I started a position in $SMCI (-2,34%) in November and December last year with a current average of $45,11 so I'm currently down around 33% on my total position…
The Bull Case:
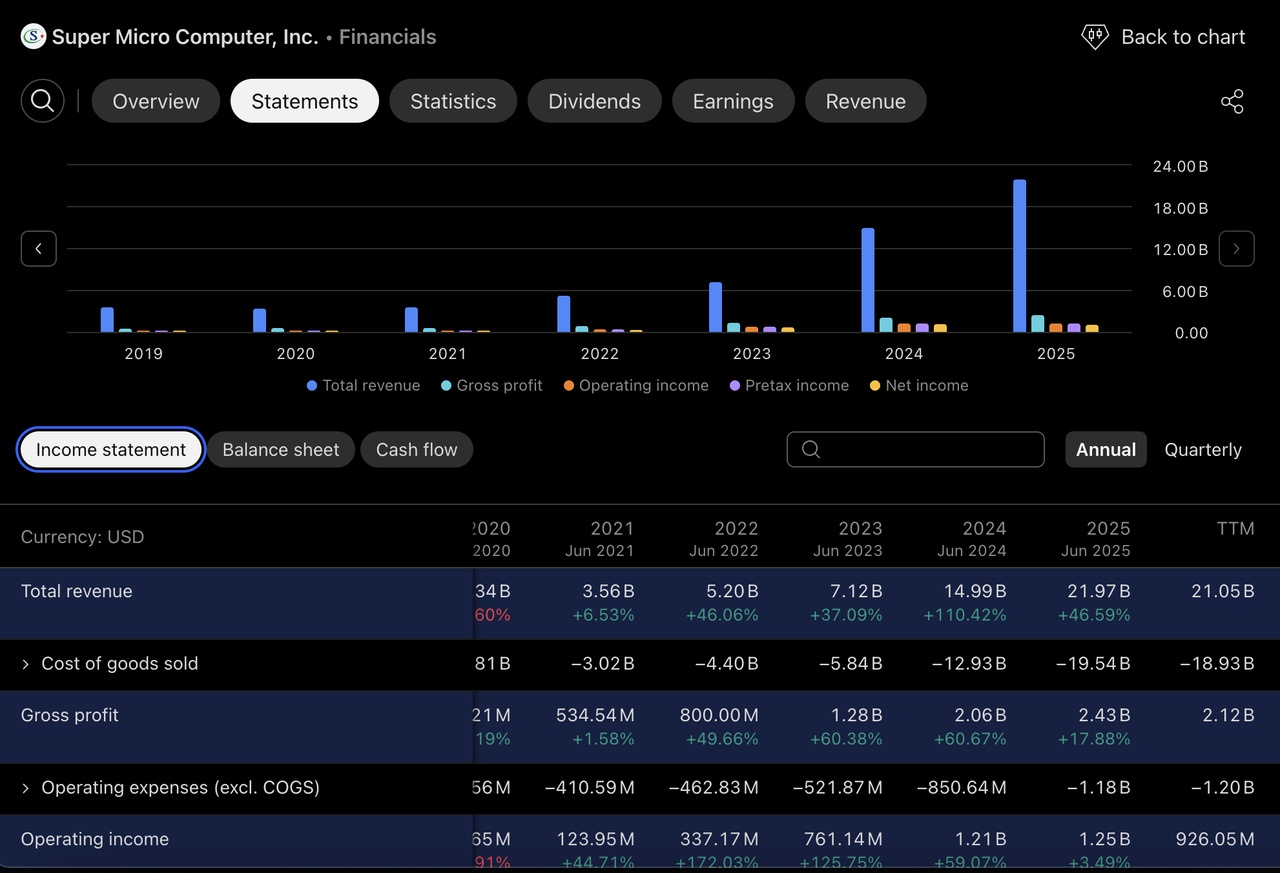
Massive Revenue Guidance: Management is still projecting $36 billion+ in revenue for fiscal year 2026. If they hit even close to that, the current market cap looks significantly undervalued.
The "Rubin" Catalyst: The recent January 2026 confirmation that $SMCI is ready for NVIDIA’s Vera Rubin and Blackwell platforms proves their partnership with NVIDIA is still rock solid.
Regulatory Cloud Lifting: The accounting and delisting drama from last year is largely in the rearview mirror now that they’ve regained compliance and secured a new $2B credit line.
The Bear Case:
Margin Compression: This is the big one. Gross margins have dipped to around 9.5% due to a brutal price war with $DELL. They are buying market share, but it’s hurting the bottom line.
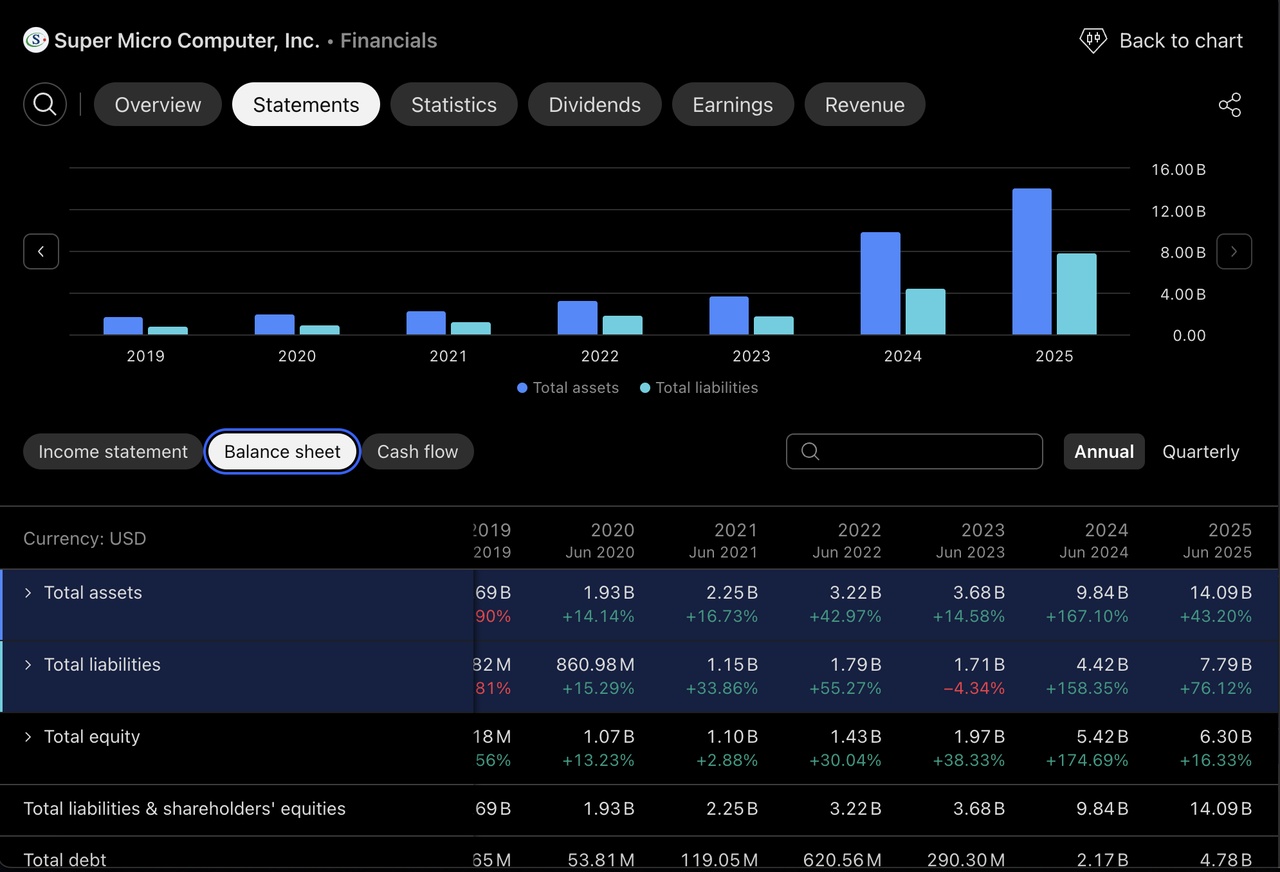
Inventory Levels: They have nearly $5.7 billion tied up in inventory. While it shows high demand, it’s a capital-heavy model that leaves little room for error.
Most analysts have a 1-year price target of around $46, which would get me back to my
average and then some. I’m leaning toward holding through the Q2 FY2026 earnings in February to see if the revenue acceleration management promised actually shows up on the balance sheet.
Anybody else having an interesting take on this one?