

so I ran it through my algorithm. $CPB (+0,34%)
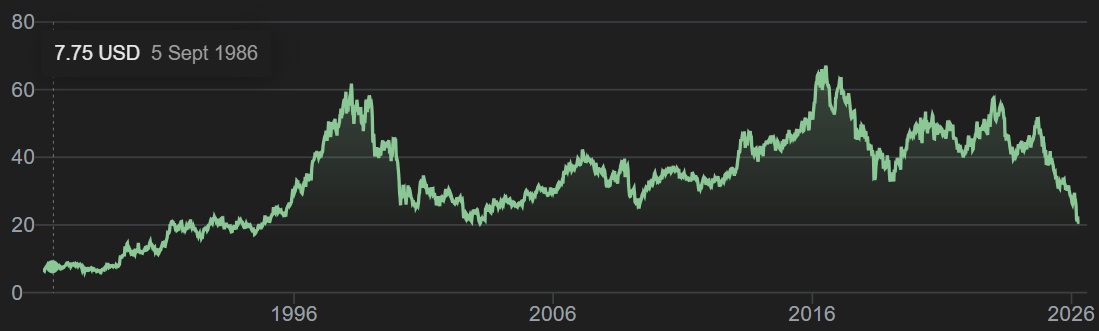
The market is pricing in an apocalypse, but the engine flagged this as a textbook "Temporary Problem."
Currently 🟢 OPTIMAL
• Quality Score: 70/100
• Opportunity Score: 85/100
• Yield: 7.34%
• P/E: 11.2x
What the market sees: A recent quarterly GAAP net loss.
What the math sees: That "loss" was driven entirely by a one-time $53M impairment charge and M&A accounting for their Sovos Brands acquisition. Adjusted earnings actually jumped 26%.
The 7.34% yield is safely covered by a 41.3% cash flow payout ratio. The 10-year dividend track record remains flawless.
The only real concern? Debt. Net Debt/EBITDA is sitting at 4.46x right now because of the acquisition. Management's primary focus needs to be deleveraging, but at an 11.2x P/E, there's a deep margin of safety here.
Anyone else adding to their $CPB position at these levels?
EDIT (April 23):
A community member (thanks @TheMaverick ) flagged something the algorithm missed —
the recent controversy ("soup for poor people") that went viral on social
media and triggered a notable boycott in the US. I re-ran the analysis with
updated news, and the Quality Score dropped from 70 → 65.
The quadrant stays 🟢 OPTIMAL, but the thesis now has a harder dependency:
management needs to address the brand damage before the next earnings call.
If the boycott holds for 2-3+ quarters, this stops being a Temporary Problem.
Worth monitoring closely.
Thanks for keeping the analysis honest. I added to the software a deep search on boikots and scandals that works perfectly in this case.