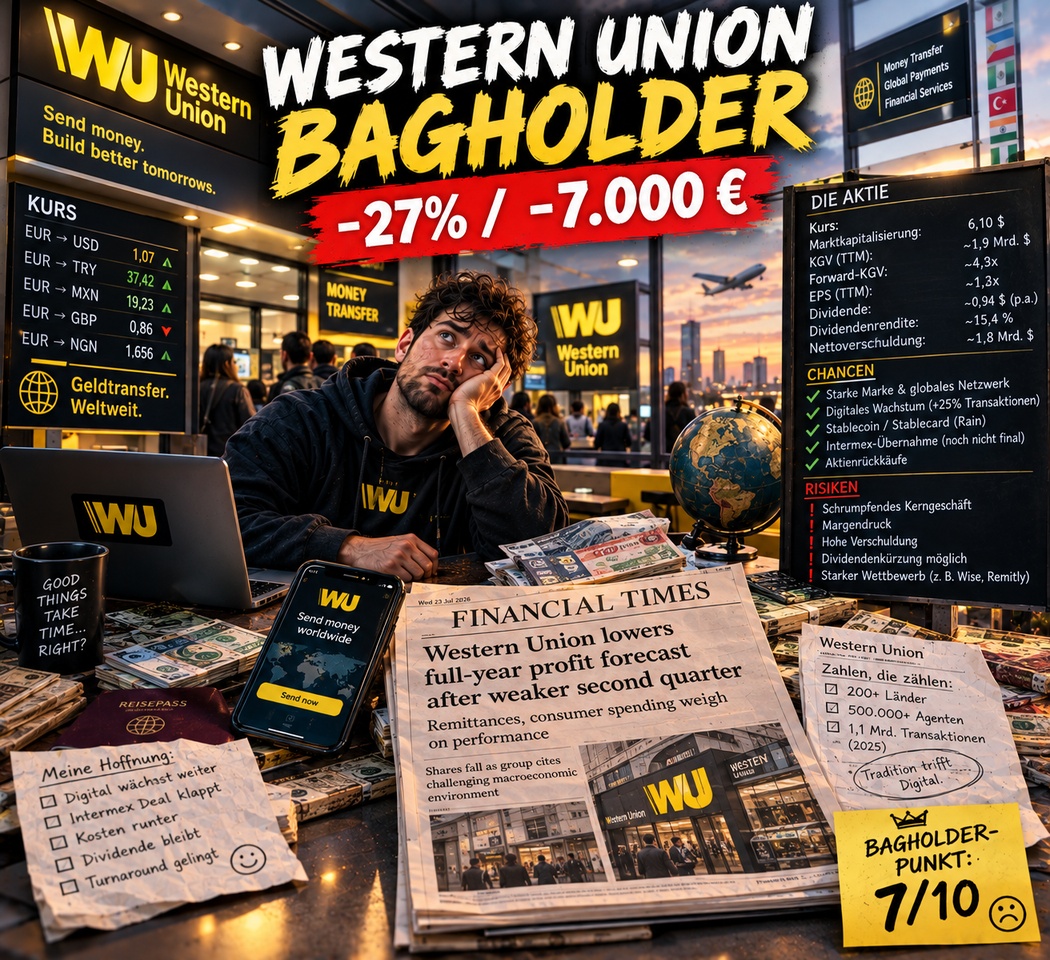
It's the fourth day of my "Bagholder Series," and we're leaving the +30% loss bracket behind. Western Union ($WU (-0,87%)) leads the pack... 👻
👉🏻 Purchase value: 26,000 euros
👉🏻 Loss: 7,000 euros (-27%)
🌎 Brief Profile
Western Union is one of the world’s best-known providers of international money transfers and cross-border payment services. The company operates in more than 200 countries and connects customers to billions of bank accounts, millions of digital wallets, and hundreds of thousands of locations worldwide. In addition to traditional money transfers, Western Union is expanding its digital business and other financial services.
📊 Fundamental Data
At a share price of approximately $6.10, the figures are roughly as follows:
Market capitalization: ~$1.9 billion
P/E ratio (TTM): ~4.9x
Forward P/E ratio: ~4.3x
EPS (TTM): ~$1.24
Adjusted EPS 2025: $1.75
Dividend: $0.94 p.a.
Dividend yield: ~15.4%
📉 How is the business performing right now?
Operationally, things are currently ranging from mixed to challenging.
In the second quarter of 2026, revenue was $1.013 billion, about 1% below the prior-year figure. At the same time, adjusted EPS fell from $0.42 to $0.31. The pressure on margins became even more pronounced: The adjusted operating margin fell from 19% to 15%.
However, there is an interesting contrast within the group:
The traditional retail business is weakening, while the digital division is growing significantly.
Branded Digital posted a 6% adjusted revenue increase in Q2 and even boosted transaction volumes by 25%. The digital business now accounts for about 32% of CMT’s revenue and 43% of transactions.
This is precisely where the company is placing its bet on the future. The company is striving to evolve from a traditional provider of money transfers via branches and agents into a global digital financial services provider. This now even includes the area of stablecoins. In August, in partnership with Rain, the company launched the Stablecard, which allows customers to hold, transfer, and spend USDPT-backed dollar values via Visa. The service initially launched in 37 markets; Western Union aims to expand to more than 60 markets by the end of the year.
The planned acquisition of Intermex is also part of this strategy. The transaction is intended to strengthen the existing business and create synergies. However, the acquisition is taking significantly longer than originally expected.
The 2026 forecast was significantly reduced following a weak second quarter:
Revenue: $4.213–4.294 billion
Adjusted EPS: $1.25–1.35 (previously $1.75–1.85 EPS)
🧐 Why might the stock be a bargain?
The market now values the company as if its traditional business model were to shrink permanently and its digital transformation were failing.
At around $6, the stock trades for less than 5 times TTM earnings and only about 4.5 times the midpoint of the current EPS forecast. At the same time, Western Union continues to have a massive global network and a well-known brand.
If the traditional business stabilizes while digital transactions continue to grow at double-digit rates, earnings could stabilize. And then a P/E ratio of 4–5x would suddenly look quite low again.
Add to that the capital return. Western Union currently pays $0.235 per quarter, or $0.94 annually. At a stock price of around $6.10, this corresponds to a dividend yield of over 15%. If the dividend can indeed be maintained, you’ll receive an enormous recurring cash flow on top of that at this price.
Furthermore, the company has already repurchased 5.7 million shares for approximately $53.7 million in the first six months of 2026. As of the end of June, approximately $722 million of the existing buyback program remained available.
For me, this suggests the following possible combination:
Digital transactions ↑ + Costs ↓ + Intermex synergies + Stabilization of the core business + Debt reduction + Dividend
If even just part of this works out, the current valuation level could be quite low.
⚠️ Why is the stock still so cheap?
Western Union is undergoing structural change—and no one knows for sure whether it will succeed. The traditional business model is losing its appeal. Today, people can send money much more easily and cheaply via an app.
Revenue is declining, and the operating margin is under pressure. On top of that is the debt. As of June 30, Western Union had approximately $2.7 billion in gross debt. The interest burden is therefore not entirely irrelevant—especially when operating profit is under pressure at the same time and overall interest rates are rising significantly again.
The high dividend yield of 15% can also be interpreted as a warning sign at this time.
The market evidently assumes that the current dividend may not be sustainable at this level. Should management have to reduce the dividend again, the stock price could come under significant pressure once more.
The Intermex acquisition is also not a sure thing. It is intended to strengthen the business and generate synergies, but the regulatory delays show that the transaction is not yet a done deal.
🎯 My Bagholder Verdict -> 7/10 Bagholder Points 🤑
For me, Western Union is currently one of the most exciting—but also one of the riskier—value bagholders in my portfolio.
The crucial question, therefore, isn’t whether Western Union is profitable today—it clearly is. The real question is: Can the company successfully transition from a traditional money transfer provider to a digital global financial services provider?
If so, I believe the current valuation is significantly too low. If not, then the stock will become a classic value trap.
P.S.: Western Union has been in my portfolio for quite some time. Due to the high dividend (which is paid quarterly), my actual loss is probably closer to 20–15%.