2Mês·

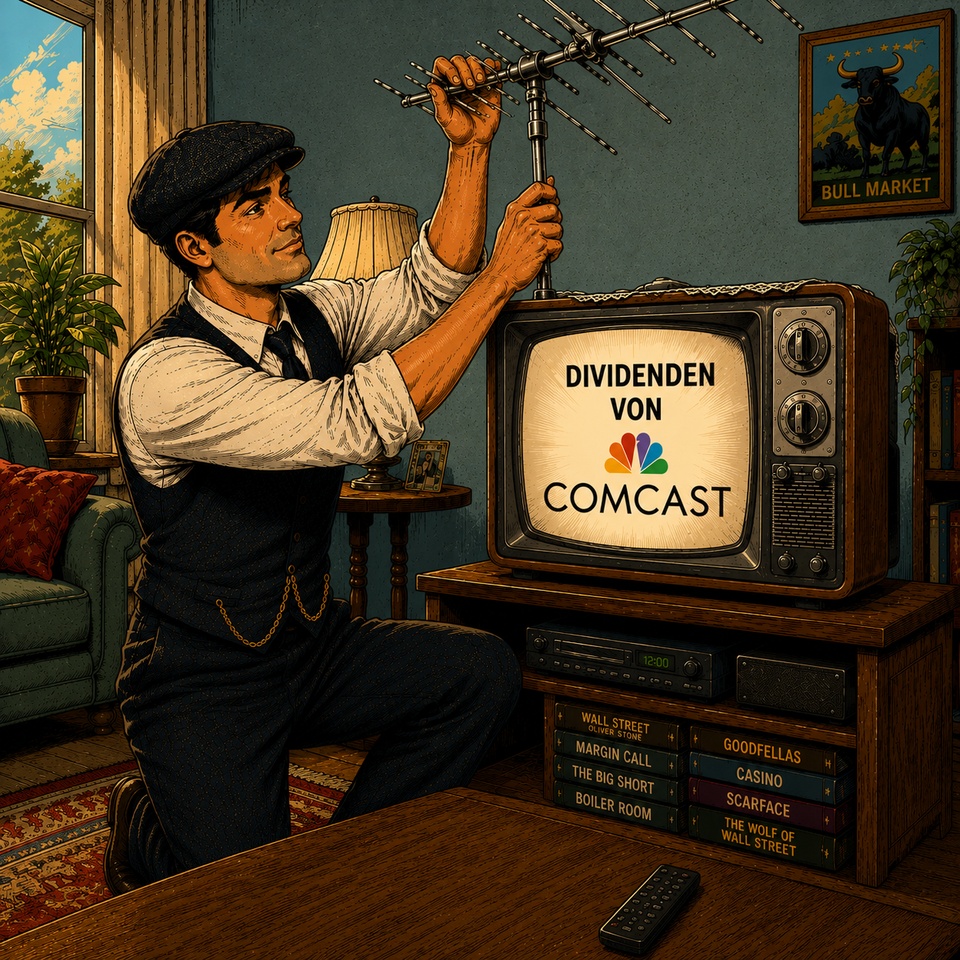
Comcast Dividend and "News"📺

Comcast is on a
mission..

Meanwhile, I’m watching from the sidelines and paying my $CMCSA (-0,06%)
dividends for Netflix subscriptions 🤪

No, no—the reality is, I accumulate the dividends and reinvest them quarterly in larger amounts into specific stocks.


With Comcast , there was recently a spin-off. I sold all of the spin-off shares as soon as they hit my portfolio. TV isn’t my thing.


Comcast plans to split into a total of 3 companies ...:


Comcast: Internet, mobile communications, and everything related


NBCUniversal: Movies, streaming, theme parks, and everything related


Versant: TV networks and other challenges that come with them.


The spin-offs are happening for one reason: The market values the individual business units more highly than the group as a whole. Comcast wants to eliminate the so-called conglomerate discount and enable each company to focus entirely on its core business.
attachment
22.07
Comcast logo
Recebido x299 Dividendos em US$ 0,33
US$ 98,67
15
17 Comentários

imagem de perfil
I'd rather just buy a company than get a subscription! Beginner's mistake
•
1
•
imagem de perfil
•
1
•
If $CMCSA focuses so heavily on the growing mobile communications market and spins off its loss-making divisions, could that also have a positive impact on the stock price, which hasn't been looking so great lately? Thanks for the introduction; I hadn't had it on my watchlist until now.
•
1
•
imagem de perfil
@imarkation I'm starting to feel optimistic if Comcast can at least manage to hold onto its subscriber base. Things have been pretty weak in recent quarters. Streaming, on the other hand, is growing.
••
imagem de perfil
@imarkation The earnings report came out today... In my opinion, they're finally back in the black.
•
1
•
imagem de perfil
@imarkation So NBC Universal is more the part with growth potential, and it’s not operating at a loss either. Versant is also far from operating at a loss (revenue of about $7.0 billion and EBITDA of about $2.5 billion, with a margin of about 35%). And then there’s the core Comcast business with broadband internet, mobile services (Xfinity Mobile via Verizon), business services, and infrastructure.

So as an investor, you can choose what you want to focus on 🤓 What I find exciting are the theme parks and Comcast’s infrastructure. On one hand, a focused media giant with growth potential; on the other, a pure-play telecommunications and network provider with very high margins, extremely stable and predictable cash flows, and a focus on dividends and share buybacks. (I also h $VZ ) in my portfolio.)

The point of this allocation isn’t to offset losses, but rather to capitalize on stock market valuation (multiple expansion) 💰
••
@finanzperpetuum Thanks for the explanation—it can sometimes be a hassle to do in-depth research on my phone. I'd be interested in Telco; I already have Netflix for streaming, and I don't see much potential in live TV streaming or the parks. We'll see how it goes :-)
••
imagem de perfil
How long have you had Comcast?
The chart for the last few months looks pretty scary—why are the numbers just dropping?
•
1
•
imagem de perfil
@Smudeo I’ve had Comcast since Q3 2024. Up until then, the numbers looked pretty solid, and I actually really like the cash flow. Equity exceeds long-term liabilities. But it turned out that customers are tending to switch to the competition. Business is stagnating in broadband and TV. Meanwhile, the situation with customers is improving—so they’re slowly getting it under control. Peacock, the streaming division, is also growing rapidly and will turn a profit for the first time this year.
Still, I have a feeling they’ll improve significantly in the future.
•
1
•
imagem de perfil
@PoorDad Thanks. I didn't pay any attention to the stock until Norbert recommended it.
••
I also hold a position in $CMCSA because of its impressive free cash flow, extremely attractive valuation, and the associated share buybacks and dividends. However, I’m keeping this position relatively small because I’m not fully convinced.

The question is whether they can turn things around operationally. After the spin-off, the remaining businesses will be mobile communications, Xfinty TV, and broadband Internet.

There are other providers active in these markets as well, and the price war in the mobile communications sector is rather destructive…
••
imagem de perfil
@AlterFalter24 Competition is fierce, coming from all directions. While streaming is growing rapidly, it will still be a challenge. For example, I’ve cut my Verizon position in half because I think SpaceX will take market share away from VZ in the future. And VZ’s margins are already extremely thin anyway.
•
1
•
imagem de perfil
@AlterFalter24 look at the heutigen Earnings ✅
•
1
•
@PoorDad I'll do that—thanks!

Next week, I'll be focusing mainly on my biggest "project" $OWL
••
imagem de perfil
@PoorDad I can't imagine SpaceX taking a large share of the market away from other mobile carriers. At least not with the technology as it stands today. They’ll certainly be the best choice in rural areas and in niche markets, but Verizon’s lucrative core business—millions of mobile contracts in metropolitan areas and high-margin B2B customers—will remain untouched by SpaceX.

Verizon’s real challenge lies more in paying off its 5G debt. And given its cash flow, $VZ remains a reliable long-term dividend payer. My opinion 🤓
•
1
•
imagem de perfil
@finanzperpetuum I get what you’re saying, which is why I’ve left about 4,500 € in VZ to keep benefiting from the current situation. My problem with VZ is that the company is barely growing organically. If SpaceX takes market share away from VZ in the future, VZ will have to make up for that loss somewhere. Without growth, that’ll be tough.

VZ is investing in AST, but AST first has to get to where SpaceX has already gotten to. And even AST is still dependent on SpaceX. That means that some of the money VZ invests will end up with SpaceX anyway.

There are just so many factors that bother me about VZ.
••
$VZ I do, too. My investment thesis is that their new CEO, Dan Schulman, will slash costs significantly and that they’ll use their free cash flow to pay down debt.

But overall, the upside is limited; you just get a high dividend that, at best, grows by more than 2%.

I’ll sell once the dividend yield reaches 5% and then look for something more attractive.
••
Participar na conversa