Lam Research ($LRCX (-3,35%)) is not just a semiconductor supplier - it is one of the four gatekeepers of the entire chip industry. Without LRCX machines, there is no memory, no logic, no AI chip.
The Q3 FY26 figures (reported 22.04.) were the fourth beat in a row: record sales, WFE outlook raised upwards, customer support above $2 bn for the first time, then the share fell -6%. Clanship with ASML due to China worries.
Operational strength meets sector worries - an exciting constellation.
⚙️ What is Lam Research doing?
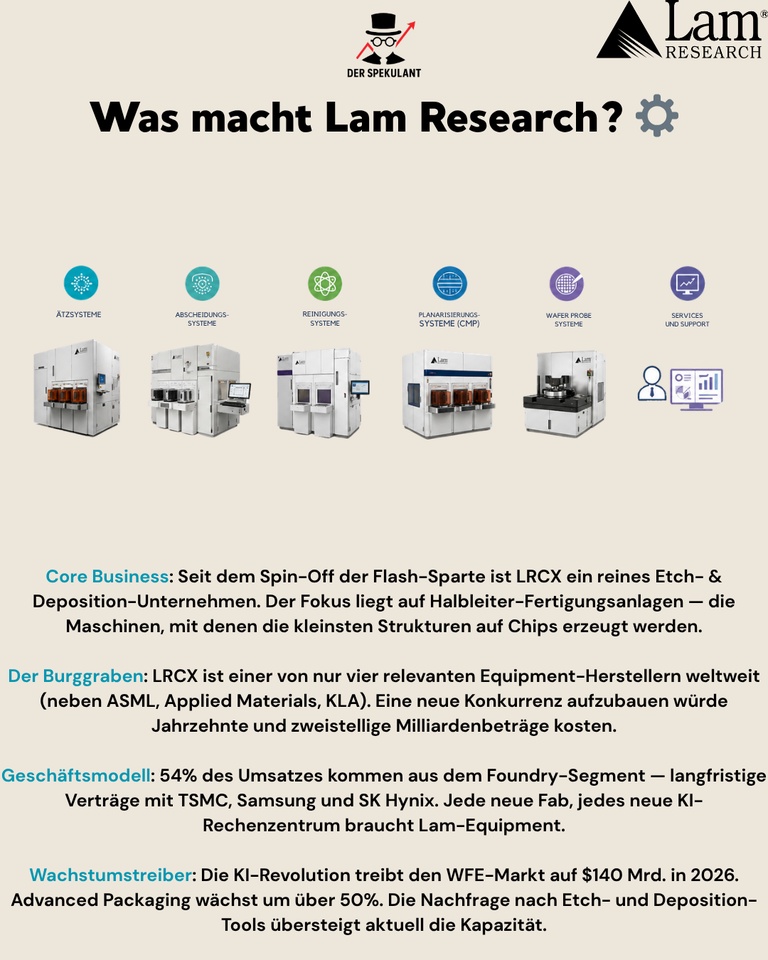
➡️ Core Business - Etch & Deposition Equipment:
LRCX is one of the four dominant suppliers worldwide (alongside ASML, Applied Materials, KLA) for semiconductor manufacturing equipment. Specialized in etch and deposition processes - the steps used to create the smallest structures on chips.
→ Mission Critical Equipment + very high entry barriers.
➡️ Oligopoly position:
There are only a handful of players in the semiconductor equipment market. LRCX is the market leader in etch together with Applied Materials. Establishing new competition would take decades and cost tens of billions.
→ Structural moat + pricing power.
➡️ AI investment cycle:
Every new HBM4 chip, every NAND memory and every advanced packaging solution requires Lam equipment. The customer support area (maintenance, upgrades, spare parts) has exceeded USD 2 billion per quarter for the first time - that is recurring revenue.
→ AI-Capex directly coupled + increasing service share.
➡️ Technology leadership:
In advanced packaging (HBM stacking, 3D packaging), LRCX is growing by over 50% in 2026 according to its own guidance. In NAND, the next generation 1C-node DRAM will be produced exclusively with Lam tools.
→ Innovation lead + sold-out roadmap.
📊 Figures & growth (Q3 FY26)
📈 Turnover (Q3 FY26):
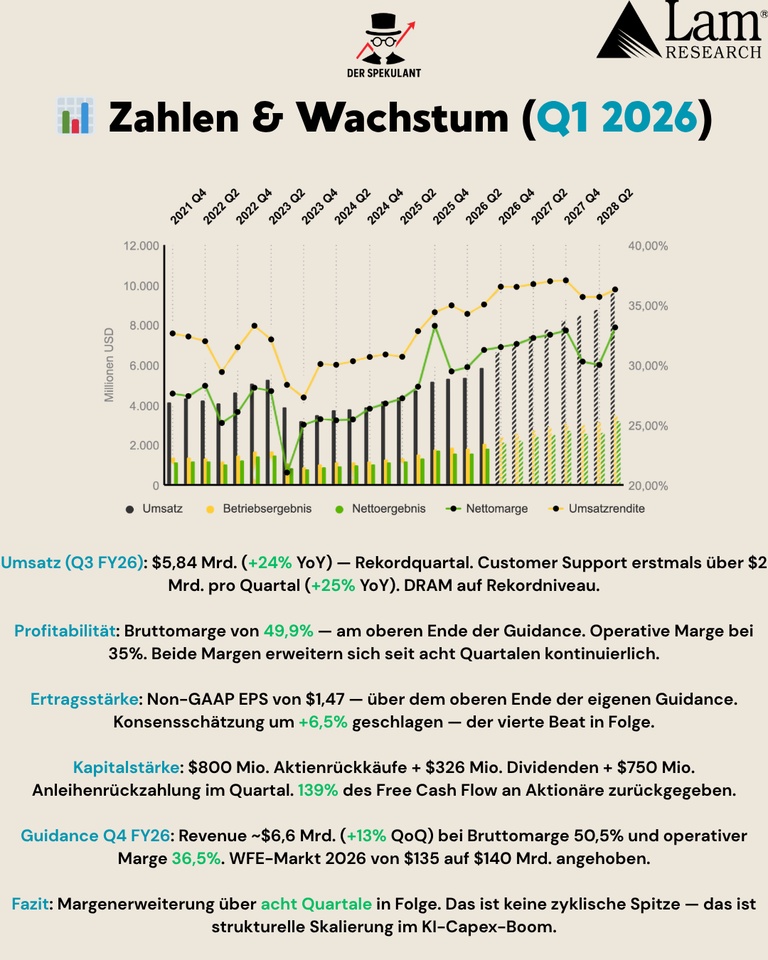
USD 5.84 billion (+24% YoY) - record quarter. Customer Support exceeds USD 2 bn per quarter for the first time (+25% YoY). Foundry share 54%, Memory 39% - DRAM at record level.
📊 Profitability:
Gross margin of 49,9% - at the upper end of the guidance. Operating margin at 35%. Both margins have been expanding continuously for eight quarters.
📈 Earnings power:
Non-GAAP EPS of USD 1.47 - above the upper end of the company's own guidance. The consensus estimate was raised by +6,5% the fourth beat in a row.
💰 Capital repatriation:
USD 800 million in share buybacks + USD 326 million in dividends + USD 750 million in bonds repaid in the quarter. 139% of free cash flow returned to shareholders.
📍 Guidance Q4 FY26:
Sales ~6.6 billion USD (+13% QoQ) with gross margin 50,5% and operating margin 36,5%. WFE market 2026 raised from USD 135 bn to USD 140 bn - with an explicit "bias to the upside".
Conclusion: Margin expansion for eight quarters in a row. This is not a cyclical peak - this is structural scaling in the AI capex boom.
🟢 The opportunities
🟢 AI Capex Supercycle:
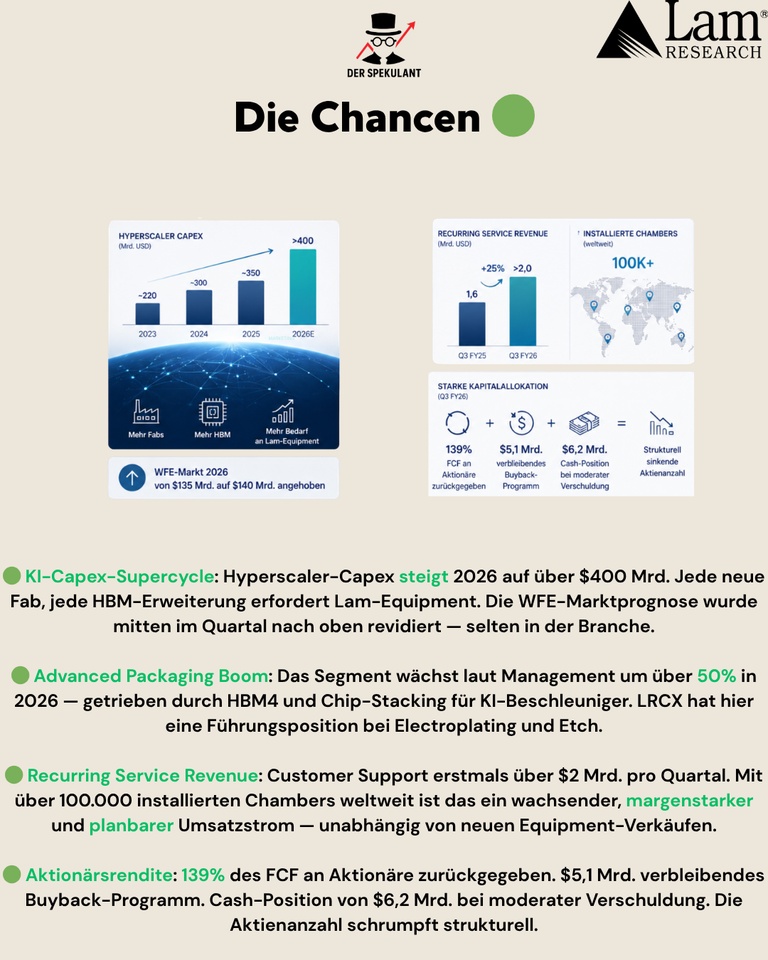
Hyperscaler capex expected to rise to over USD 400 billion in 2026. Every new fab, every HBM expansion, every advanced packaging step requires Lam equipment. The WFE market forecast was revised upwards in the middle of the quarter - rare in the industry.
🟢 Advanced packaging boom:
According to management, the segment will grow by over 50% in 2026 - driven by HBM4 and chip stacking architectures for AI accelerators. LRCX has a leading position in electroplating and etch.
🟢 Recurring Service Revenue:
Customer Support Business has exceeded USD 2 billion per quarter for the first time. With over 100,000 Chambers installed worldwide, this is a growing, high-margin and predictable revenue stream - regardless of new equipment sales.
🟢 Shareholder return:
139% of FCF returned to shareholders. USD 5.1 billion remaining buyback program. Cash position of USD 6.2 bn with moderate debt. The number of shares is shrinking structurally.
🔴 The risks
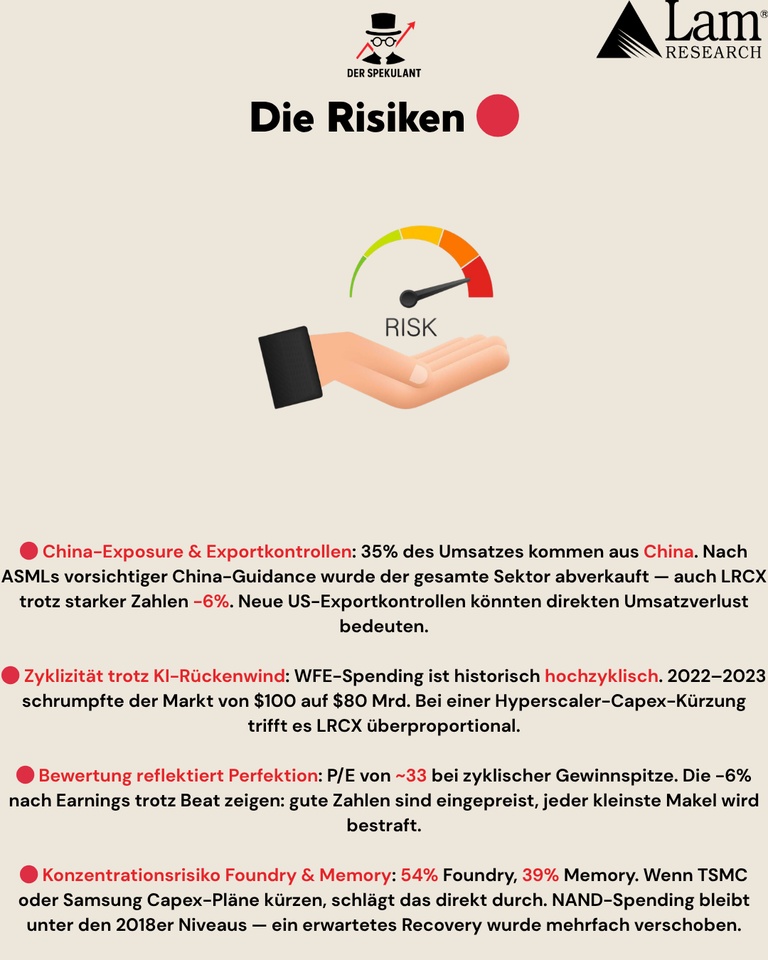
⚠️ China exposure & export restrictions:
35% of sales come from China. After ASML's cautious China guidance two weeks ago, the entire sector was sold off - including LRCX despite strong figures -6%. New US export controls could mean a direct loss of sales.
⚠️ Cyclicality of the semiconductor industry:
WFE spending is historically highly cyclical. In 2022-2023, the market shrank from USD 100bn to USD 80bn. Even with AI tailwinds: LRCX will be disproportionately affected by a hyperscaler capex cut.
⚠️ Valuation & sentiment risk:
P/E of ~33 at cyclical earnings peak. The share is vulnerable despite strong figures - the -6% drop after earnings shows: good figures are priced in, every slightest flaw is punished.
⚠️ Concentration risk Memory & Foundry:
54% foundry, 39% memory. If TSMC or Samsung cut capex plans, this will have a direct impact. NAND spending remains below 2018 levels - an expected recovery has been postponed several times.
💡 Conclusion & outlook
Lam Research delivers record operating results - gross margin has been expanding for eight quarters, WFE market revised upwards, Customer Support breaks the 2 billion mark. The question is not whether business is strong, but how much of it is already priced in.
🔹 Short term:
Sentiment driven by ASML kinship and China headlines. Despite Q3 beat -6% after earnings - the sector is currently not trading on fundamentals.
🔹 Long term:
One of the four gatekeepers of the entire chip production. As long as AI compute grows exponentially, TSMC, Samsung and SK Hynix will need new fabs. And new fabs need Lam equipment.
🎯 Investment case:
Margin expansion over eight quarters + Customer Support exceeds USD 2 bn for the first time + Advanced Packaging +50% in 2026 + WFE outlook revised upwards → operationally at record level, strategically at the center of the AI-Capex boom.
💬 Community question:
👉 Structurally indispensable equipment player in the AI supercycle, currently attractively valued due to China clan detention
or
👉 with P/E 33 and 35% China exposure, a cyclical risk that has only just begun to materialize?
I look forward to your assessment 👇
🗞️ Newsletter: derspekulant.beehiiv.com