
On November 4, CVS Health released its third-quarter 2026 earnings report. And I think it’s worth taking a closer look at the company.
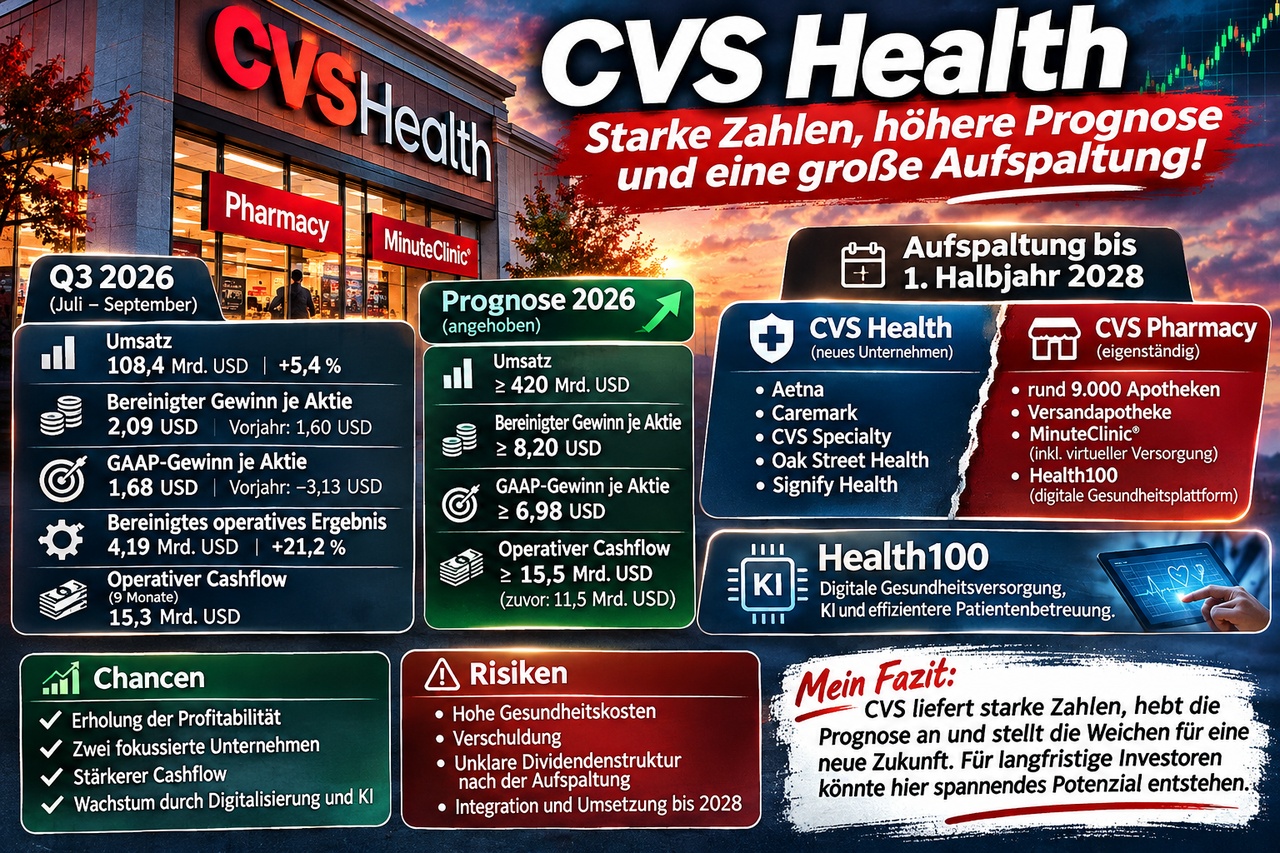
From July through September, revenue totaled $108.4 billion. That represents a 5.4% increase compared to the third quarter of 2025.
I find the earnings trend even more interesting: Adjusted earnings per share rose from $1.60 in the same quarter last year to $2.09 now. At the same time, management has raised its earnings forecast for the full year 2026 to at least $8.20 per share.
What concerns me even more, however, is the spin-off announced today, which is scheduled to take place by the first half of 2028.
CVS plans to split into two independent, publicly traded companies. On one side will be the insurance business, comprising Aetna and Caremark; on the other, the pharmacy and healthcare business, with approximately 9,000 stores.
Added to this are investments in digital healthcare and AI, which could certainly offer long-term potential.
Of course, not everything is rosy. High healthcare costs, debt, and uncertainty surrounding future dividends remain issues that cannot be ignored.
But as a long-term investor, it’s precisely these kinds of situations that I find interesting. A company improves its third-quarter results, raises its full-year forecast, and at the same time plans a fundamental realignment. Nevertheless, market sentiment remains subdued.
I therefore wonder whether CVS is currently undervalued and whether the planned spin-off could create significant long-term value for shareholders.
In any case, I’m keeping a close eye on it. Sometimes the most interesting opportunities arise when others are still uncertain.
What’s your take on CVS? Buy, hold, or wait and see?
#CVSHealth
#Aktien
#Dividenden
#Dividendenstrategie
#Börse
#Investieren
#ValueInvesting
#PassivesEinkommen
#FinanzielleFreiheit
#Aktienanalyse
#USStocks
#LangfristigesInvestieren
#StockMarket
#Dividendeninvestor
#Getquin
