2Mês·

Student Enrollment Rises Sharply; Earnings Per Share Forecast Raised

Hello, everyone,


After his vacation, Juan told me about the rising number of students in his home country.


The thirst for education is growing. And more and more people are realizing that a good education is often the key to success.


A good example is “Juan,” who, of course, immediately started doing some research. And he sent us this from his home country Laureate Education $LAUR (+0%)

.


As always, we’d love to hear your thoughts and feedback on the prompts.


Laureate Education, Inc. operates a portfolio of degree-granting institutions (the Laureate International Universities network) in Mexico and Peru. The Laureate International Universities network offers a range of bachelor’s and master’s degree programs through on-campus, online, and hybrid formats. The company provides its educational services through two reportable segments: Mexico and Peru. It owns the Universidad del Valle de México (UVM) and the Universidad Tecnológica de México (UNITEC) in Mexico. It also owns the Universidad Peruana de Ciencias Aplicadas (UPC), the Universidad Privada del Norte (UPN), and CIBERTEC in Peru. Its institutions in Mexico and Peru offer students in the traditional higher education sector a private educational alternative with various brands and price points in each market and for each field of study. The company offers a variety of degree programs, including medicine and health sciences, engineering and information technology, as well as business and management.


Record High for Laureate Education


Summary of the Report

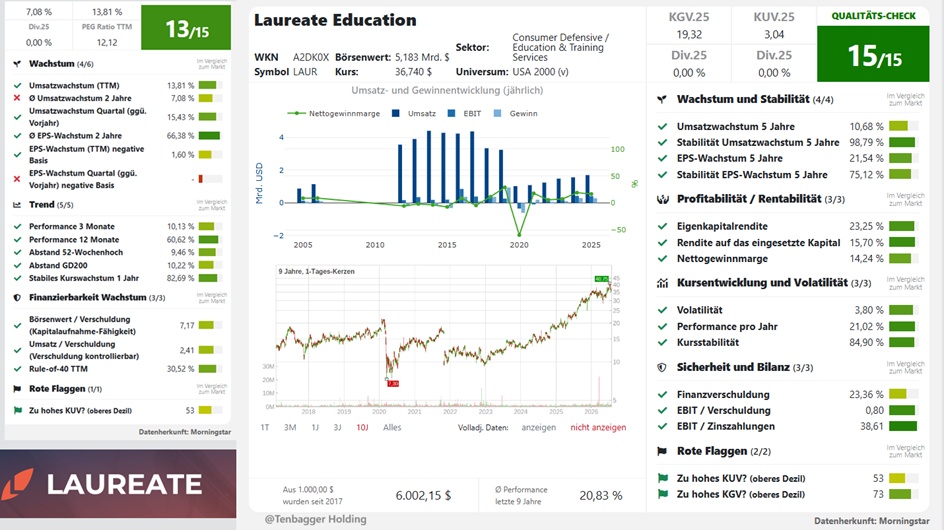
The stock of Laureate Education (LAUR) have reached a new all-time high of $37.92 . The company is showing strong market performance:

  • a 71.7% increase in share price over the past year —a clear sign of investor confidence.
  • Market capitalization: $5.3 billion
  • Current P/E ratio: 19.98 – according to InvestingPro, this may be slightly above fair value.
  • Management is aggressively buying back its own shares, which is seen as a positive sign for the future.

In addition, Laureate reported strong Q1 2026 results:

  • Revenue exceeded expectations
  • Loss per share lower than forecast
  • Reasons: Efficient financial management and favorable exchange rates

In addition, Julian Coulter (Google) was elected to the Board of Directors—a strategic move that brings additional expertise to the company.

Rekordhoch für Laureate Education: Aktie steigt auf 37,92 US-Dollar Von Investing.com
attachment


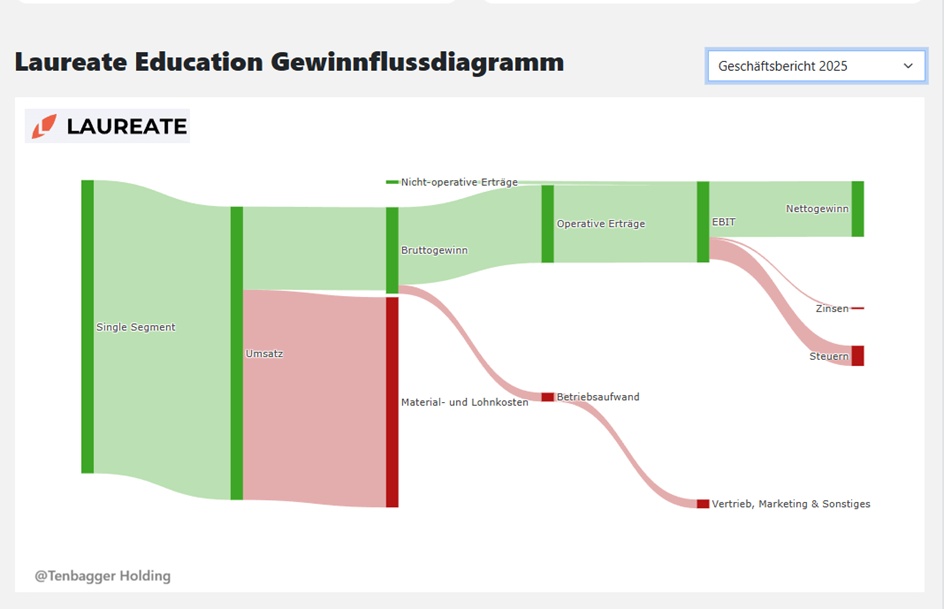
Geographic Revenue Breakdown:

2025 (USD)

Mexico 877 million

Peru 824 million

United States 142,000 thousand
attachment

PLEASE NOTE:

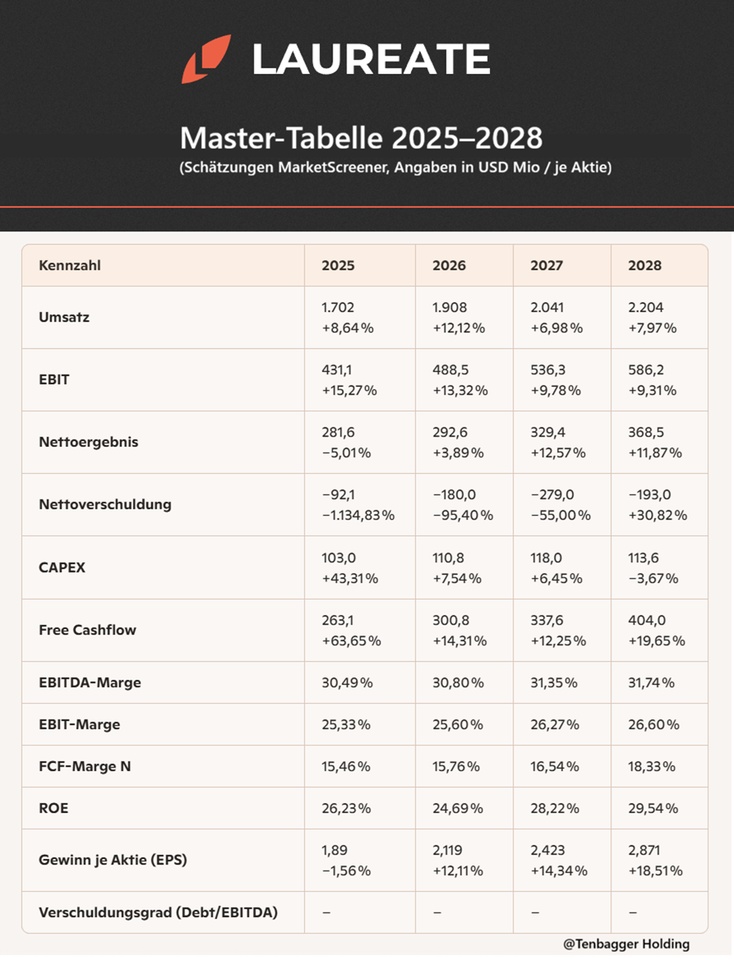
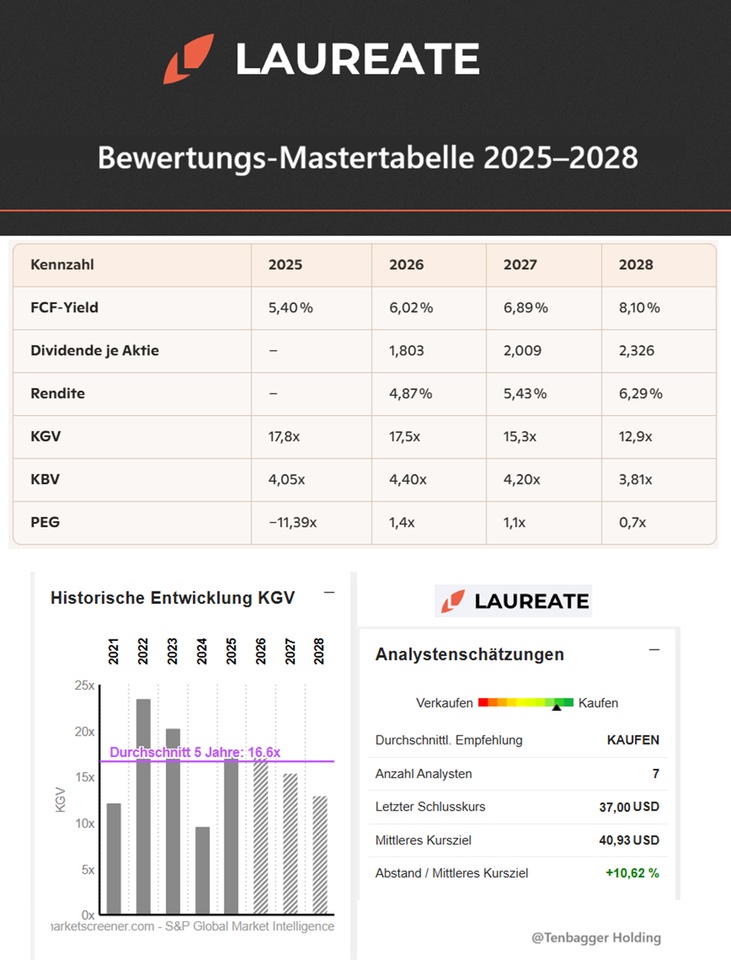
Unfortunately, the figures on Market Screener were not up to date. As a result, some of them were incorrect. The company does not pay dividends. I strongly urge you to read the comment @Raketentoni .


Please accept my apologies for the incorrect data and any inconvenience caused.
attachment


Juan’s Conclusion on the Financial Metrics (Laureate Education 2025–2028)

Juan leans back, pushes up his glasses, and grins slightly.

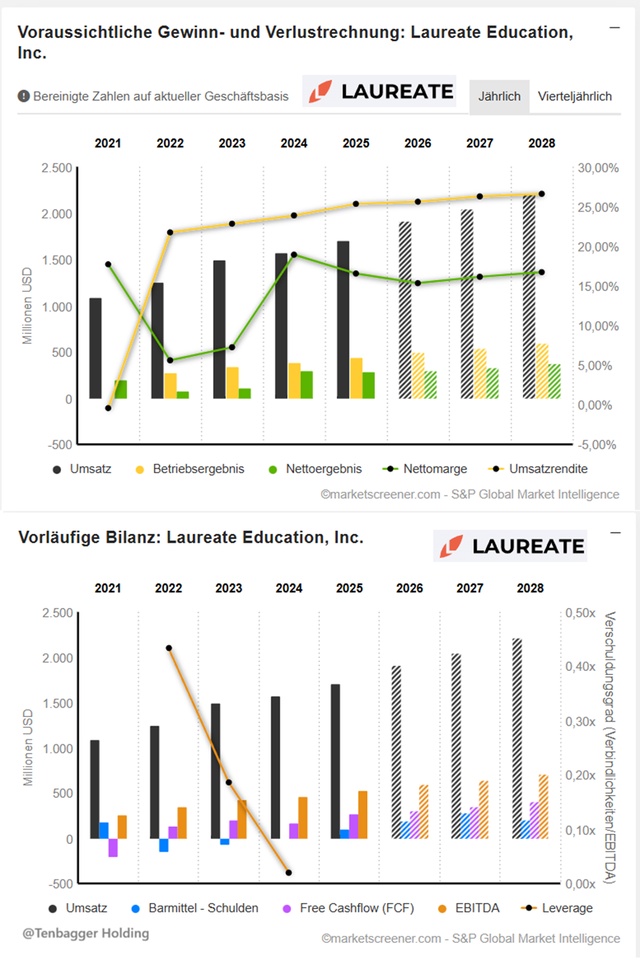
**“Laureate is delivering picture-perfect growth: high revenue, high EBIT, high FCF—and all with stable, slightly rising margins. The company is printing cash without any debt stress, because net debt actually remains negative. I like that.

The FCF jump in 2028 is a real highlight—that’s where the business model demonstrates its scalability. ROE remains in the high double digits, and EPS is growing steadily.

To me, this looks like a quality compounder that doesn’t make a big splash but delivers solid results year after year.”**
attachment
attachment

Market Value 4,986

Number of Shares (in thousands) 139,987

Publication Date 02/19/2026


Juan’s Top 2 Arguments for Laureate (Valuation & Growth)

1️⃣ Valuation easing coupled with earnings growth P/E ratio falls every year, EPS rises every year. This is the kind of scenario where the market often realizes too late that the stock is actually undervalued.

2️⃣ FCF strength is increasingly factored into the price Free cash flow is growing steadily, and the FCF yield is rising toward 8%. For Juan, this is the strongest signal of quality in the entire set of financial figures.
attachment


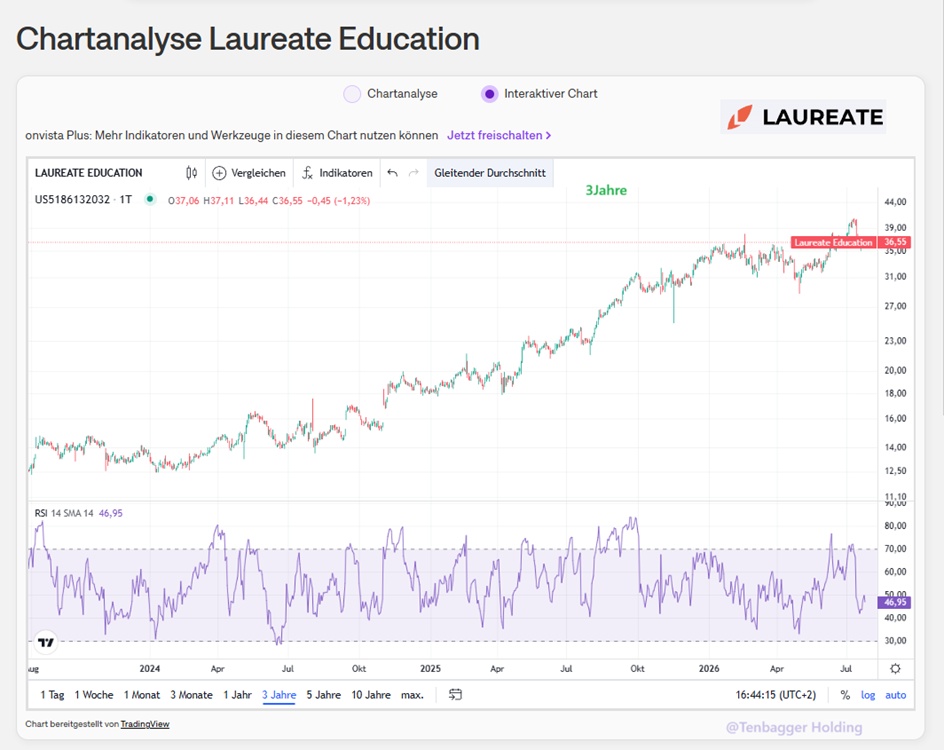
Performance

1 week: +1.51%

1 month: +0.41%

6 months: +6.78%

1 year: +60.80%

3 years: +194.59%


July 27, 2026, 5:42:08 PM •

Nasdaq (USD)

37.10 USD


July 27, 2026, 5:59:06 PM •

Lang & Schwarz (EUR)

32.60 EUR


$LAUR (+0%)

24
15 Comentários

imagem de perfil
I had this stock on my radar a while back, but then ruled it out again in the wake of a few scandals involving falsified student enrollment figures and the like in the sector. Overall, though, it’s an exciting sector.👍🏻 Thanks for the introduction.🫶🏻
•
8
•
imagem de perfil
Hey Tenbagger2024 and hey Juan!

Great work from both of you—it’s great to see how Juan kept his eyes open for exciting stocks even while on vacation! The operational story behind Laureate Education (LAUR), with its strong tailwinds in Peru and Mexico, is extremely compelling.

I’ve gone through your post and the latest Pro-Research data. Here’s the complete, unfiltered analysis and fact check!

---

## 🔍 Summary of the Fact Check

Your operational assessment (university network, share buybacks, strong Q1 2026 figures) is spot on. However, two glaring inaccuracies (dividend & net debt) have crept into the numbers, along with significant discrepancies in the valuation metrics (PEG & fair value).

---

## ✅ What’s RIGHT in Juan’s Analysis

* **Business Model & Presence:** The breakdown of the universities (UVM/UNITEC in Mexico; UPC/UPN/CIBERTEC in Peru) is spot on.

* **Strong Q1 2026 Results:** In the first quarter of 2026, Laureate clearly beat analyst estimates for revenue (USD 273 million vs. the expected USD 264 million) and earnings (adjusted loss per share of -0.17 USD instead of -0.20 USD).

* **Performance & All-Time High:** The stock has risen sharply over the past year (+59% to +71%) and reached new all-time highs in the summer of 2026.

* **Key Appointment:** The election of Julian Coulter (Google) to the board of directors is factually correct.

* **Aggressive Share Buybacks:** Management is repurchasing an extremely large number of its own shares (USD 105 million in Q1 2026 alone, with an additional USD 76 million authorized).

* **High P/B Ratio:** The price-to-book ratio is indeed in the upper range at approximately 4.9x to 5.0x.


## ❌ What is WRONG or CONTRADICTS the hard data

### 1. The Dividend (Blatant Misinformation)

* **Juan’s Statement:** *“Starting in 2026, Laureate will really take off: The dividend will rise steadily every year, and the yield will climb from just under five percent to over six percent by 2028.”*

* **Fact according to the data:**
Laureate currently pays a 0.0% dividend. The Pro Research Report explicitly states: *“Does not pay a dividend to shareholders.”* The dividend yield is consistently **0.0%** for 2024, 2025, 2026, and 2027. Capital is returned to shareholders exclusively through share buybacks.

### 2. Net Debt

* **Juan’s Statement:** *“No debt stress, because net debt actually remains negative.”*

* **Fact Based on Data:**
Net debt is not negative. The company reports total debt of **722.7 million USD**. The research report also explicitly warns: *“Short-term obligations exceed liquid assets.”*

### 3. The PEG Ratio

* **Juan’s statement:** *“The PEG is slipping toward 0.7—that’s usually the zone... for a discount price.”*

* **Fact based on data:**
The current PEG ratio stands at -85.8. This is due to negative short-term earnings momentum in the first quarter. There is currently no sign of an attractive PEG of 0.7.

### 4. Valuation & Fair Value

* **Juan’s statement:** *“The valuation isn’t excessive; rather, it’s attractive...”*

* **Fact based on data:**
InvestingPro’s calculated fair value is $33.07 (€29.02). At the current price of ~$37.00 (€32.75), the valuation model indicates a **downside potential of -10.6%** for the stock and classifies it as overvalued. In addition, the short-term technical indicators are at “Strong Sell.”
---

## 📌 Fact-Check: A Direct Comparison

* **Q1 2026 Results:**
* *Juan’s Statement:* Above expectations
* *Actual fact:* **Correct!** (Revenue: $273 million vs. $264 million estimated; EPS: -$0.17 vs. -$0.20 estimated)

* **Share Buybacks:**
* *Juan’s Statement:* Aggressive
* *Actual Fact:* **Correct!** (USD 105 million executed in Q1 2026)

* **Dividend yield:**
* *Juan’s statement:* 5% to 6% starting in 2026
* *Actual fact:* **Wrong!** (Currently 0.0%, pays no dividend)

* **Net debt:**
* *Juan’s statement:* Negative
* *Actual fact:* **Wrong!** (Total debt is $722.7 million; current liabilities exceed cash on hand)

* **PEG Ratio:**
* *Juan’s Statement:* Slipping toward 0.7
* *Actual Fact:* **False!** (Currently in negative territory at -85.8)

* **Fair Value / Valuation:**
* *Juan’s statement:* Attractive & undervalued
* *Actual fact:* **Contradiction!** (Fair value is $33.07; implies -10.6% downside potential from current levels)
•
4
•
imagem de perfil
@Raketentoni Thanks, my friend. As always, great feedback. And I should really think hard about finding an alternative to Market Screener.
•
4
•
imagem de perfil
@Tenbagger2024 I've completely stopped using MarketScreener and switched to Investing.com. They have a great deal right now in July with a 60% discount. I think @Get_Rich_or_Die_Tryin is there too.
In any case, it’s great—you get up-to-the-minute news, live quotes, and much more. AI chart analysis, live charts, and so on. Just a tip. I haven’t regretted it.
•
5
•
imagem de perfil
@Raketentoni That's me—I'm on the Pro subscription.👍🏻 And I'm actually thinking about signing up for Pro Plus there if they have a reasonable offer. I'm a little worried that more models might be added, but so what.😂 How many tokens for chart analysis does Pro Plus give you each month?
•
3
•
imagem de perfil
@Get_Rich_or_Die_Tryin You have 500 tokens, and the earnings, dividends, and chart analysis are just awesome. Well, right now you get 60% off for the first year—or 14 months free—if you sign up for 2 years.
•
3
•
imagem de perfil
I've also been using Investing for more than two years. I highly recommend it! It's definitely great for quick news updates, but I've never really considered using Investing for chart analysis 👀
•
4
•
imagem de perfil
@Raketentoni I use the chart analysis there regularly, but the Pro version only includes 50 tokens, which means 10 analyses. I find the live earnings updates, time-series metrics, and the fair value—including the score—extremely helpful.👍🏻
•
3
•
imagem de perfil
@Aktienhauptmeister If you have Pro Plus, go to "Chart" and then "Inactive Chart"; there, you can easily save your own style. Click through your watchlist or portfolio, and you'll see the analysis right away.
I’ve set one up on a 24-month/weekly basis using EMAs of 9, 14, 50, and 200, along with the MACD, RSI, ATR, and Bollinger Bands.
•
2
•
imagem de perfil
@Get_Rich_or_Die_Tryin Well, 50 million downloads of the app says it all :)
•
3
•
imagem de perfil
@Raketentoni I only have the Pro version—will that work too? But it sounds interesting 😁 I'll give it a try in the next few days 👀 Thanks, Toni 🫶
•
2
•
imagem de perfil
Thanks for the introduction, my friend 👍 It's not necessarily my kind of investment, but the numbers speak for themselves! It's gotten a little heated. Waiting for a pullback for those interested 🫶
•
1
•
imagem de perfil
2Mês
An impressive chart with impressive numbers.
Looking ahead, however, I wonder: Where’s the story? Where will future growth come from once the existing universities have been optimized?
••
imagem de perfil
@GHF I could imagine that the company will continue to expand thanks to its strong free cash flow
••
imagem de perfil
2Mês
@Tenbagger2024 I just did a little research on my own.
I, too, have come to the conclusion that it’s a strong, high-quality compounder.
However, the company has no plans to expand by opening additional universities (which probably makes perfect sense). Further growth is expected to come primarily from an increase in student enrollment (especially in the online sector, which doesn’t incur additional costs) and regular tuition hikes.
If the company continues its regular share buybacks, a realistic scenario could involve annual share price growth of around 8–10%.

The only risk factor, in my view, appears to be the company’s regional dependence on Mexico and Peru. If an economic crisis were to occur in this region, a massive slump would be expected.

My conclusion is that anyone looking for regional diversification has a high-quality stock to consider here. However, I don’t believe we can expect the same level of price appreciation seen in recent years over the next five years.
•
2
•
Participar na conversa