Hello my dears,
I have been following the $REVG but unfortunately I never managed to get started. Although I have always liked the company.
But in the last few days, no share price has been displayed here. And because I'm currently following a lot of exciting companies, I haven't yet managed to research why this is the case.
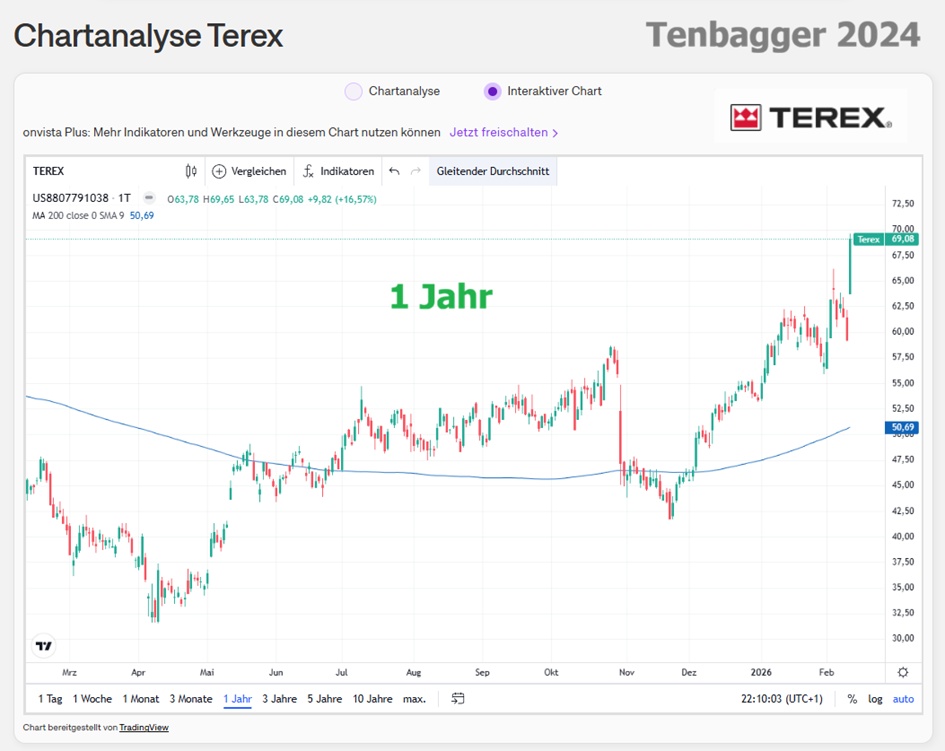
Due to the good performance, driven by good figures, I took a look at Terex yesterday. $TEX (-0,21%) yesterday. And what do I read in the first press release?
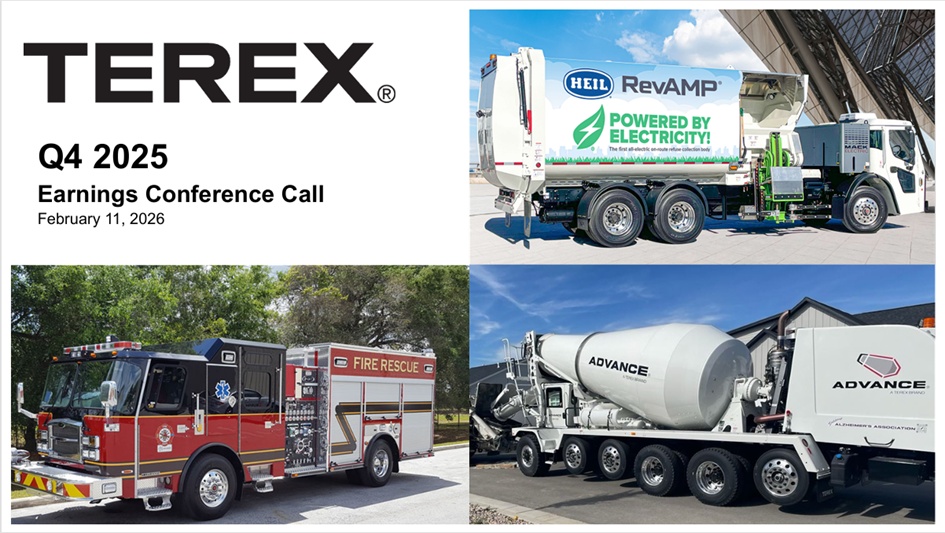
TEREX AND REV GROUP COMPLETE MERGER AND CREATE A LEADING MANUFACTURER OF SPECIALIZED EQUIPMENT
This of course makes Terex interesting for me. And I realized just how interesting Terex is when I looked at the portfolio.
Apart from the growing sector (see Caterpillar), I see a lot more potential here, driven by the high demand for commodities.
Ladies and gentlemen, do you agree with my theory? And does this also make Terex an investment with potential for you?
About Terex
Terex Corporation is a global leader in specialized equipment solutions, serving key sectors such as emergency services, waste and recycling, utilities and construction. Our diversified portfolio positions us in resilient, high-demand markets with strong long-term growth potential.
They design and manufacture advanced specialty vehicles - including fire trucks, ambulances and recreational vehicles - alongside waste collection vehicles, materials processing equipment, elevated mobile railroads and equipment for the power supply industry. Through its global dealer, parts and service network and true value-added digital solutions, the company provides world-class lifecycle support and helps customers maximize return on investment.
With a strong manufacturing presence in the United States and operations in Europe, India and Asia-Pacific, Terex combines global reach with local expertise to unlock opportunities worldwide. Their strategy is clear: exceed customer expectations, invest in innovation, leverage Terex's diversified portfolio and deliver consistent, profitable growth for their shareholders
The key benefits of the merger with REV Group - and why it's exciting for investors
1. a significantly broader, more robust business model
Terex describes itself as a "global leader in specialized equipment solutions" serving "emergency services, waste and recycling, utilities and construction" . Through the merger with REV Group, this portfolio will be massively expandedespecially in:
- Fire trucks
- municipal vehicles
- Special vehicles for authorities
- Rescue and emergency vehicles
Advantage: More end markets = fewer cycle risks = more stable sales.
2. larger global scale and stronger market position
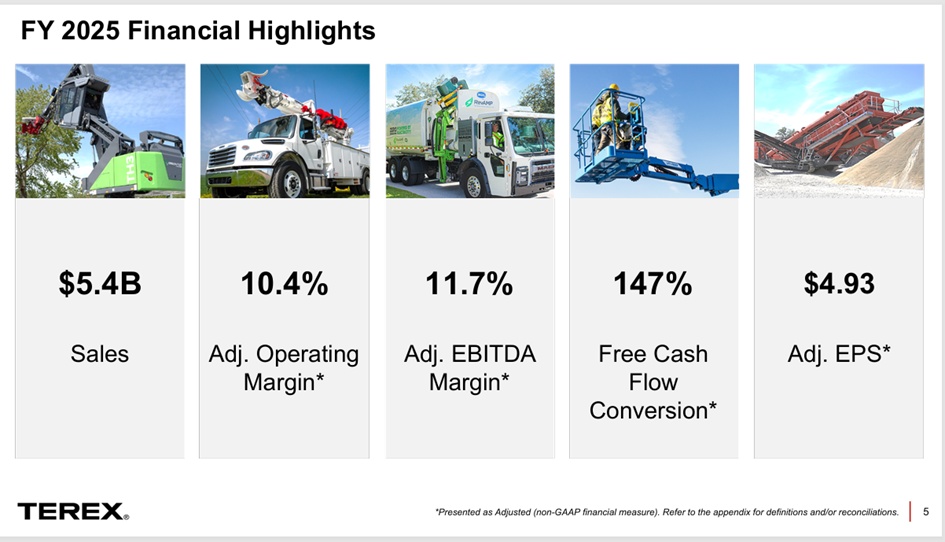
Terex emphasizes its "global scale" and shows even before the merger USD 5.1 billion sales and strong returns on investment (ROIC 19.4 %) . With REV Group, the platform continues to grow and becomes one of the largest specialty vehicle manufacturer in North America.
Advantage: Economies of scale, better purchasing conditions, greater pricing power.
3. synergies - operational and financial levers
The merger was announced in the official presentation (October 30, 2025) . Typical synergies in such deals:
- joint procurement
- production optimization
- shared distribution structures
- more efficient administration
Advantage: Higher margins and increasing cash flows from 2026/27.
4. access to attractive, resilient end markets
Terex itself emphasizes that it operates in "attractive and resilient end markets with strong long-term growth potential". REV Group is active in the same stable segments.
Advantage: More sales security, especially in recession-prone phases.
5. strong track record of return on capital and shareholder returns
Terex has shown since 2015:
- 5× EPS increase
- 3× ROIC increase
- USD 2 billion return of capital to shareholders
- 39 % share reduction + dividends
Advantage: A management team with a proven track record of value creation - and even more leverage through the merger.
🚀 What does this mean for investors?
1. higher growth potential
The combined company covers more markets and can grow faster - both organically and through cross-selling.
2. increased margins through synergies
The integration should bring noticeable EBITDA leverage from 2026/27.
3. more stable cash flows
More end markets + more state/municipal customers = less volatility.
4. re-rating potential
If Terex can increase USD in millions
estimates
the market could
- pay higher multiples
- Revalue the stock
- See the merger as a strategic turning point
5. stronger competitive advantage
The new size makes Terex one of the dominant player in the specialty vehicle segment - without a monopoly, but with clear strength.
🚀 What potential does the high demand for raw materials create for Terex?
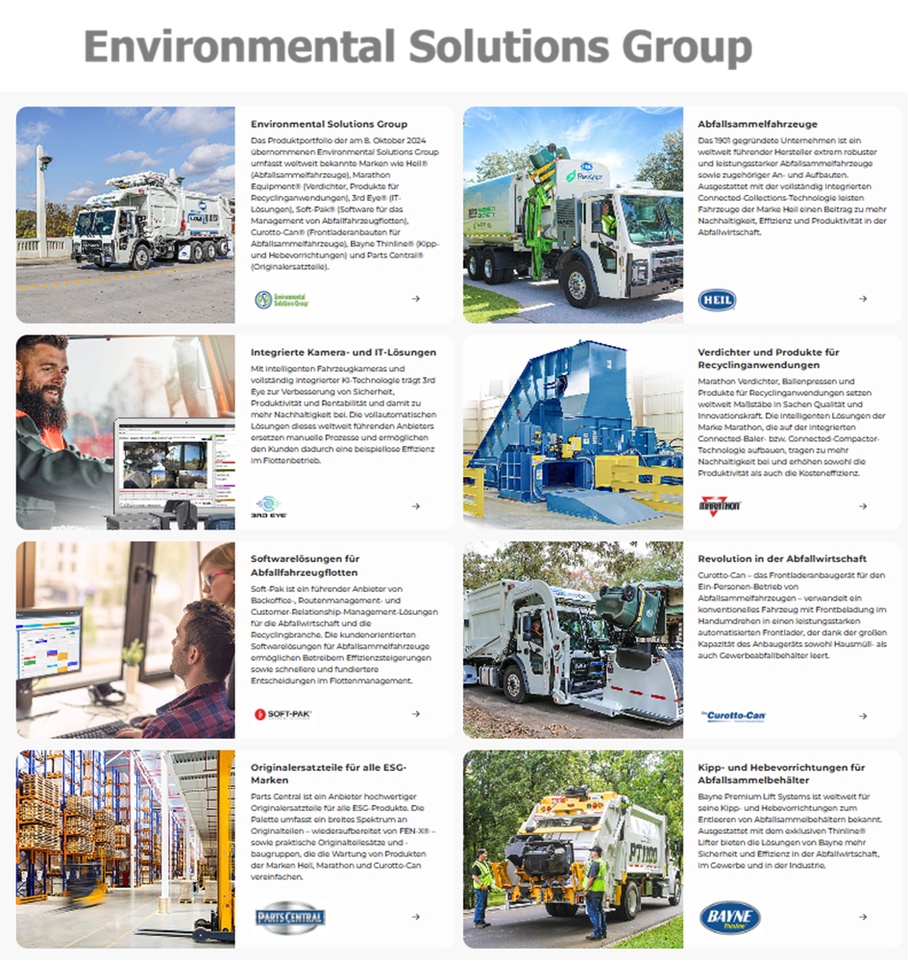
The rising demand for raw materials (copper, lithium, nickel, iron ore, rare earths) is leading to more mining activity globally more mining activity, more infrastructure projects and more material processing. This is exactly where Terex is strategically positioned.
⭐ 1. more mining = more demand for material processing technology
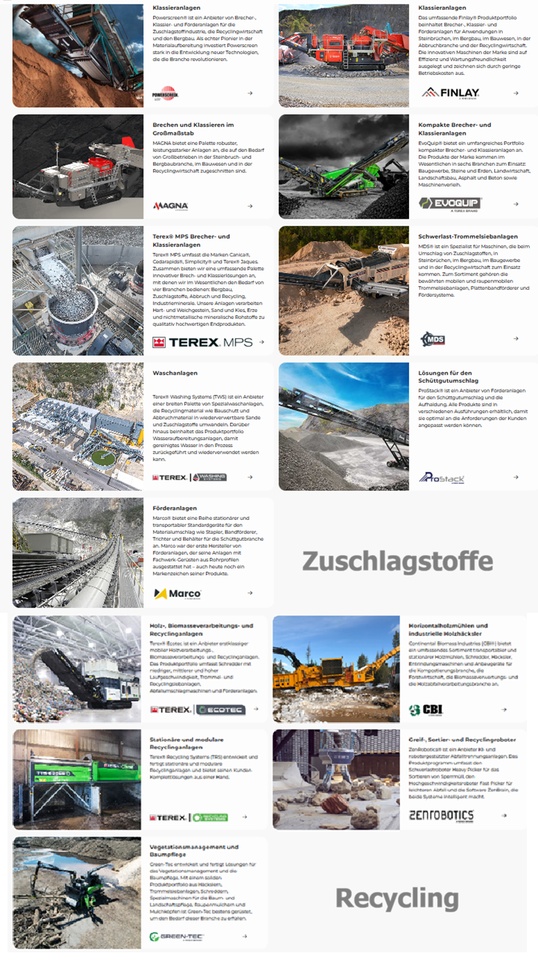
Terex is strong in materials processing (Powerscreen, Finlay, EvoQuip, CBI, Ecotec). These brands deliver:
- Crushers
- screening plants
- conveying technology
- Recycling and crushing plants
When raw materials companies expand, they need more capacityand this is exactly what drives the demand for Terex machines.
Potential: → Higher sales in one of the highest-margin segments.
⭐ 2nd raw materials boom leads to more infrastructure projects
Terex itself emphasizes that it operates in "attractive and resilient end markets", including Construction and utilities .
More raw material extraction means
- new roads
- new ports
- new energy and water infrastructure
- new processing plants
All of this is needed:
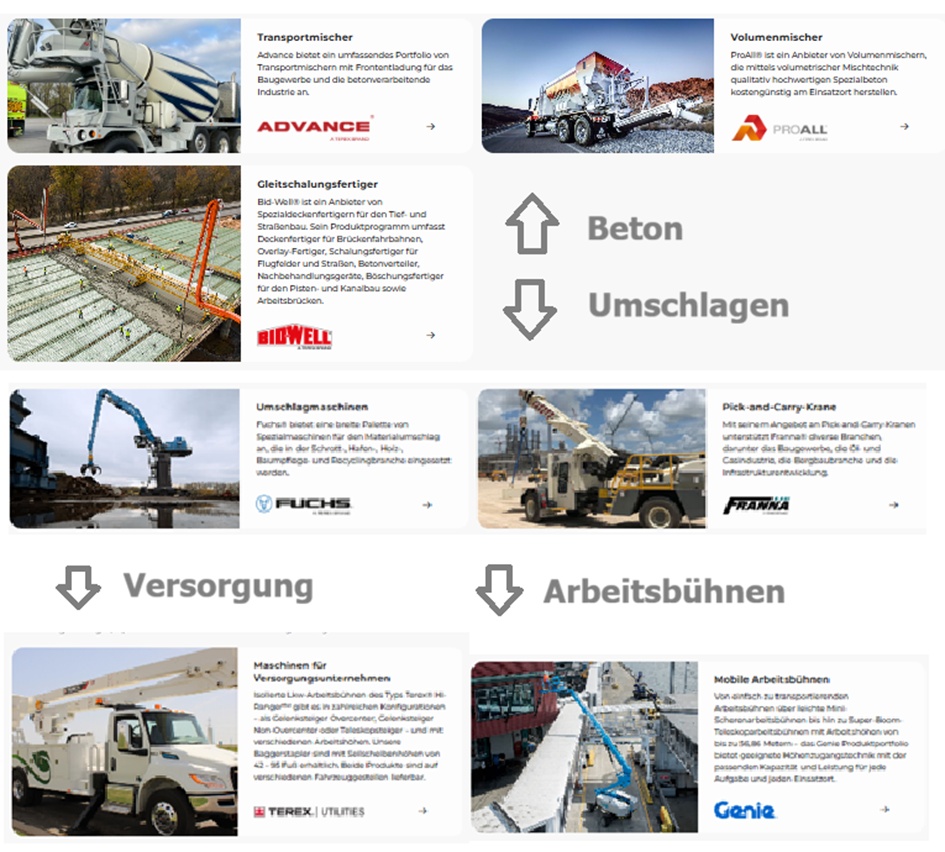
- cranes
- aerial work platforms
- special vehicles
- Material handling technology
Potential: → Broad increase in demand across several Terex segments.
3. recycling & circular economy also benefit
Terex is strong in the recycling and waste technology segment (Ecotec, Fuchs). As raw materials become scarce and expensive, the demand for
- metal recycling
- Construction waste processing
- Reprocessing of battery materials
Potential: → Structural growth, independent of the economic cycle.
⭐ 4. higher raw material prices = more investment by mine operators
When commodity prices rise, mines increase
- CAPEX
- Replacement investments
- Expansion projects
Terex benefits disproportionately because its machines have have relatively low investment costs but high productivity leverage offer.
Potential: → Disproportionate profit increases with rising raw material prices.
Global scale + strong return on capital = leverage for investors
Terex already has impressive key figures before the merger:
- USD 5.1 billion sales
- 19.4 % ROIC
- 5× EPS increase since 2015
- USD 2 billion return of capital to shareholders
If demand for raw materials continues to rise, these levers will increase:
- higher capacity utilization
- better margins
- more cash flow
- more share buybacks / dividends
Potential: → Re-rating of the share + rising shareholder returns.
🎯 Summary for investors
The high demand for raw materials is a massive tailwind for Terex massive tailwindbecause:
- the materials processing segment is booming
- Infrastructure investments are increasing
- Recycling is gaining in importance
- mine operators are investing more
- Terex already has a strong global platform
The result: → More growth, higher margins, more stable cash flows and long-term upside for the share.
As the backbone of infrastructure development, the aggregates industry needs efficient, reliable machines. This division includes Powerscreen, Finlay, EvoQuip, MDS, Terex MPS, ProStack, Marco and Terex Washing Systems. Under these brands, Terex MP offers mobile, modular, transportable and stationary solutions for crushing, classifying, washing, recycling and conveying applications used in the raw materials, aggregates and construction industries worldwide.
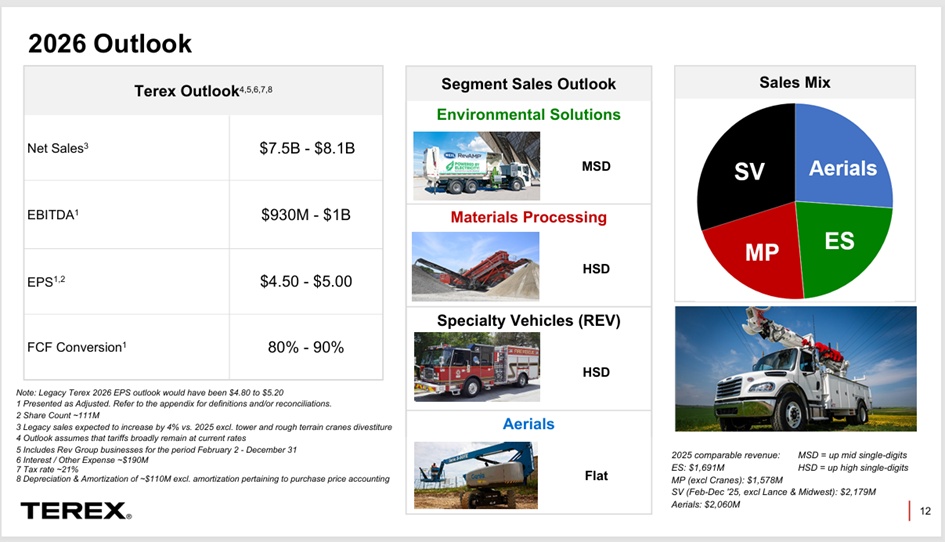
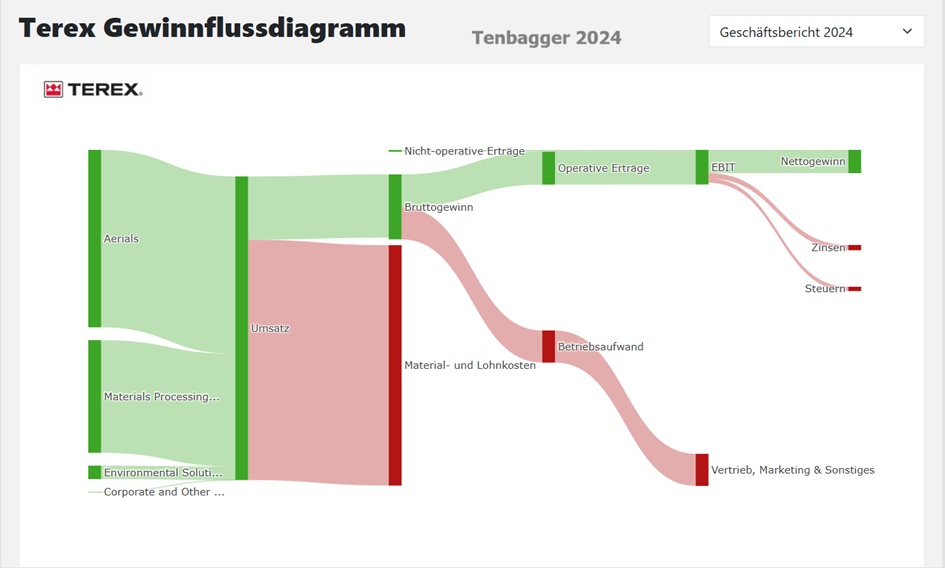
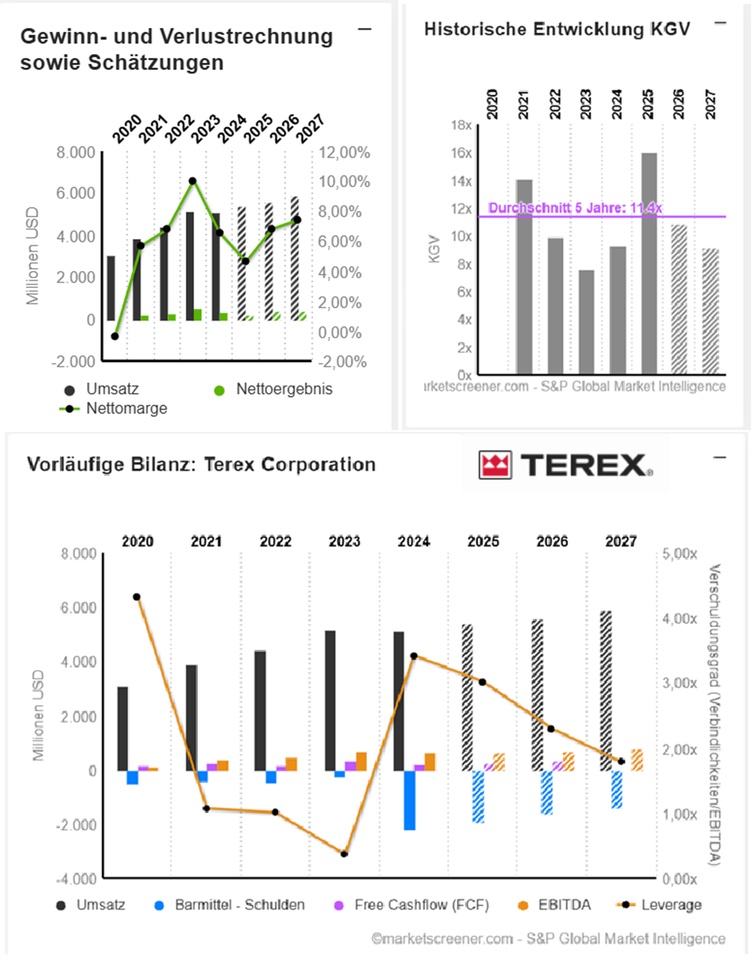
Ladies and gentlemen, the merger with the REV Group will of course make the figures look even better. Nevertheless, here are the old estimates from Terex.
USD in millions
Estimates
Year Turnover Change
2024 5.127 -0,48 %
2025 5.421 5,73 %
2026 5.567 2,68 %
2027 5.890 5,81 %
Year Turnover Change
2024 526 -17,36 %
2025 566 7,6 %
2026 617,9 9,17 %
2027 647,1 4,73 %
Year Net result Change
2024 335 -35,33 %
2025 221 -34,03 %
2026 379,1 71,54 %
2027 436,3 15,09 %
Year Net debt CAPEX
2024 2.196 137
2025 1.924 113,9
2026 1.607 118,6
2027 1.394 120,8
Year Free cash flow Change
2024 189 -43,09 %
2025 272,3 44,07 %
2026 351,4 29,05 %
Year EBIT margin ROE
2024 10,26 % 23,57 %
2025 10,45 % 16,73 %
2026 11,1 % 16,86 %
2027 10,99 % 17,51 %
Year Earnings per share Change
2024 4,96 -34,56 %
2025 3,687 -25,66 %
2026 5,542 50,31 %
2027 6,562 18,4 %
Year Dividend Yield
2024 0,68 1,47 %
2025 0,66 1,11 %
2026 0,6746 1,14 %
2027 0,6625 1,12 %
Year P/E ratio PEG
2024 9.32x -0.3x
2025 16x -0.5x
2026 10.9x 0.2x
2027 9.1x 0.4x
Market value 6,724
Number of shares (in thousands) 113,463
Date of publication 11.02.26