

Hello, everyone,
My last post was about nanotechnology. Since I’ve been getting questions about the medical technology sector lately,
I’d like to tie these two topics together, which brings us to the field of diagnostics.
Some of you have probably been keeping an eye on the major players in the medical tech sector for quite some time now. And you’re likely disappointed by their lackluster performance.
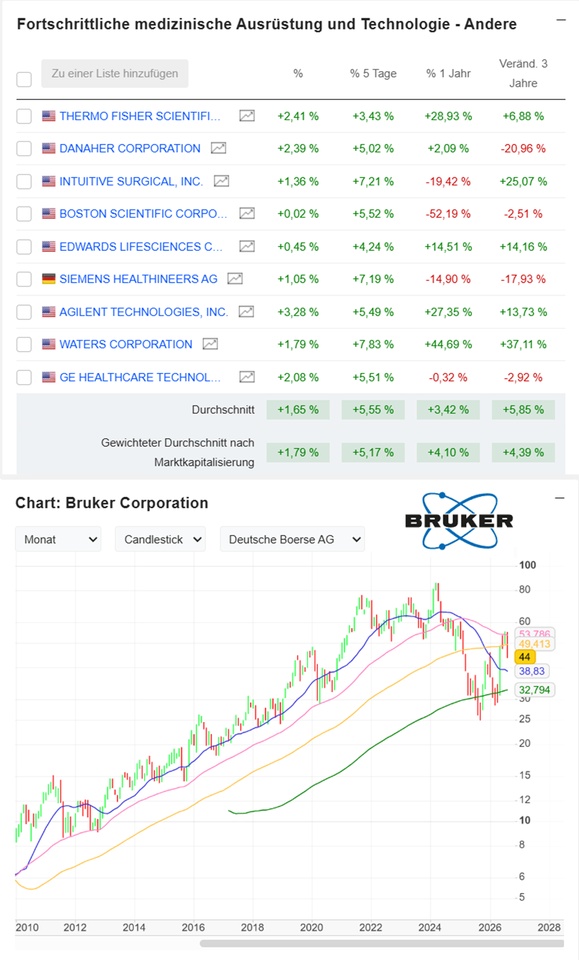
I’ve included the list below for your reference.
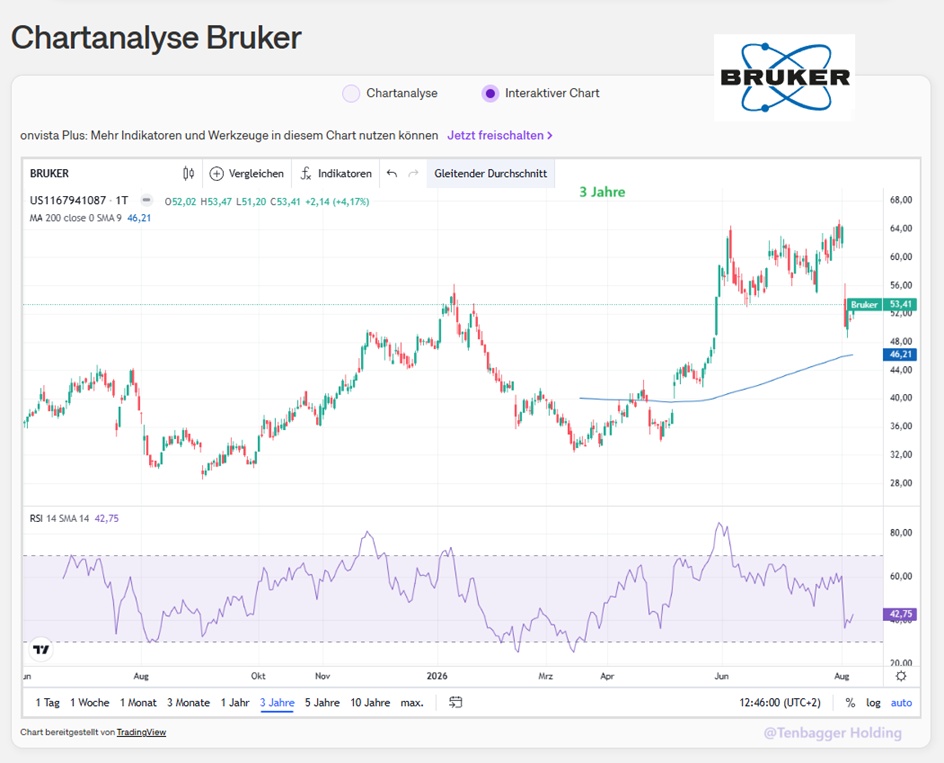
If we look at the chart for today’s company, we see that it stands out with an annual performance of +71.41%.
Even though there was a significant correction following the latest quarterly results, the attractive RSI could make this a good opportunity right now.
Because in the long term, we might have a medical tech company here that even has great potential in the semiconductor industry.
My dear friends, and my dear prompts, what’s your take on this company?
(@Raketentoni , @Aktienhauptmeister )
The Bruker Corporation owes its existence to Professor Günther Laukien, who recognized the need for pulse spectrometers as early as the 1950s. In 1960, Professor Laukien set out to meet this need by founding Bruker Physik-AG in Karlsruhe. Since then, Bruker has been developing groundbreaking analytical solutions
The Bruker Corporation is a developer, manufacturer, and distributor of high-performance scientific instruments as well as analytical and diagnostic solutions. The company’s business units include Bruker Scientific Instruments (BSI), BioSpin, BSI CALID, BSI NANO, and Bruker Energy & Supercon Technologies (BEST). The BSI business unit develops, manufactures, and markets life science instruments based on magnetic resonance technology and offers automated solutions for laboratory research and development in chemical research. The BSI CALID segment develops, manufactures, and markets solutions for mass spectrometry, applied spectrometry, and ion mobility spectrometry in the life sciences, as well as analytical and process analysis instruments and solutions based on infrared and Raman molecular spectroscopy technologies. BSI NANO develops, manufactures, and markets advanced X-ray equipment, scanning force microscopy instruments, optical fluorescence microscopes, analytical tools for electron microscopes, and other products.
Number of employees: 11,085
Stifel Raises Bruker’s Price Target to $50 Due to Strong Performance
Published on August 5, 2026, at 5:44 a.m.
🧩 Article summary
Stifel raises its price target for Bruker from $45 to $50, despite a recent decline in the stock price. Reason: strong demand from the semiconductor and AI sectors, where orders have risen by over 50% . However, long lead times are delaying revenue recognition.
📉 Why did the stock recently fall?
- Bruker missed its organic growth.
- As a result, the stock lost 18.5% within a week.
- Revenue came in at $838.5 million , fell short of expectations ($853.4 million).
- Earnings, on the other hand, were well above expectations: $0.49 per share vs. $0.3832.
📊 Outlook & Valuation
- Full-year outlook remains unchanged.
- Bruker expects low single-digit growth, and in 2027 mid-single-digit growth rates.
- Weakness in the academic market is weighing on the company.
- Stifel maintains a multiple in the low 20s to be appropriate.
- InvestingPro continues to view the stock continues to view the stock, with an expected earnings per share of $2.13 per share for 2026
- 🎯 Key Takeaway
- Despite short-term weakness and a revenue miss, demand for semiconductors and AI a strong driver, leading Stifel to raise its price target and a positive assessment .
Presentation Title in maximum two lines
Bruker Exceeds Q2 Earnings Forecast, but Stock Plummets Due to Missed Revenue Targets
August 4, 2026
Summary of the report
(Source: )
1. Q2 2026 Earnings
- Earnings well above expectations: $0.49 non-GAAP EPS vs. $0.3832 expected.
- Revenue fell short: $838.5 million vs. $853.4 million expected.
- Weak organic growth: +2.8% (excluding currency effects: +3.4%).
- Margins improved significantly:
- Gross margin up 350 bps to 52.1%.
- Operating margin up 510 bps to 14.1%.
2. Market reaction
- Stock price falls −16.8% to $53.50.
- Reason: Investors are focusing more on missed revenue targets and cautious outlook rather than the strong margins.
3. Business Performance
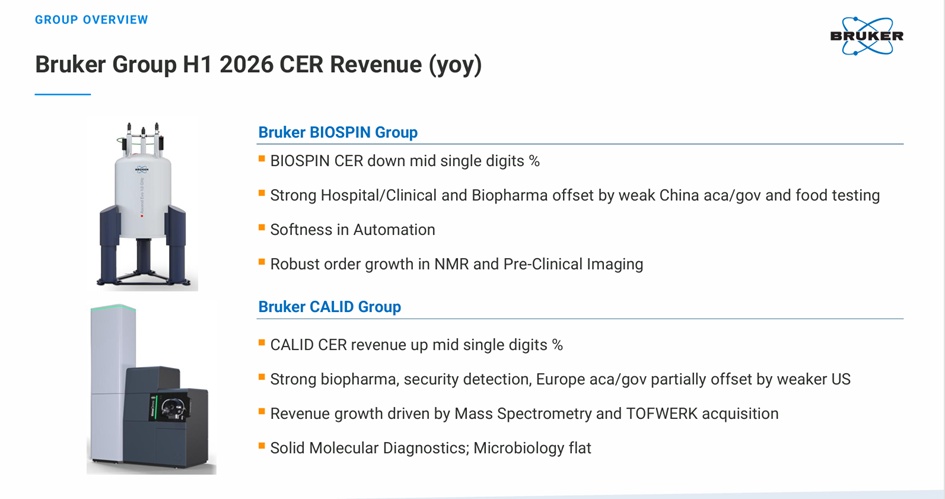
- Strong Sectors: Biopharma, semiconductor measurement technology, energy research.
- Weak areas: U.S. academic and government institutions, food analytics, industrial markets.
- Deep-tech segments: Very strong order growth, but long delivery cycles → Revenue is spread over several quarters.
4. Financial Key Figures
- Revenue +5.2% YoY.
- Operating cash flow: +$50 million.
- Free cash flow: $43 million.
- Net debt: 2.8×.
- Market capitalization: $8.15 billion.
- Beta: 1.29 (higher volatility).
5. Outlook
- Full Year 2026:
- EPS of $2.10–2.15 confirmed.
- Organic growth: 1–2%.
- Revenue: $3.54–3.57 billion.
- Currency tailwind reduced (0.5%).
- Q3:
- Organic revenue flat to slightly up.
- Margins down sequentially.
- $20 million in semiconductor revenue will be deferred to Q4.
- Q4:
- Significantly better margins, revenue, and EPS.
- Revenue of $1.02–1.04 billion expected.
- 50–66% of revenue already covered by the backlog.
6. Management Statements
- CEO: pleased with the return to organic growth; strong demand in NMR, X-ray, and mass spectrometry.
- CFO: Revenue at the lower end of the range, margins significantly above plan; customs refunds contributed +200 bps.
7. Risks
- Weak U.S. research budgets.
- Long lead times in the semiconductor business → quarterly volatility.
- Exchange rate pressure.
- Front-loading effects related to tariffs.
- Mixed performance in end markets.
8. 2027 Outlook (Initial Indications)
- Organic growth is expected to accelerate.
- Margins +100 bps or more.
- Double-digit EPS growth.
- Long-term goal: Return to an ~20% EBIT margin.
Bruker Acquires DISQVER Clinical Metagenomics Platform
Expands its next-generation sequencing capabilities for infection detection.
July 15, 2026
Bruker erwirbt DISQVER Clinical Metagenomics Platform | Vertragspharma
Guggenheim Reiterates Buy Recommendation for Bruker Stock Due to Demand for Measurement Technology
Published on July 13, 2026, 1:45 p.m.
🔍 Key Takeaway
Guggenheim confirms its “Buy” rating for Bruker and maintains the price target at $70. Main reason: strong growth prospects in the semiconductor metrology business, which, according to expert interviews, is expected to grow by around 30% in the short term.
📈 Reasons for the positive assessment
- Guggenheim surveyed semiconductor experts with over 135 years of combined industry experience (foundries, IDMs, OSATs, and metrology equipment manufacturers).
- Result: Very strong demand for Bruker’s metrology solutions.
- Bruker’s management confirms the growing importance of the semiconductor segment.
- Growth depends on whether Bruker can maintain maintain its order momentum through the end of 2026 .
🧪 Product & Technology Updates
Bruker is showing strong activity in its product portfolio:
- New MALDI Biotyper CA system (FDA-approved features).
- New timsMRMS System for energy research (high-resolution analytics).
- Expansions in the field of microbiology and infectious disease diagnostics.
🎯 Conclusion
The article paints a picture of robust semiconductor growth, strong product innovation, and confirmed analyst confidence. Despite some valuation concerns, analysts view Bruker as a clear beneficiary of demand for measurement technology.
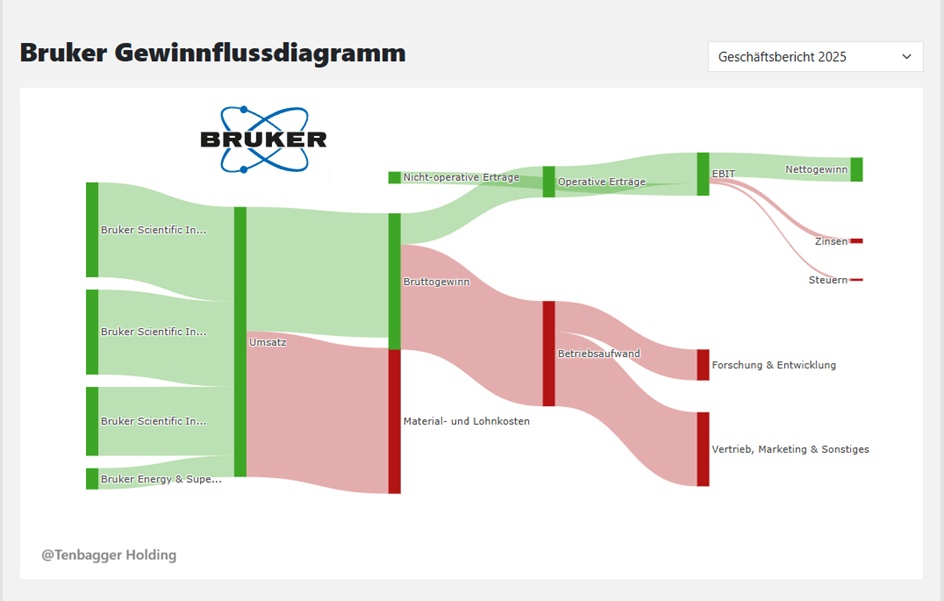
Geographic Revenue Breakdown:
2025 (USD)
Europe Excluding Germany 950 million
United States 891 million
Asia Pacific Excluding China 553 million
China 476 million
Germany 297 million
Other 270 million
Revenue Breakdown by Business Segment:
2025 (USD)
Bruker CALID 1.21 billion
Bruker Nano 1.08 billion
Bruker Bio Spin 879 million
Bruker Energy & Supercon Tech 271 million
Intersegment Revenue -7.7 million
Market Capitalization 8,138
Number of Shares (in thousands) 152,359
Date of Publication 02/12/2026
🎯 Ultra-compact interpretation
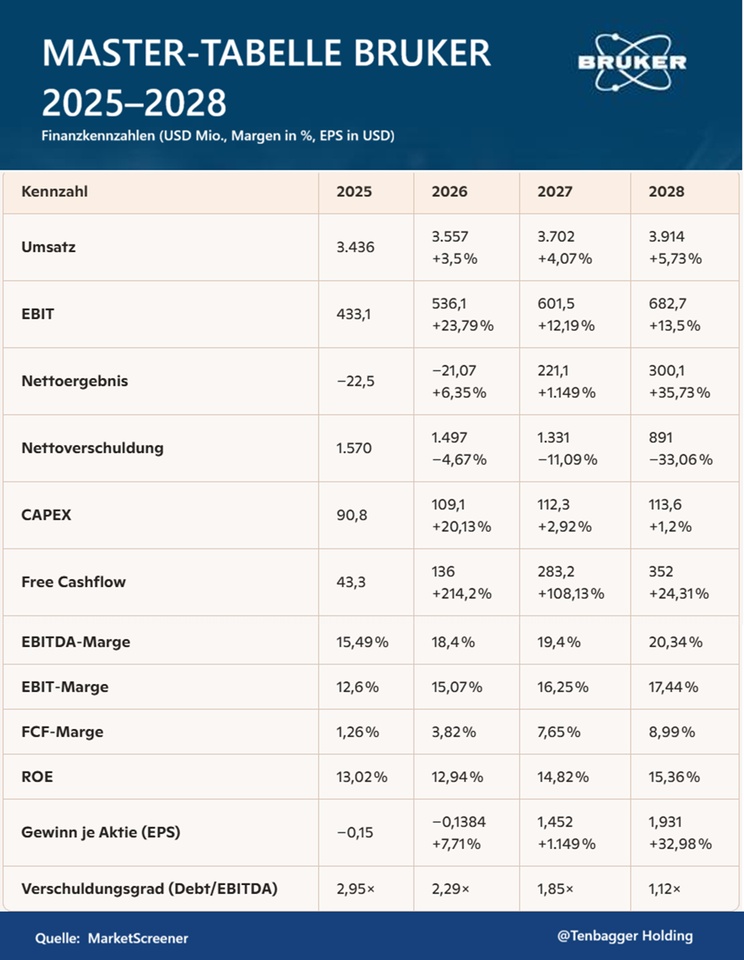
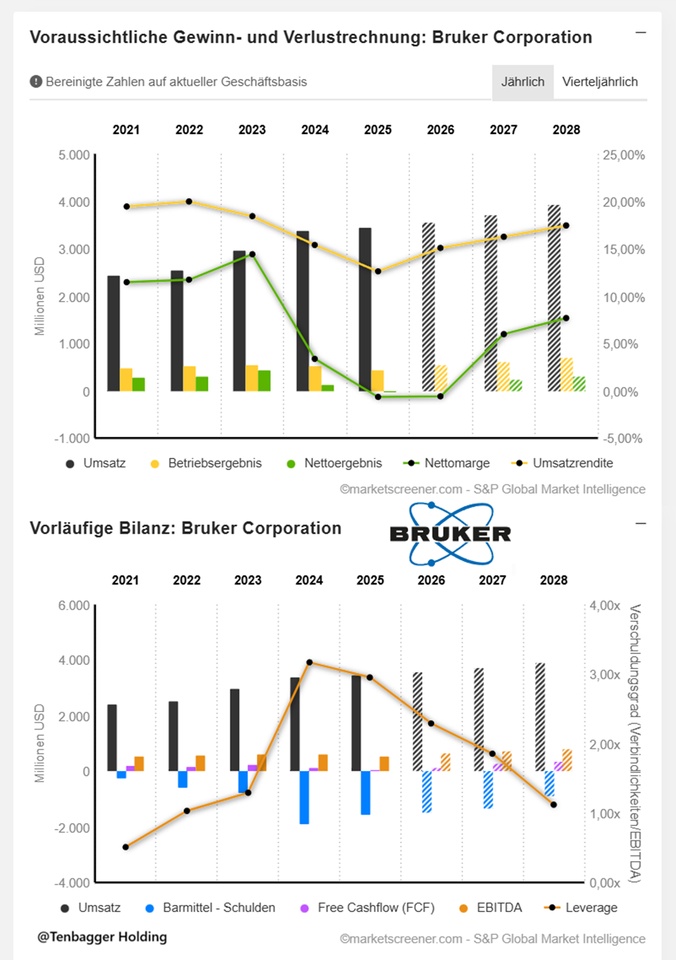
- 2026–2028 = clear recovery: EBIT, FCF, margins, and EPS rise sharply.
- Net debt falls dramatically → By 2028, only $891 million.
- FCF margin jumps from 1.26% → 8.99%.
- EBIT margin is approaching its long-term target range again (~17–20%).
- EPS turnaround very significant starting in 2027.
🎯 Ultra-compact interpretation
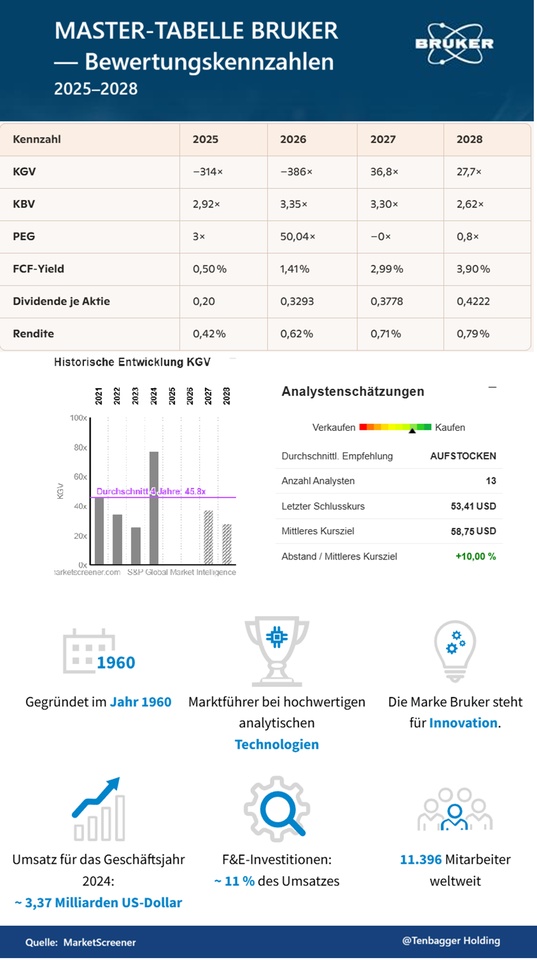
- 2027–2028 = Valuation normalization P/E ratio falls from extreme distortions (negative EPS) back into the 20s–30s range.
- FCF yield rises each year → 0.50% → 3.90%.
- Dividend grows steadily → +30–40% over four years.
- PEG 2028 = 0.8× → significant improvement in the growth ratio.
August 8, 2026, 10:05:00 •
Lang & Schwarz (EUR)
45.87 EUR
+0.06 EUR +0.13%


