

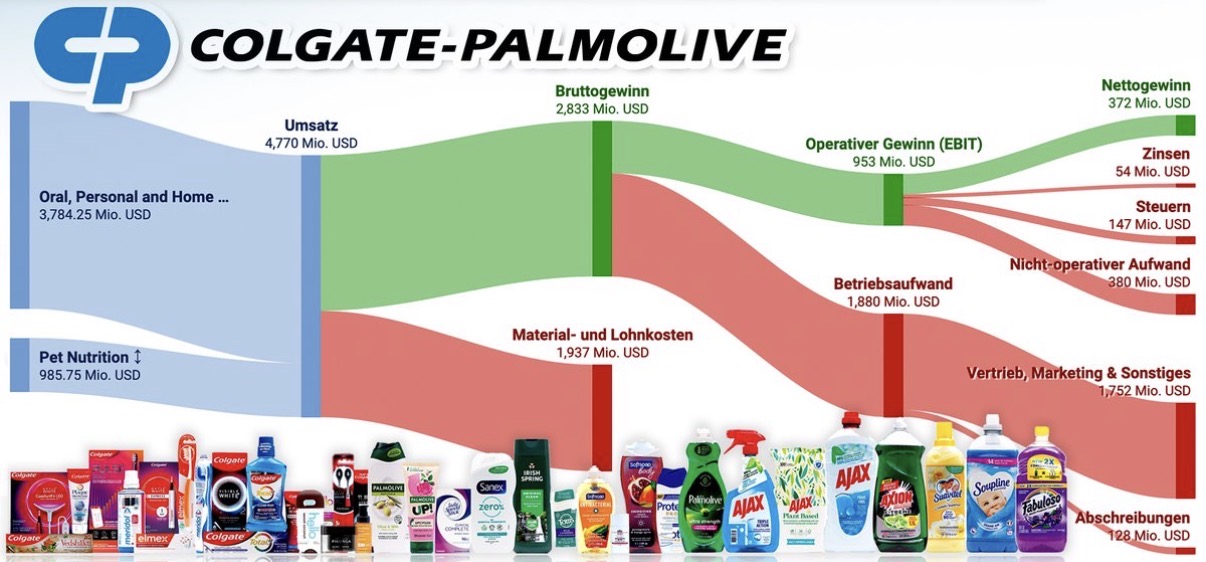
On January 30, 2026, Colgate-Palmolive Company (NYSE: CL) published its results for the fourth quarter and full year 2025 and presented a solid, albeit less dynamic, conclusion to a challenging financial year. The quarterly figures and strategic initiatives paint a mixed picture: on the one hand, strong cash flows and a robust dividend policy, on the other hand, organic growth is slowing in many core segments.
1. current quarterly figures (Q4 & full year 2025)
Turnover & result
- At around USD 5.23 billion, net sales in the fourth quarter exceeded analysts' consensus estimates, reflecting a positive market environment in the area of everyday consumer goods.
- Adjusted earnings per share (adjusted EPS) amounted to USD 0.95, exceeding expectations (forecast around USD 0.91). This demonstrates the company's operational strength despite continued volatile conditions.
- For the year as a whole, net sales increased organically by 1.4%, while GAAP EPS fell by around 25% due to one-off accounting effects (goodwill/intangible assets).
Cash flow & capital repayment
- Of particular note is a record operating cash flow of around USD 4.198 billion, a strong indicator of cash generation power.
- The company has returned USD 2.9 billion to shareholders, including through dividends and share buybacks. Colgate has paid dividends continuously since 1895, which is an important criterion for defensive investors.
2. detailed analysis of the last quarters
A review of the previous quarterly reports shows that Colgate-Palmolive is continuously adapting to a more difficult market environment:
- Q3 2025: organic sales growth remained at 0.4% and gross margin suffered from higher raw material and packaging costs.
- Q2 2025: Results also showed slight outperformance in sales and EPS, although gross margin was impacted by inflationary costs and tariffs.
Overall, it is clear that Colgate continues to deliver stable results, but growth momentum is moderate compared to previous years. This is reflected in particular in organic growth rates, which tend to be in the low single-digit percentage range.
3. market reaction & analyst opinions
Following the release of the figures, share prices reacted slightly positively, pointing to the solid results and improved outlook for 2026. According to the Reuters report, Colgate expects net sales growth of between 2% and 6% in 2026, supported by stable demand for everyday hygiene and personal care products, particularly in Latin America and Europe.
Analyst sentiment is mixed:
- Wells Fargo recently upgraded the rating to "Equal-Weight" and sees moderate upside potential based on current valuations and expected results.
- RBC Capital assumes an Outperform rating, but continues to see challenges in global growth.
- JPMorgan had previously lowered its price target as some product categories are performing weaker than expected.
These diverging assessments show that the market sees Colgate-Palmolive as a defensive consumer goods stock - with an attractive dividend yield, but at the same time limited short-term growth potential.
4. future prospects and strategic initiatives
Colgate is actively investing in its future potential in order to achieve higher organic growth again in the long term:
Strategic direction through 2030
- The company has launched a "Strategic Growth and Productivity Program" (SGPP), which aims to integrate innovation, digital demand generation and artificial intelligence more closely.
Product innovation & portfolio expansion
- Innovations in core categories such as dental care and home/personal care should further consolidate brand strength and create new growth drivers.
- Hill's Pet Nutrition division is showing improvement again after Colgate divested less strategic private label businesses.
Macroeconomic challenges
- Like many consumer goods manufacturers, Colgate is feeling the pressure of commodity price inflation, exchange rate volatility and subdued consumer spending, particularly in developed markets. This can put pressure on margins and dampen growth.
5. conclusion for investors
Colgate-Palmolive remains a classic defensive consumer goods stock with stable cash flows, a solid dividend history and attractive long-term yield aspects. The latest quarterly figures show that the company is structurally well positioned to survive even in a difficult global environment. At the same time, growth is rather moderate and market risks - such as weak category expansion or margin pressure - may limit short-term performance.
For investors looking for stable earnings and dividend continuity, Colgate-Palmolive therefore remains a position worth considering. Those looking for strong sales and earnings growth, on the other hand, should keep an eye on the share in the long term and pay attention to the implementation of the 2030 strategy.