As announced in my previous post, here is something special and niche from the biotech sector.
It's about $FBIO . Who please (?!), you're probably wondering.
Let me give you a brief overview, especially with regard to what could provide a massive push in the short term.
Let me say in advance that this is absolute high-risk, high-reward gambling, not a buy recommendation and, as always, DYOR applies.
Now to the facts:
$FBIO is active in the development, approval and commercialization of innovative therapies in dermatology, oncology & rare diseases. As is not uncommon in the biotech sector, the company operates primarily through subsidiaries.
Currently, only dermatological products are marketed.
The game changer for $FBIO could be the preparation CUTX-101 as the first therapy against the rare Menkes' disease (I'll spare you the details of the disease, that's more for doctors, pharmacologists etc., if you're interested, you can of course research it for yourself😉). A corresponding application for approval has been pending with the FDA for some time. License fees and milestone payments of up to USD 129 million are linked to this active ingredient. To put this into perspective: the current market cap of $FBIO is approx. 135 million dollars!!!
Now to the really interesting part:
As part of the approval application, the responsible subsidiary received a Complete Response Letter (rejection) from the FDA in September 2025.
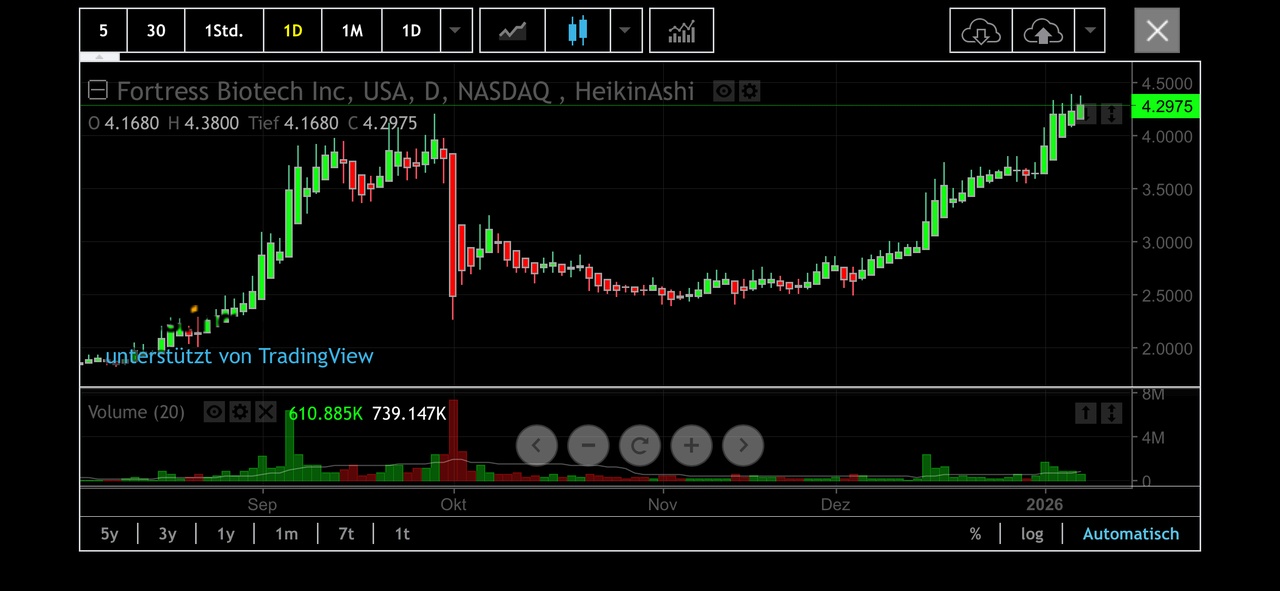
This was based solely on manufacturing problems - not on the efficacy or safety of the drug. Market approval is therefore still quite realistic. The market reaction to the rejection: approx. 30% share price loss on 30.09.2025.
It was pretty much at this point that I entered the market with a small position.
The sell-off seemed absolutely exaggerated to me and, given the share price performance over the last few months, the market also assessed it that way in retrospect.
Why should $FBIO be interesting right now?
Well, the responsible subsidiary resubmitted the application to the FDA in mid-December 2025, and the FDA subsequently set the decision date for January 14, 2026, i.e. next week.
Should approval be granted $FBIO considerable short-term upside potential (my estimate here is >100% from the current level, if you look at milestone payments, license fees etc. and the current market cap in relation).
The share is currently approx. 73% up for me, I will definitely stay on board until the decision is made, but will hedge profits in advance with a stop loss if necessary.
At the present time $FBIO in my opinion only something for very risk-averse investors who are interested in event-driven investing.💥
For the number crunchers among you, here is a brief summary of the key financials (which didn't really play a role for me in this trade from the outset😉):
- Cash balance: USD 86.22m (Q3 2025) - solid liquidity base for short-term capital requirements. If approval fails, further dilution through capital measures is very likely.
- Debt: Significantly reduced, debt/equity from 334.1% (2024) to 122.3% (Q3 2025).
- Earnings situation: Losses, negative EBITDA, but strong EPS trend (growth of 94.1% LTM).
Maybe something for the hardcore traders @Multibagger and @Klein-Anleger 😎