A cooperation with Nvidia and orders worth billions from several hyperscalers. Without Corning's fiber optic technology, it would hardly be possible.
The biggest infrastructure wave of our time
The AI boom initially boosted Nvidia and other chip companies in particular. However, it is now becoming apparent that traditional industrial companies could also be among the big winners.
The AI boom is now changing entire branches of industry. Initially, the focus was Börse almost exclusively on Nvidia. Later, the focus shifted to the potential losers in the software sector.
The potential that lay dormant in the hardware sector was overlooked. This was not understood on the stock market until a few months ago. At that time, Micron's share price was still below USD 70 and today it is significantly higher. During this time, Seagate climbed significantly from below USD 70 - and these are just a few examples.
In the meantime, it is becoming apparent that large parts of the traditional industry are also being turned upside down.
Corning is one of the world's leading manufacturers of specialty glass, fiber optic technology and photonic solutions.
Modern AI data centers not only consume ever more powerful chips, but above all enormous amounts of fiber optic technology. Thousands of graphics processors working in parallel have to exchange data almost instantaneously. This is currently one of the biggest bottlenecks in the AI industry.
NVIDIA boss Jensen Huang has already spoken of the "biggest infrastructure wave of our time".
Why Corning is suddenly at the center of the AI boom
Why Corning is suddenly at the center of the AI boom
Corning and Nvidia have therefore agreed on a long-term technological and commercial cooperation to massively expand the production of optical connectivity solutions in the USA.
Production for optical connectivity in the USA is to be increased tenfold, and the Group is also planning to expand domestic fiber optic production by more than 50%. New production sites are being built in North Carolina and Texas for this purpose. More than 3,000 new jobs are to be created.
KI is increasingly becoming an industry and infrastructure story. In line with this topic:
Amazon greift nach der Kontrolle über Handel, Logistik und KI
For Corning, this development comes at the right time strategically. With the "Springboard" corporate strategy, the management has been pursuing the goal for years of working its way out of low-margin standard business and instead offering highly specialized solutions with a technological edge. This approach is now visibly paying off, particularly in the Optical Communications division.
The next growth phase has begun
This strategy seems to be paying off. After Corning achieved a 15% jump in earnings to USD 1.96 per share in the 2024 financial year, a new record year followed in 2025 with earnings of USD 2.52 per share.
The positive development is likely to continue in the current financial year, not least thanks to the cooperation with Nvidia. The real Hebel is that capacities are being significantly expanded, while at the same time economies of scale are taking effect and good prices can be achieved thanks to strong demand.
In the first quarter, turnover increased by 18% to USD 4.35 billion. At the same time, profitability improved, with earnings increasing by 30% to USD 0.70 per share.
Corning announced that it had signed long-term contracts with two further hyperscalers in the last quarter. According to the company, the scope and duration of the agreements are similar to the recently concluded multi-year contract with Meta with a volume of up to USD 6 billion.
For the second quarter, Corning is forecasting a 14% jump in sales to USD 4.6 billion and a 25% increase in earnings to USD 0.73 - 0.77 per share.
Traders love momentum - investors wait for setbacks
This is in line with current consensus estimates, which predict a 26% jump in earnings to USD 3.18 per share for the current financial year. The only problem with Corning is its high valuation, as the forward P/E is currently 57.
This is at least borderline, without any doubt.
The share is therefore particularly suitable for traders who want to follow a trend. However, the fundamental data and the positive news flow should provide sufficient tailwind to comfort the stock market over the high valuation.
For long-term investors, the share would be particularly interesting after a major setback. In view of the high Volatilität a gradual Einstieg be advisable.
If the company achieves its targets, the path of least resistance over the next few years is likely to be the upside.
Corning is aiming for a turnover (run rate) of USD 20 billion by the end of the year. The aim is to reach USD 40 billion by 2030.
This would roughly correspond to annualized sales growth of around 19 %. If profitability increases at the same time, disproportionately high profit increases would be conceivable.
Growth momentum is currently expected to increase in the coming years. According to consensus estimates, earnings are set to rise by 28% in 2027 and by as much as 31% in 2028
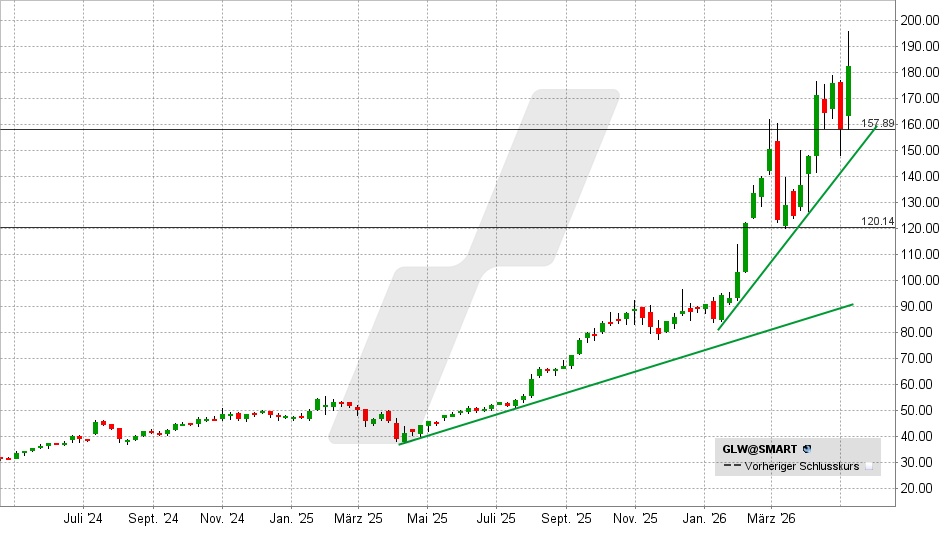
Corning share: Chart from 08.05.2026, price: USD 182.40 - symbol: GLW | source: TWS
Possible starting points on the downside would be the support zone at USD 155 - 160 or the upward trend near USD 145.
The next relevant support below this would be at USD 125 - 130.
However, if there is a procyclical breakout above USD 190, a continuation of the rally towards an all-time high could be possible. Above this, extrapolated price targets of USD 220 and USD 235 are possible.