Good morning my dears,
I need to find the perfect semiconductor for a project. And where would you find it if not in Taiwan? So dear Juan set off on his journey.
I had written him a cheat sheet:
- TSMC has already been presented many times
- Nevertheless, it would be nice if the company were to collaborate with the King of Semiconductors Jensen Huang.
- Another highlight would be if the company also has a position in the fields of optoelectronics and photonics.
My dears, and what can I tell you. Juan has done his homework well.
And so today we can present you with a company that is active in these important technologies through the back door, in the form of subsidiaries and holdings. And on top of that, there's even LIDAR.
And let's compare it with the companies in these sectors, which have been making one high after another for weeks. With a forward P/E ratio of 23 and a PEG of 0.50, our current company is perhaps even a small insider tip.
Of course, I would like to ask you for your opinion, how do you see the company?
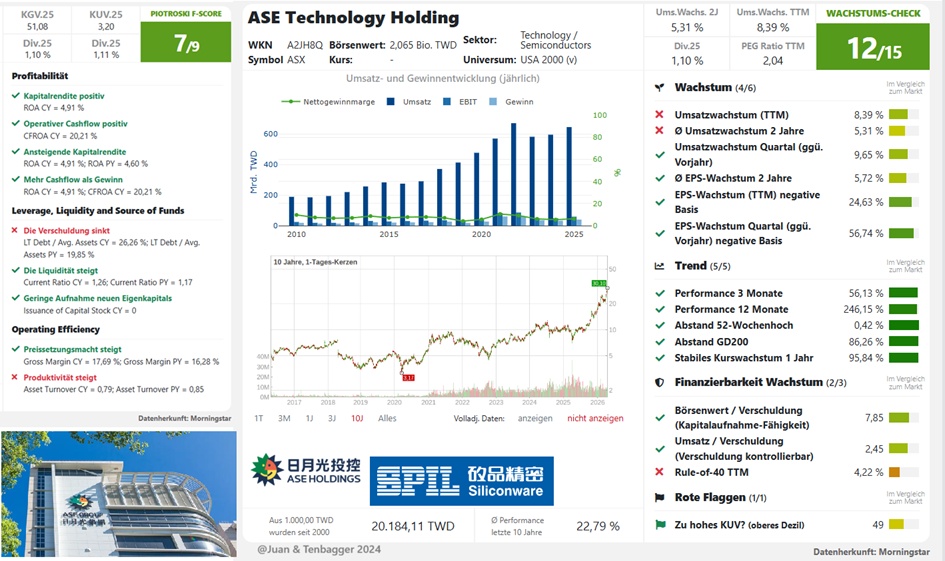
And the company that Juan has found for us is ASE Technology Holding $ASX (+3,42%)
ASE Technology Holding Co Ltd is a Taiwan-based company that mainly invests in packaging services, testing services, electronic product assembly technology and manufacturing services. The investment business includes general investment projects. The packaging and testing business provides integrated circuit (IC) services, including packaging and module design, IC packaging, multi-chip packaging, micro and hybrid modules, memory packaging, front-end testing, wafer probe testing, finished product testing, substrate design and manufacturing. The electronics manufacturing service business mainly provides a series of professional services such as development and design, material procurement, production and manufacturing, logistics, maintenance and other after-sales services for domestic and foreign brand manufacturers in the fields of communications, consumer electronics, computers, memory industry, automotive electronics and other types of electronic products.
Number of employees: 105,955
With over 95,000 employees worldwide, ASE operates manufacturing facilities in several countries, including Taiwan, China, South Korea, Japan, Singapore, Malaysia, Vietnam, Mexico, the United States, Poland, France, the United Kingdom, Germany, Tunisia and the Czech Republic.
ASE Industrial published its figures for the quarter ended December 31, 2025 at the trimonthly financial conference on February 5, 2026.
Earnings per share of USD 0.22 were presented. In the previous year, earnings per share amounted to USD 0.130.
Revenue for the past quarter was reported at USD 5.73 billion - an increase of 14.24% compared to the same quarter of the previous year, when USD 5.02 billion was reported.
EPS for the year as a whole was put at USD 0.600. The previous year's figure was USD 0.470 per share.
Annual sales were put at USD 20.71 billion, compared to USD 18.54 billion in the previous year.
Editorial finanzen.net
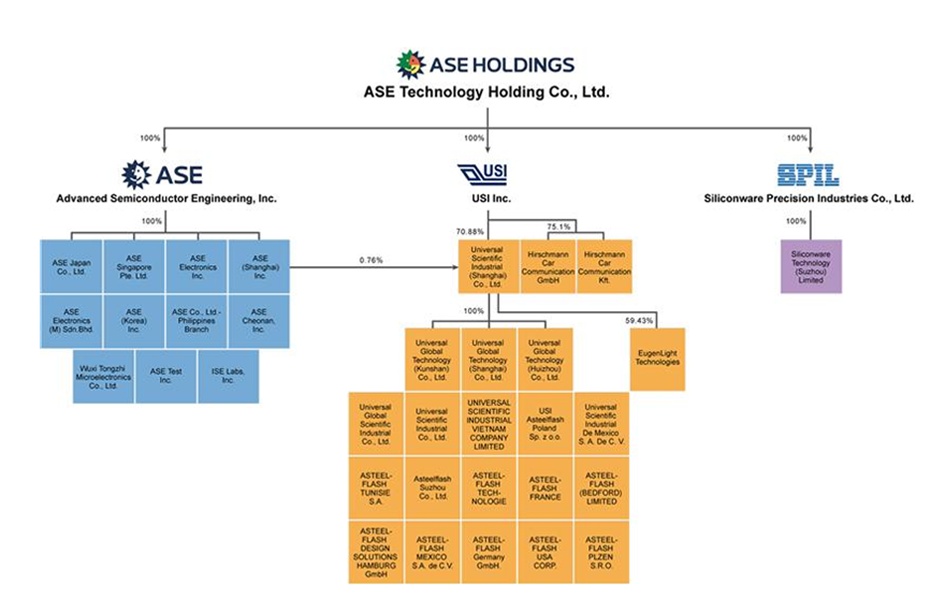
USI subsidiary Universal Optoelectronics acquires controlling stake in Eugenlight Technologies, furthering the integration of the optical interconnect industry
January 16, 2026
USI (SSE: 601231), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), has announced that its subsidiary Universal Optoelectronics has acquired a controlling stake in EugenLight Technologies - a strategic move aimed at consolidating its position in the global optical interconnect ecosystem. By integrating EugenLight's expertise in high-speed optoelectronic components and silicon photonics - breakthrough technologies essential for AI data centers, LiDAR and photonic computing - USI, together with parent company ASE Holdings, aims to enhance its capabilities in rack system integration and advanced packaging.
ASE breaks ground on new high-tech facility in Kaohsiung, investing NT$17.8 billion to meet demand for AI chips
March 11, 2026
ASE starts construction of a new Renwu power plant to build a high-tech test cluster
April 10, 2026
ASE Technology Holdings recognized as one of Taiwan's top 10 sustainable companies for the third consecutive year and received 16 awards, demonstrating leadership in environmental, social and governance (ESG) practices
December 1, 2025
ASE introduces IDE 2.0 - AI-powered platform accelerates housing design accuracy and innovation
November 4, 2025
ASE and Analog Devices announce strategic collaboration
October 21, 2025
ASE und Analog Devices kündigen strategische Zusammenarbeit an | ASE-Holdings
SPIL hosts NVIDIA founder and CEO Jensen Huang at new fab site to accelerate semiconductor assembly and test services
January 16, 2025
Siliconware Precision Industries Co, Ltd ("SPIL"), a subsidiary of ASE Technology Holding Co, Ltd (TWSE: 3711, NYSE: ASX), welcomed Jensen Huang, founder and CEO of NVIDIA, to the opening ceremony of its Tan Ke Plant facility. The Chairman of SPIL, C.W. Tsai, met with NVIDIA Founder and CEO Jensen Huang and highlighted the close cooperation between the two companies as they work together to usher in the new era of AI chip innovation.
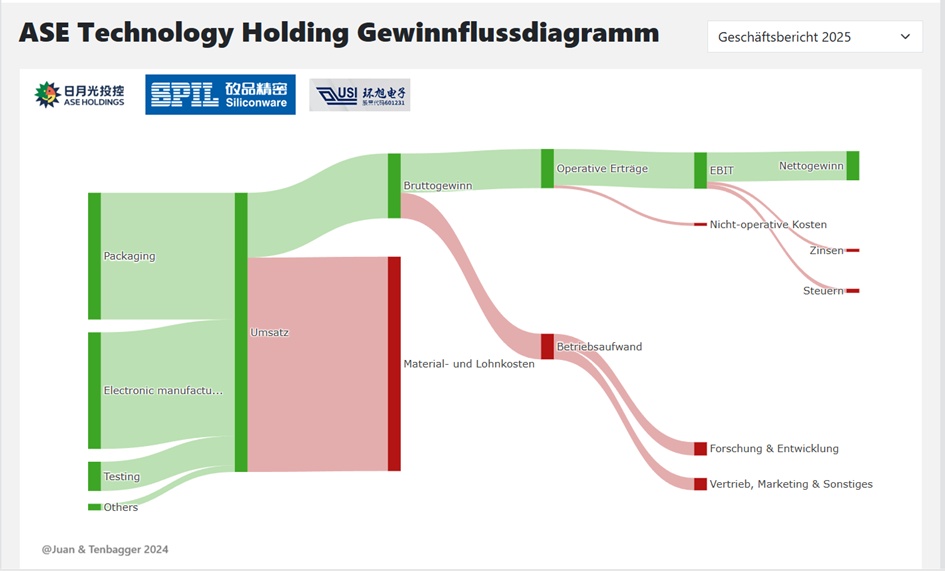
Sales breakdown by business unit:
2025 (TWD)
Packaging 314 billion
Electronic Manufacturing Service (EMS) 289 billion
Testing 72.46 billion
Others 16.38 bn
Adjustments and Eliminations -46.37 billion
Geographical distribution of sales:
2025 (TWD)
U.S. 366 bn
Taiwan 116 billion
Asia 97.82 billion
Europe 64.91 bn
Other 897 million
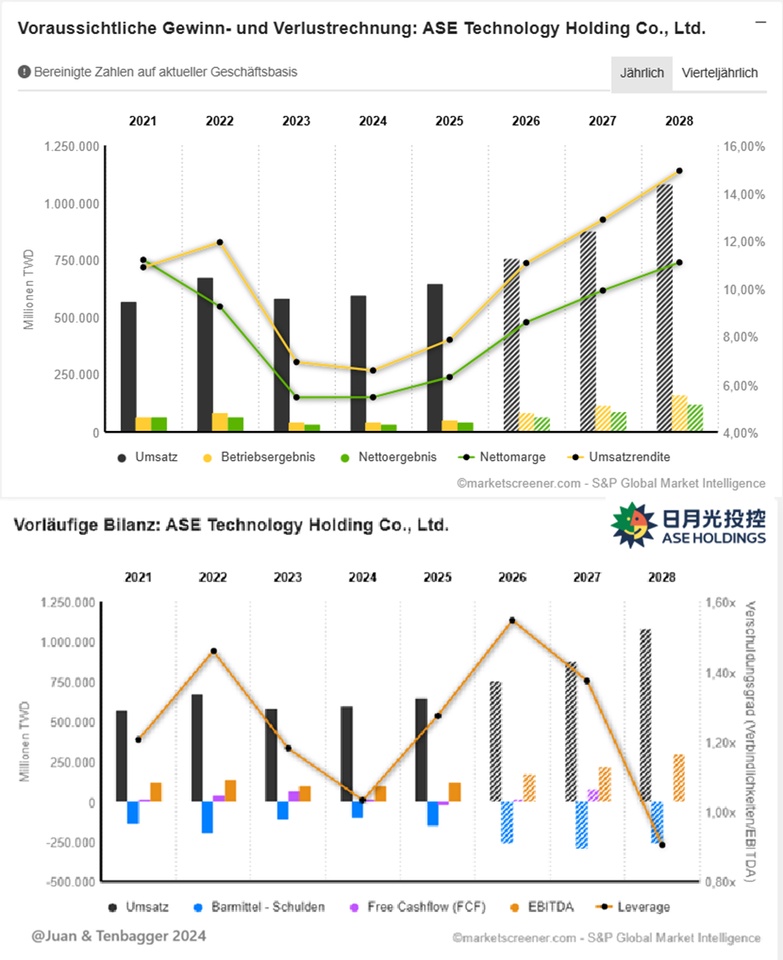
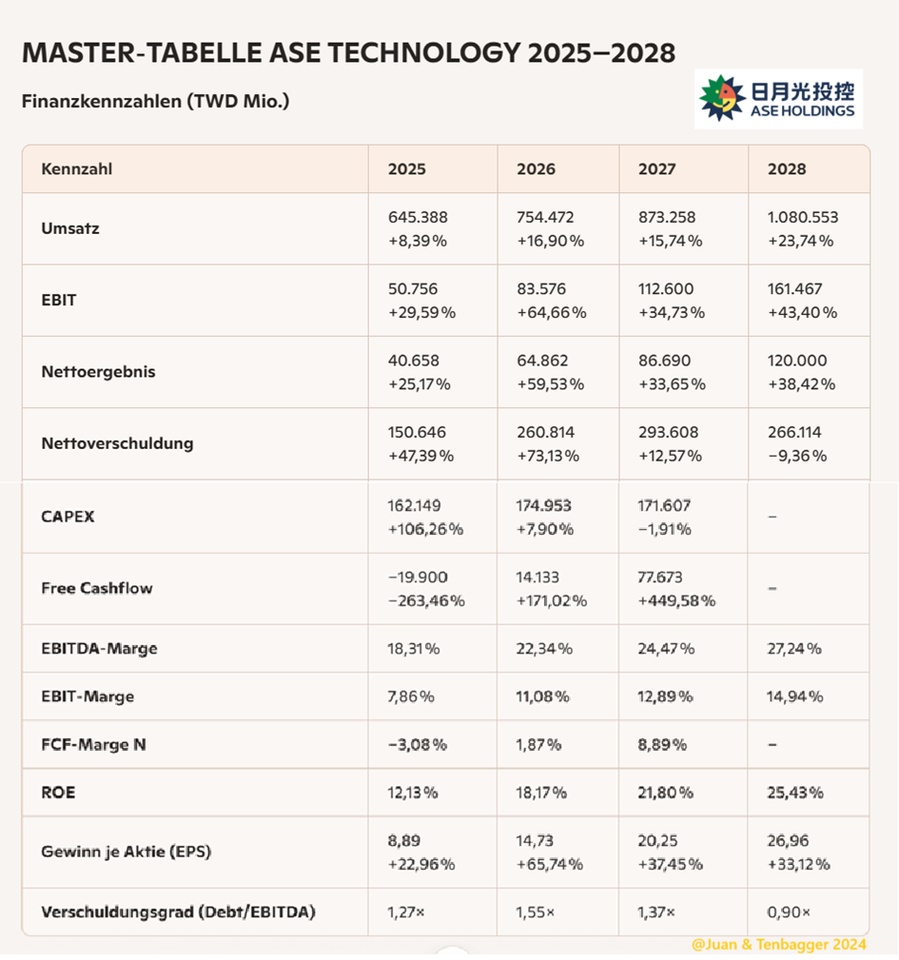
Brief summary of the key financial figures (2025-2028)
ASE shows from 2025 a significant operational recoveryacross all key performance indicators. Revenue, EBIT and net income grow double-digit growthwith 2026 in particular being a margin leap year year. Profitability improves significantly: EBITDA margin rises from 18% to over 27%, EBIT margin from 7.9% to almost 15%.
The free cash flow development is initially weak (negative in 2025 due to extremely high CAPEX), but turns strongly positive from 2026 onwards. Net debt rises sharply in 2025/26, but is reduced again from 2027 - at the same time, the leverage ratio falls to a very solid level by 2028.
All in all, ASE provides a picture of scaling growth, rising margins, decreasing risk and clearly improved return on investment (ROE of up to 25 %). For investors, this looks like a classic turnaround into structural growth.
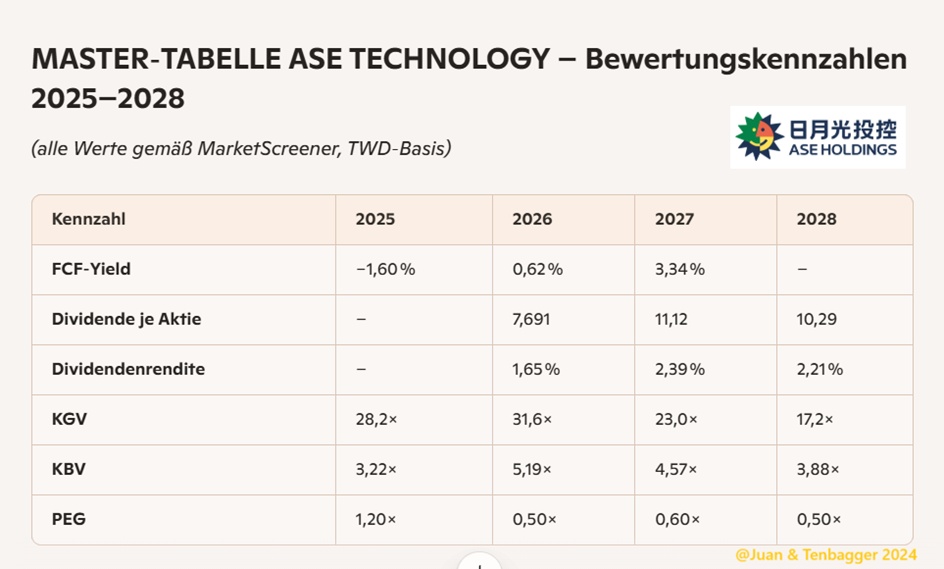
(TWD in millions)
Market value 2,034,392
Number of shares (in thousands) 4,375,036
Date of publication 05,02,2026
Brief summary of the valuation ratios
In terms of valuation, ASE acts as a classic transitional value: expensive in the short term, fair in the medium term, cheap in the long term. The P/E ratio will remain high in 2025-2026 because earnings will only pick up with a delay. From 2027, the picture changes: earnings scale faster than the share price, causing the P/E ratio to fall significantly and the valuation to become more attractive.
The PEG curve is the strongest indicator: from 2026, it is stable in the 0.5-0.6 range - a level that normally indicates undervaluation with high growth growth. The dividend yield increases moderately, but remains more of a bonus than a core argument.
FCF yield turns positive from 2026 and improves strongly, further underpinning the valuation. Overall, ASE shows a profile that will turn into a structurally structurally favorable valuation valuation from 2027 onwards, while the operating performance increases significantly at the same time. For investors, this means Valuation and growth will start to move in the same direction from 2027 - a positive setup.
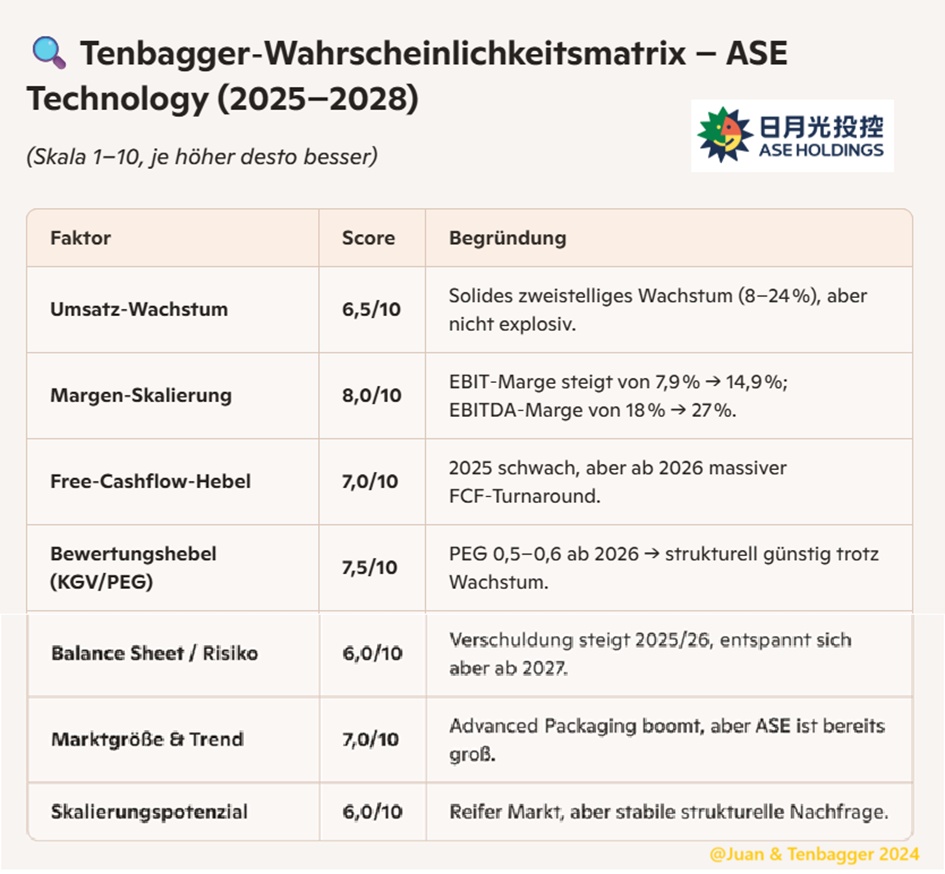
⭐ Overall score: 6.8 / 10
🎯 Realistic tenbagger probability: 10-15%
📌 Juan's conclusion
ASE is not a classic Tenbagger moonshotbut a solid compounderthat will enter a phase from 2027 in which:
- Margins rise sharply
- FCF turns massively
- Valuation becomes more favorable
- Risk decreases
- ROE moves towards 25%
This is a high-quality setupbut not explosive enough for a 10× story in 5-7 years.
A doubling to tripling is more likelynot a tenfold increase.
Performance
1 week +10.16 %
1 month +38.90
6 months +133.44 %
1 year +269.54 %
3 years +322.25 %
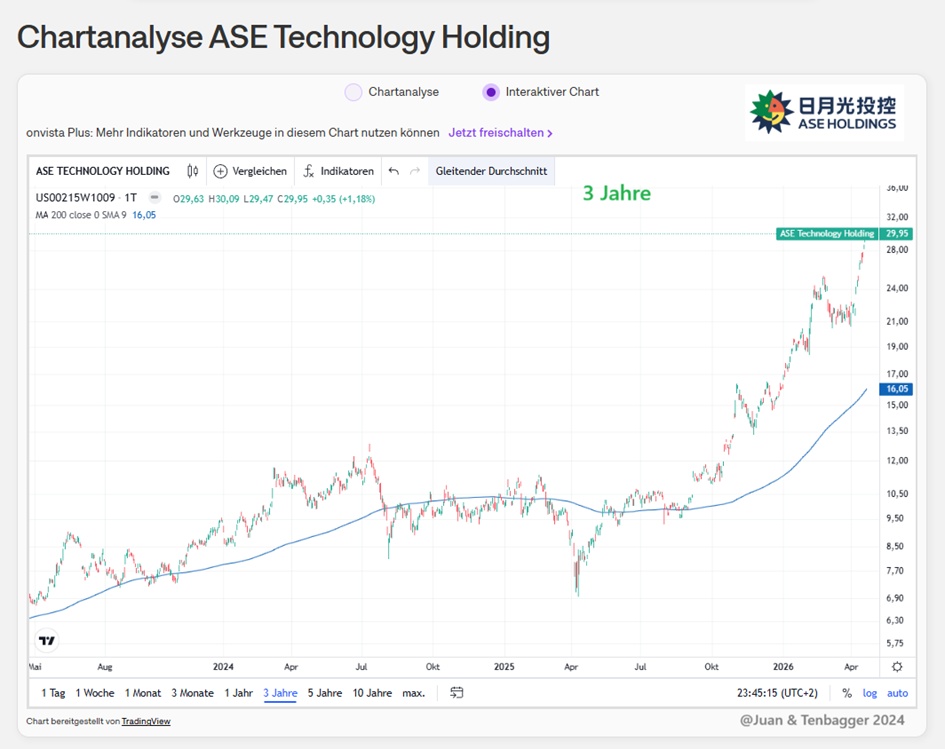
Ladies and gentlemen, the next correction should be coming. Figures will also be presented next week.
PRICE €25.50 (23.04.2026 at 07:52)