

Hello my dears,
now that the memory chip manufacturers are cracking one ATH after the other. I naturally went looking for you again at our beloved vane suppliers.
(too valuable for the sand and potato box @Raketentoni )
Matereals and purity is one of the most important building blocks in semiconductor production. And that's why we have an important supplier from this sector for the weekend.
My dears, what do you think of
$ENTG (+4,37%)
Entegris, Inc. is a provider of high-performance critical materials and process solutions for the semiconductor and other high-technology industries. The company's business segments include Materials Solutions (MS) and Advanced Purity Solutions (APS). The MS segment offers material-based solutions, including materials for chemical vapor deposition and atomic layer deposition, slurries and pads for chemical mechanical planarization (CMP), specialty gases for ion implantation, formulated etch and purification materials, and other specialty materials. The APS segment provides filtration, purification and contamination control solutions that improve the yield and reliability of customers' equipment by ensuring the purity of critical liquid chemicals and gases, as well as the cleanliness of wafers and other substrates used in semiconductor manufacturing processes, the semiconductor ecosystem and other high-technology industries.
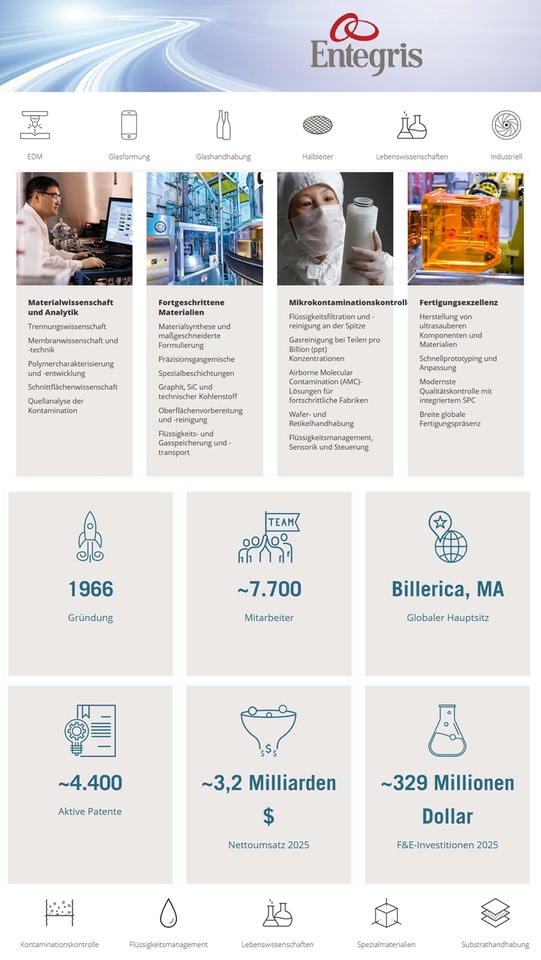
Entegris employs approximately 7,700 people worldwide. Headquartered in Massachusetts, Entegris has manufacturing, customer service and/or research facilities in the United States, Canada, China, France, Germany, Israel, Japan, Malaysia, Singapore, South Korea and Taiwan.
They work with industry leaders in the semiconductor and other high-tech industries to ensure that their customers can take full advantage of the latest advances in microcontamination control, critical materials handling and advanced process materials. In addition to strategic partnerships and membership in key industry groups, such as the International Technology Roadmap for Semiconductors (ITRS) and SEMI, Entegris is actively involved in industry-related technology consortia.
Holds ~4,400 active patents -
Important milestones and acquisitions Entegris®
- 1966
Founded as Fluoroware, Inc.
- 2000
Begins trading under the symbol ENTG on NASDAQ
- 2005
Merged with Mykrolis Corporation, a leading provider of liquid filtration and gas purification technologies
- 2014
Acquires ATMI, Inc. a leading provider of advanced materials
- 2016
Celebrates 50 years in business
- 2017
Partnership with Spectrum Materials and Hubei Jingxing production of specialty chemicals in China
- 2018
Acquires PSS particle size analyzers for liquid applications
Acquires SAES Pure Gas high capacity gas purification systems
Acquires Flex Concepts Fast customized configurations for bioprocessing
- 2019
Acquires Digital Specialty Chemicals Organometallics and other fine chemicals
Acquires MPD Chemicals organosilanes and other advanced chemicals
Acquires Hangzhou Anow Microfiltration Filtration manufacturing in Asia
- 2020
Acquires Sinmat CMP slurries for SiC, GaN, C
Acquires GMTI and CRP Advanced process monitoring for CMP chemistries
- 2021
Acquires BASF's Precision Microchemicals business CMP slurries for SiC and high purity cleaners for HDD
- 2022 Acquires CMC Materials industry-leading CMP slurries and pads
Entegris
As a specialist in contamination control, Entegris (ENTG) has positioned itself as an indispensable partner within the semiconductor industry. The company supplies high-purity materials, specialty chemicals and components to prevent even the tiniest contaminants that could render chips unusable. Customers range from leading semiconductor manufacturers such as TSMC, Intel and Micron to equipment and material suppliers such as Applied Materials and Lam Research. The transition from sub-5 to sub-2 nanometer technologies also increases the purity requirements as complexity increases.
Integration into the ecosystem is to be expanded under new CEO Dave Reeder, who has been in office since August 2025, in order to ensure purer starting materials in chip factories during transportation. This will create new sales opportunities with suppliers. New factories in Colorado and Taiwan are being ramped up. China is also an important pillar with sequential growth of 8 % in the last quarter, where local production is to be expanded to over 90 % in 2026 to circumvent US export restrictions.
Advanced logic chips and HBM memory for AI applications are important drivers, with 3D NAND and advanced packaging also offering new opportunities.
In the last financial year, sales at Entegris Inc. fell by 1.4% from USD 3.2 billion to USD 3.2 billion. At the same time, profit fell by 19.5% from USD 292.8 million to USD 235.6 million. The net profit margin was therefore 7.4% compared to 9.0% in the previous year. On April 30, 2026, Entegris Inc. reported its Q3 figures for the quarter ending March 31, 2026. Revenue in the earnings period amounted to USD 811.9 million (+5.0% compared to the same quarter of the previous year) and profit was USD 92.0 million (+46.3% compared to the same quarter of the previous year).
News
27,05,2026
Entegris berichtet Ergebnisse für das erste Quartal 2026
30,04,2026
Published on February 10, 2026Entegris berichtet Ergebnisse für das vierte Quartal 2025
Published on August 21, 2025Entegris kündigt Pläne für eine Investition von 700 Millionen Dollar in den Vereinigten Staaten an, Technology Center in Illinois
Published on July 18, 2025Entegris eröffnet neues Technologiezentrum in Korea
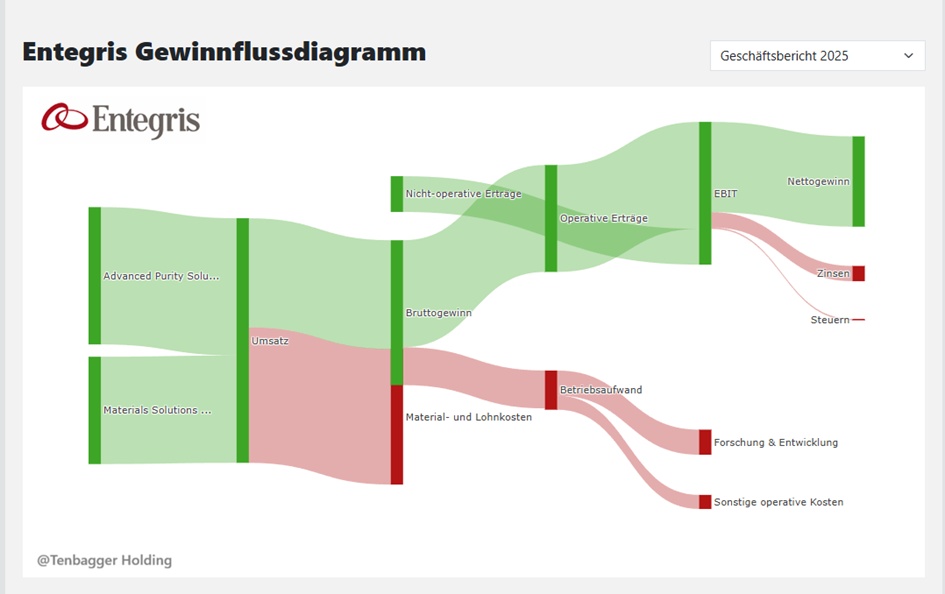
Sales distribution by business segment:
2025 (USD)
Advanced Purity Solutions (APS) 1.8 billion
Materials Solutions (MS) 1.41 billion
Inter-segment Elemation -9.2 million
Geographical distribution of sales:
2025 (USD)
Taiwan 736 million
China 658 million
North America (NA) 562 million
South Korea 428 million
Japan 318 million
Southeast Asia 256 million
Europe 239 million
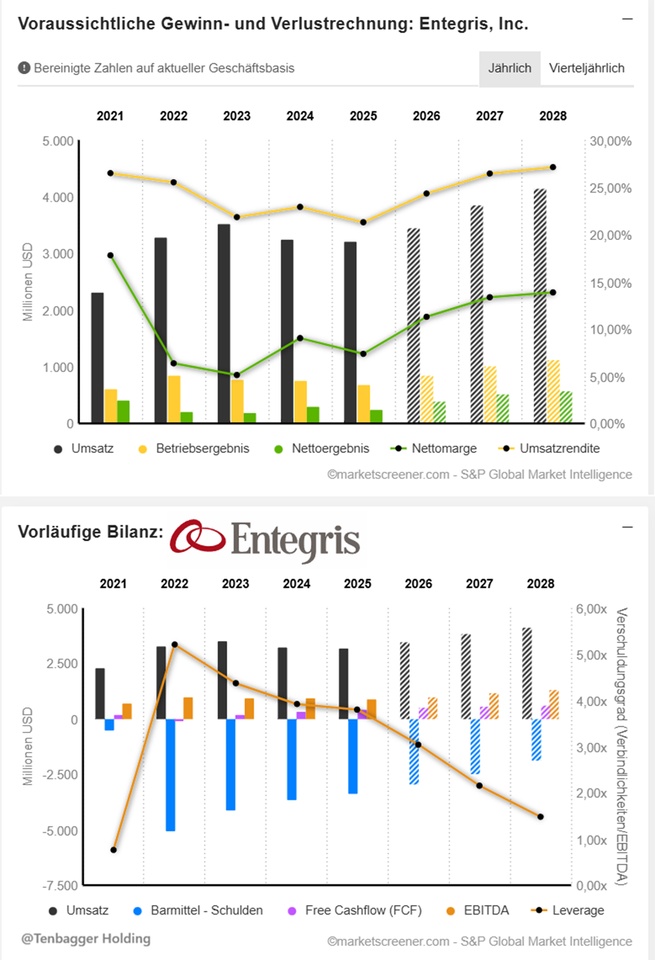
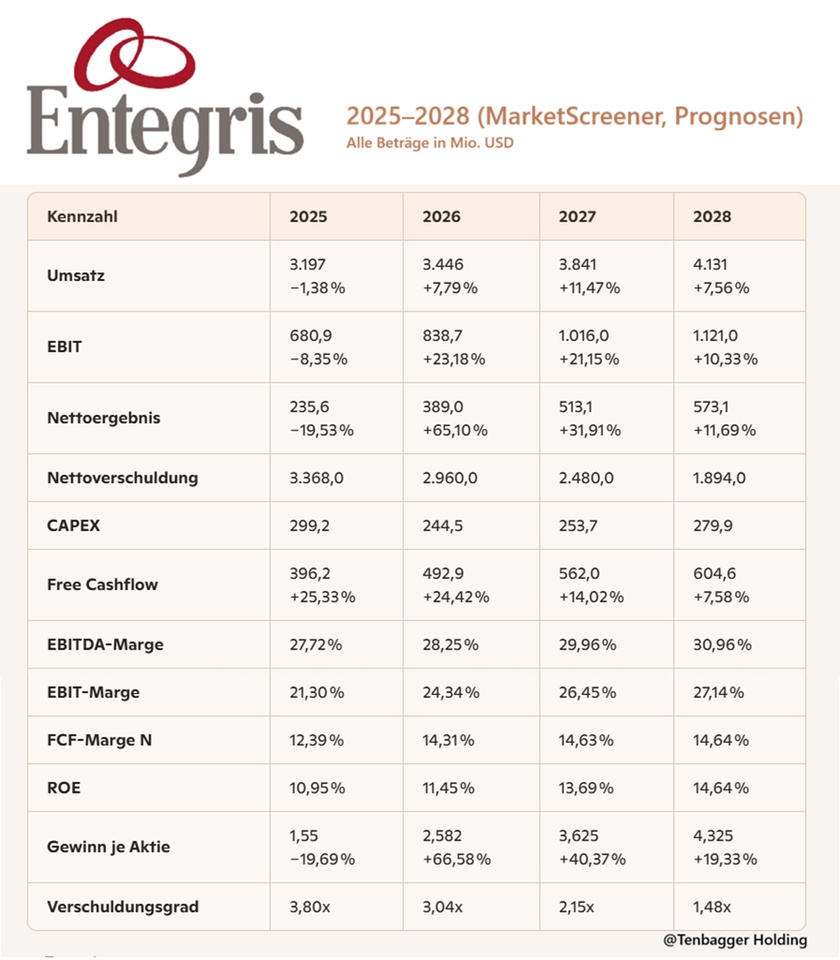
Juan's conclusion - Entegris key financial figures (2025-2028)
"Entegris provides a clear picture: the bottom will be reached in 2025 - after that, the overall figures will pick up strongly. Double-digit growth in sales, EBIT and net profit from 2026 onwards, with margins rising cleanly and free cash flow getting stronger every year. Net debt will fall rapidly and the gearing ratio will be halved by 2028. This is a classic high-quality rebound profile: operating levers will take effect, cash flow will become king again and the balance sheet will visibly improve."
Market value 21,165
Number of shares (in thousands) 152,500
Date of publication 10.02.2026
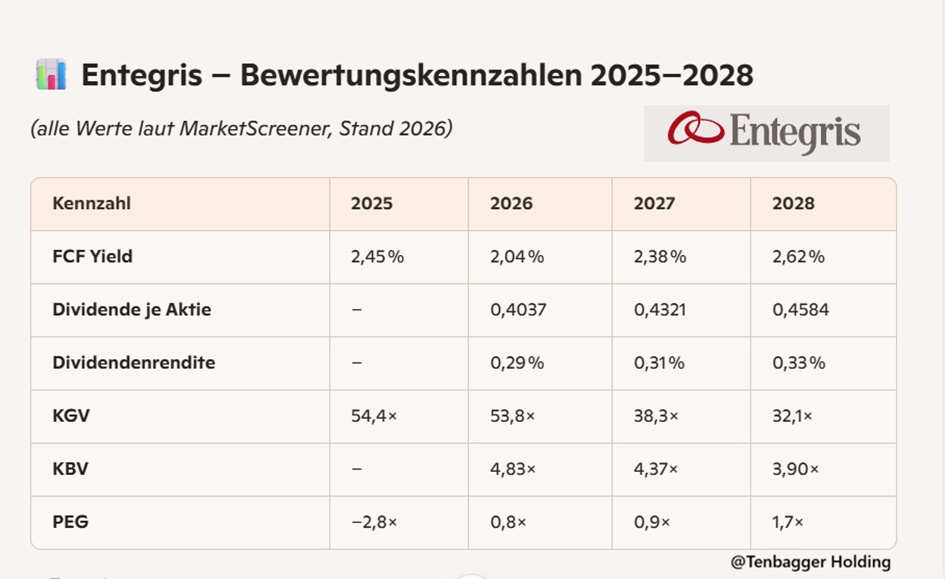
🧩 Interpretation (ultra-compact)
- P/E ratio falls from 54 → 32 → Valuation eases significantly.
- PEG normalizes normalizes from 2026 → Growth back in line with valuation.
- FCF yield increases continuously → Cash flow quality improves.
- P/B ratio decreases → Share becomes more favorable on balance sheet.
- Dividend grows moderatelyyield remains low (typical for high-growth semis).
Juan conclusion - financial ratios + valuation ratios (2025-2028)
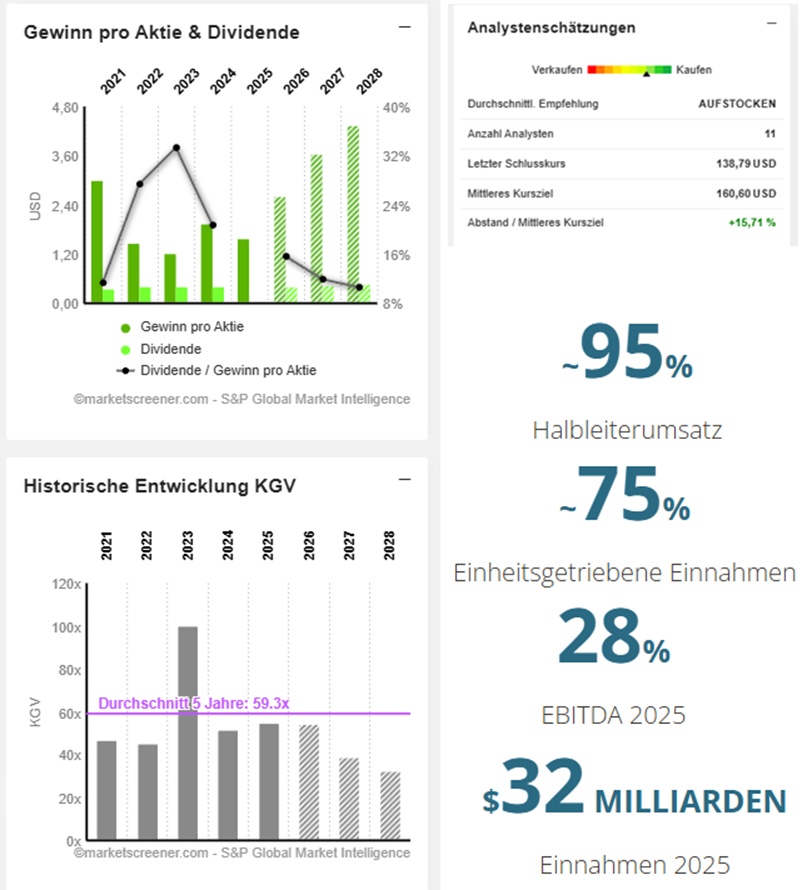
"Entegris shows a clean double signal: operationally, the machine will pick up again fully from 2026 - sales, EBIT, cash flow and margins will increase year after year. At the same time, the valuation is visibly easing: P/E ratio is falling, PEG is normalizing, FCF yield is rising and the balance sheet is getting lighter. This is the combination that Juan loves: strong fundamentals, declining valuation, increasing cash flow. A classic setup where quality becomes affordable again."
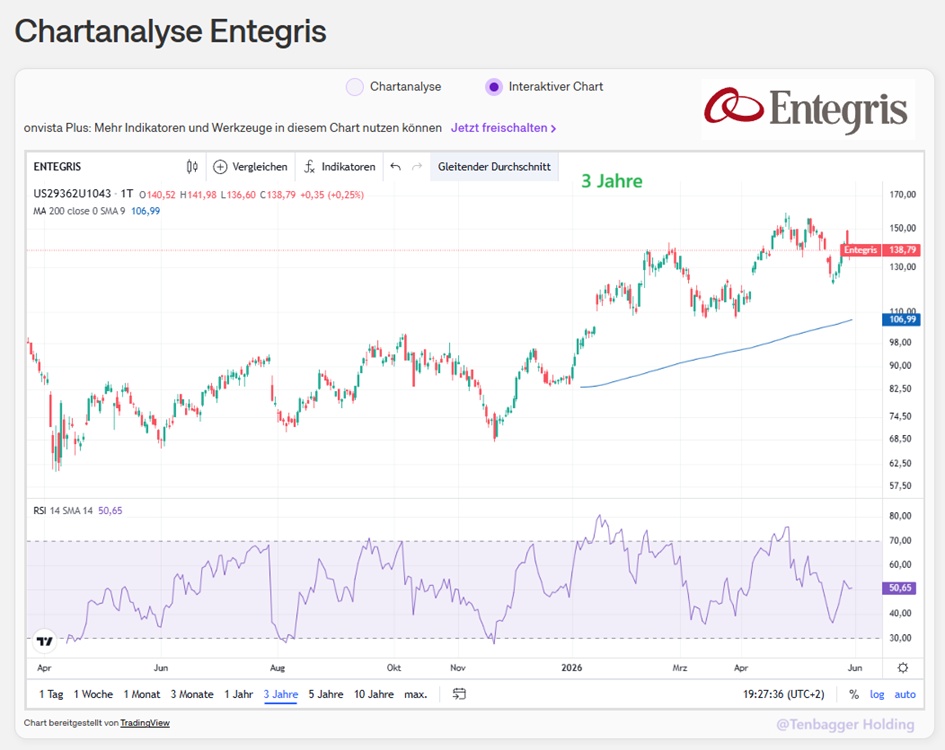
Performance
1 week +2.59 %
1 month -7.08 %
6 months +79.92 %
1 year +91.65 %
3 years +29.44 %
29.05.2026, 22:43:08 -
gettex (EUR)
118.74 EUR


