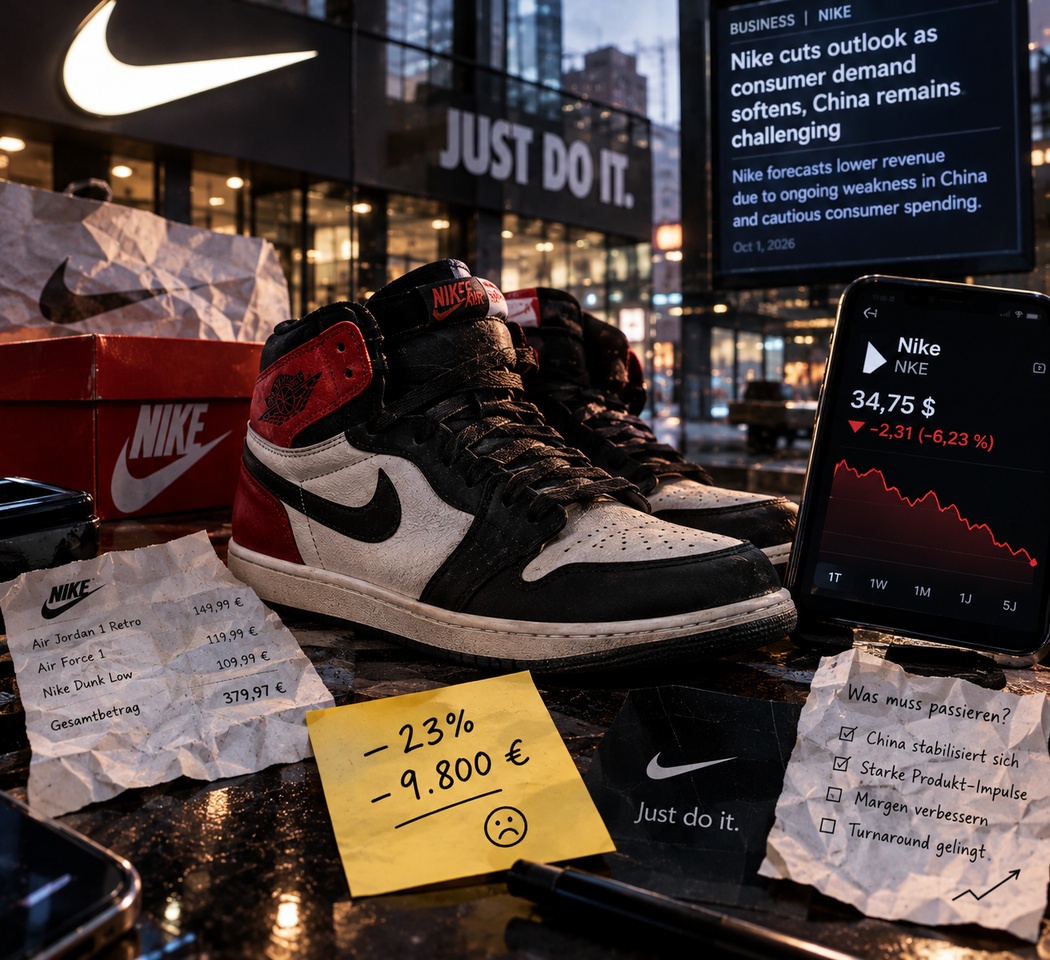
With the last workday of the week comes my final “bagholder” stock feature—Nike ($NKE (+5,24%) ). With a loss of about 23% (just under 10,000 euros), it’s actually hardly a “bagholder” stock at all. But since I think the turnaround will take a little while longer, I’ve put it on the list anyway! 😉
👟 Quick Profile
There’s really not much to say about Nike. I don’t think there’s anyone in the world who doesn’t know the brand. In addition to the core brand, the group also includes Jordan Brand and Converse. Its business ranges from athletic shoes and apparel to sports equipment and direct sales through its own stores and online shop.
📊 Fundamental Data
- Stock price: approx. $34.75
- P/E ratio (TTM): approx. 16.6
- Forward P/E: approx. 25.5
- Dividend: $1.64
- Dividend yield: approx. 4.7%
- Revenue FY 2026: $46.4 billion
- Net income FY 2026: approx. $3.1 billion
📉 How is the business performing right now?
The latest figures for the first quarter of fiscal year 2027 are rather sobering:
- Revenue: $11.2 billion (-4% year-over-year)
- Nike Direct: $4.1 billion (-8% year-over-year)
- China: still one of the company’s biggest challenges
- Gross margin: 42.8% (+0.6 pp)
- EPS: $0.48
The problem is that Nike Direct—that is, the company’s own sales channels, including its online business—continues to struggle. Nike has therefore announced “Pace,” a new multi-year restructuring program. The goal is to save $2.5 billion by fiscal year 2031. This includes further job cuts and a restructuring of the regions.
🤔 Why might the stock be a good buy?
1. The brand remains extremely strong.
Nike enjoys global recognition, sales strength, and an enormous reach in the sports world.
2.
The restructuring could pay off. The Pace program is designed to improve the cost structure and make the organization more efficient. If it succeeds in reducing costs sustainably, it would bring EPS—and thus the P/E ratio—back into acceptable ranges.
3. Expectations are now low.
At a share price of around $35, a great deal of pessimism is already priced in. Should Nike stabilize its revenue growth in the medium term, a revaluation could follow. The market currently doesn’t expect much more.
4. The company continues to pay a dividend.
The yield is currently around 4.7%. That’s nice, but of course not a sufficient reason to buy a stock if the company’s operating performance continues to deteriorate.
⚠️ Why is the stock still so cheap?
China remains a real problem. There, Nike is suffering from lower customer traffic, high inventory levels, and intense discount pressure. In the first quarter, revenue in Greater China fell by 26%. This, of course, also rendered the forecast for fiscal year 2027 obsolete. Revenue is now expected to decline by a high single-digit percentage. Adjusted earnings per share are projected to be between $1.15 and $1.35. So things will get worse for now before they (hopefully) start to improve again starting in 2028 or 2029!
The bottom line is that the turnaround will take time. The cost savings from Pace are expected to unfold over several years. Further job cuts have been announced, and the problems at Sportswear, Jordan Brand, and Converse have not yet been resolved.
🎯 My Bagholder Rating -> 7/10 Bagholder Points
For me, Nike is a classic turnaround bet—though one that will require patience. Nike is a global brand with enormous reach, but strategic mistakes in the past have led to relatively rough waters operationally... and it will take a few years to correct that.
The appeal lies in the fact that expectations are low, and stabilization in China, new successful products, and better margins could make a big difference.
I’m (still) comfortable with my entry price of just under 40 euros. Over a 5-year horizon, I can definitely imagine the price doubling from this level—which would amount to just under 20% per year, plus the dividend. 😉