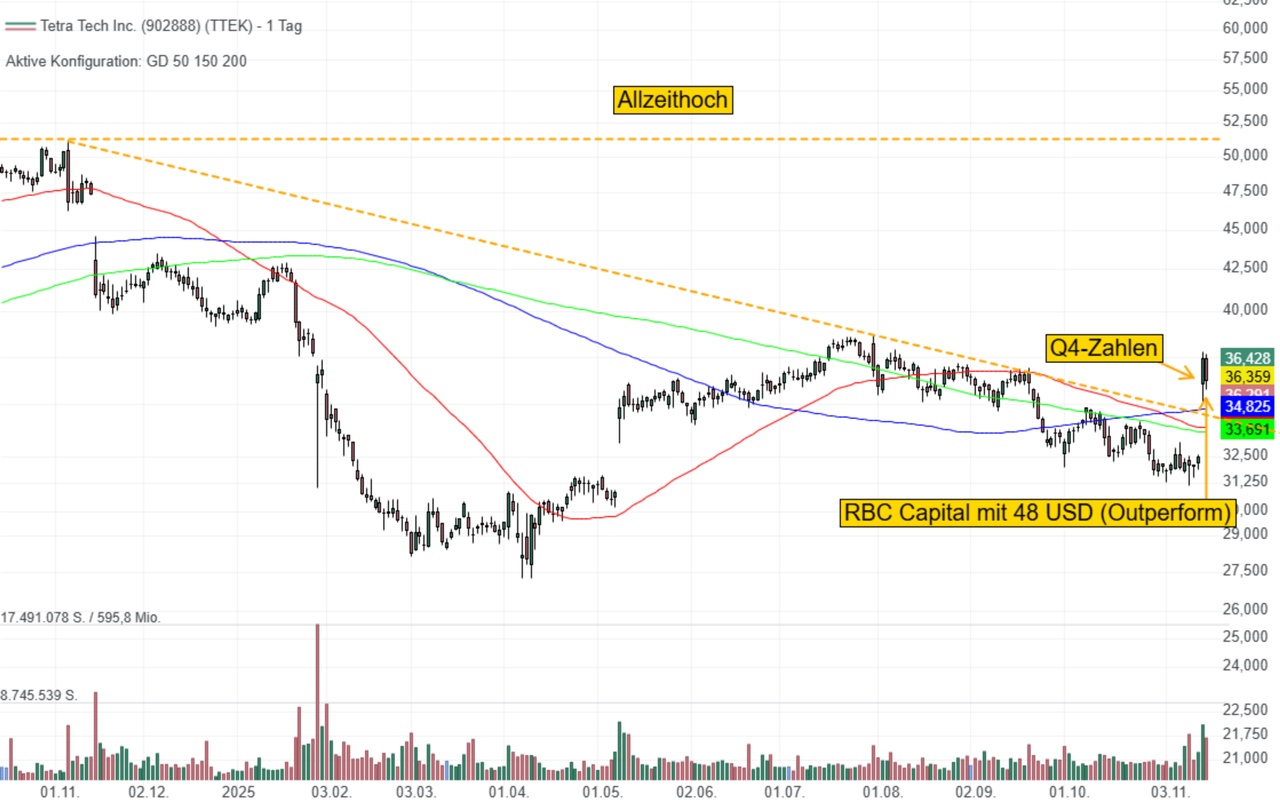
My dears, I remain invested.
The star investor is also @Simpson is also involved.
Tetra Tech (TTEK) generates around 85% of its revenue from engineering and consulting services in the water infrastructure sector. Due to the discontinuation of the previously important USAID funding, Tetra Tech is increasingly focusing on high-end consulting with a higher-margin order backlog of USD 4.1 billion. The defense market also offers good prospects with the expansion of naval bases, flood protection and pollution control. The 4th quarter delivered record sales and net profit as well as the highest margin in 30 years.
There are partnerships with over a dozen hyperscalers and colocation providers for water treatment, automation of digital control systems and commissioning in data centers. A large data center requires over 5 million gallons of water per day, 97% of which is supplied by the now expanded municipal drinking water supply. Texas has announced the highest investment in the state's history at USD 20 billion, from which Tetra Tech could benefit with 60 contracts already in place. Added to this is the increasing demand for electricity, where the planning of substations and electrical connections is leading to a doubling of the US order backlog for high-voltage technology, which is growing by 120% per year.
The share achieved the highest score in the quality check with 15 points and was able to initiate a turnaround attempt on the day of the report with a price increase of 15%. The analysts at RBC Capital raised the price target to USD 48 (Outperform) and consider the forecast for 2026 to be conservative and in line with expectations. The adjusted EBITDA margin is expected to increase by at least 50 basis points p.a. by 2030, which could be exceeded by up to 80 basis points in 2026.