Hello my dears,
Today I went on a search for you. For an exciting growth company in the growing health services sector.
I think it's a great alternative to the more well-known, but sometimes disappointing players.
I look forward to your assessment and opinions in the comments.
( @Iwamoto a little longer for you today).
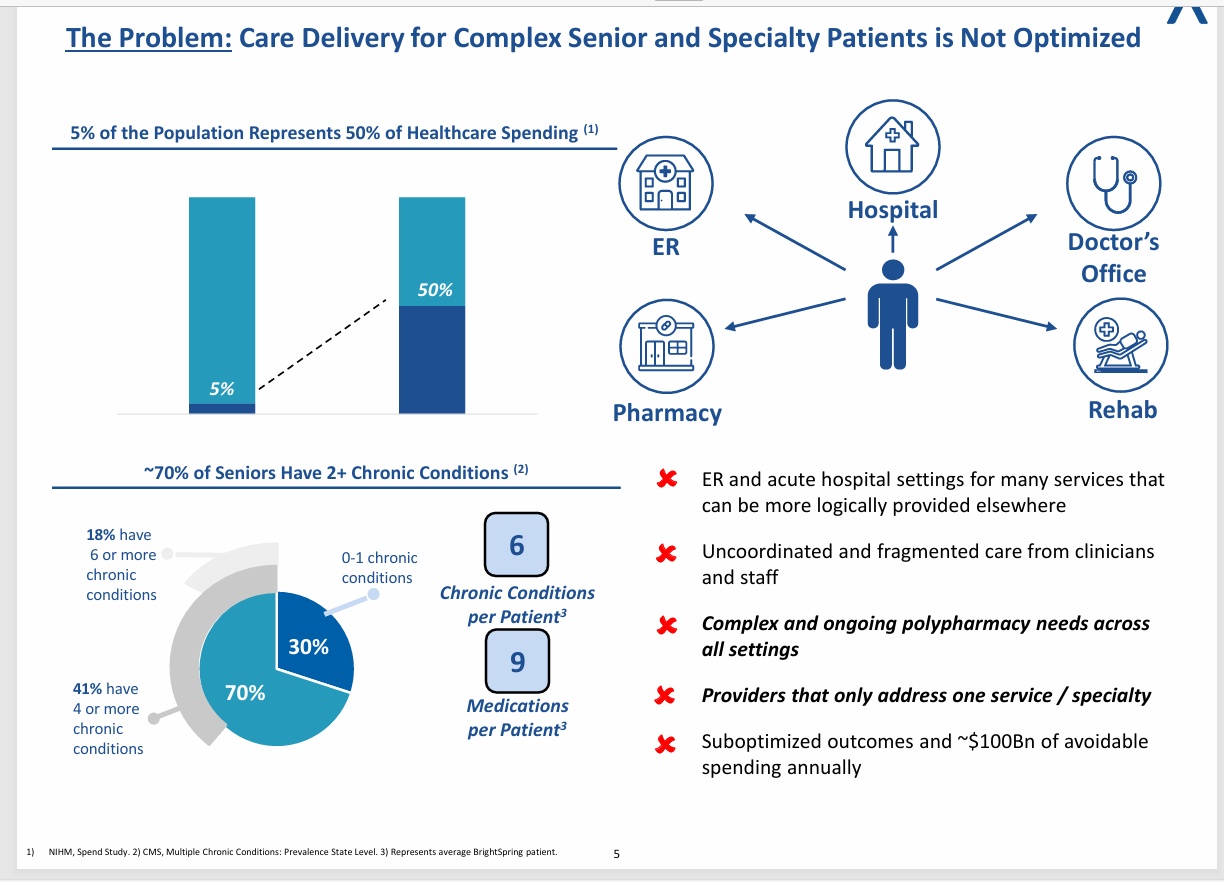
The Brightspring IPO focuses on complex patients in the US healthcare system - the market opportunity is enormous at USD 1 trillion! USD enormous!
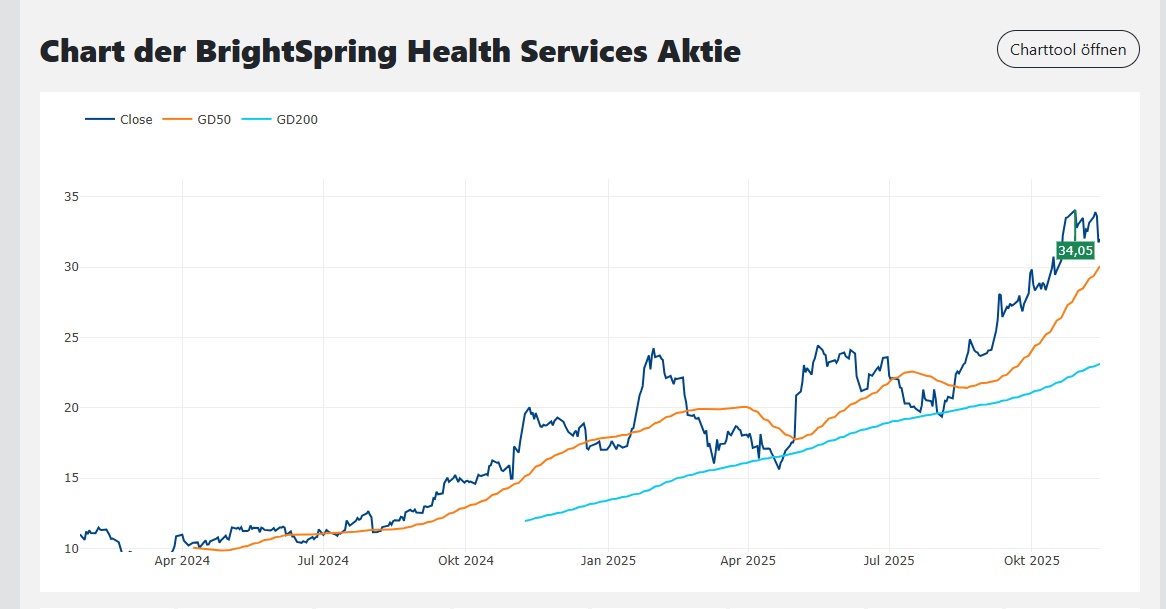
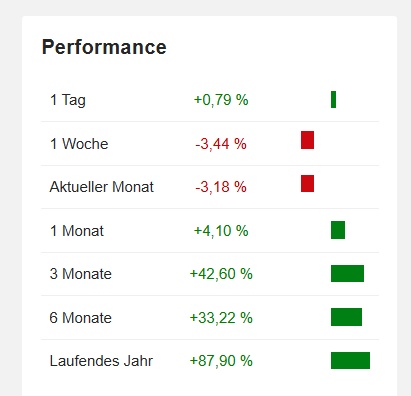
Since the IPO in January 2024, Brightspring's share price has almost only known one direction: upwards. Founded in 1974, the US company offers comprehensive home and community-based healthcare and pharmacy services for people with complex illnesses. The aim: to avoid hospital costs.
Business driver: BrightSpring Health Service (BTSG) is a provider of home care services. The company cares for senior citizens, people with disabilities or cognitive impairments, among others, and offers services ranging from home care and palliative care to specialized medication. In view of the ageing population and the increasing demand for qualified care services, BrighSpring Health Service has excellent growth prospects.
BrightSpring awakens growth fantasies with focus on home care
BrightSpring Health Services (ISIN: US10950A1060) offers comprehensive nursing and pharmacy services for patients in the USA, particularly for senior citizens and people with chronic illnesses. With the recent divestiture of its Community Living business, the company is sharpening its focus on home care and related pharmacy services. Founded in 1974, BrightSpring went public on the Nasdaq stock exchange in January 2024.
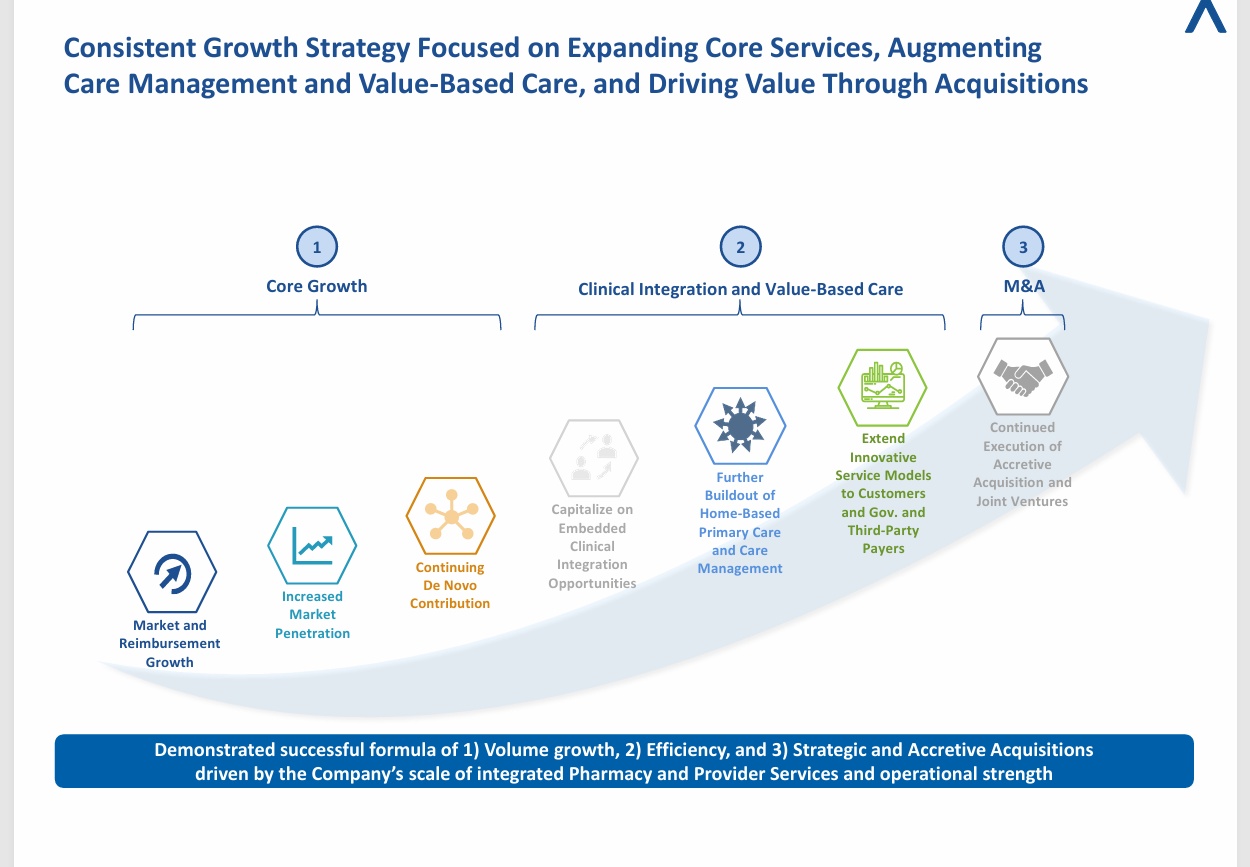
The company pursues an inorganic growth strategy to maintain its position as a leading provider of home care. Profits are constantly being invested in acquisitions, most recently in a service provider from Arkansas and a specialty pharmacy in Texas. In the past financial year 2024, the 10 billion turnover threshold was exceeded for the first time (USD 11.27 billion).
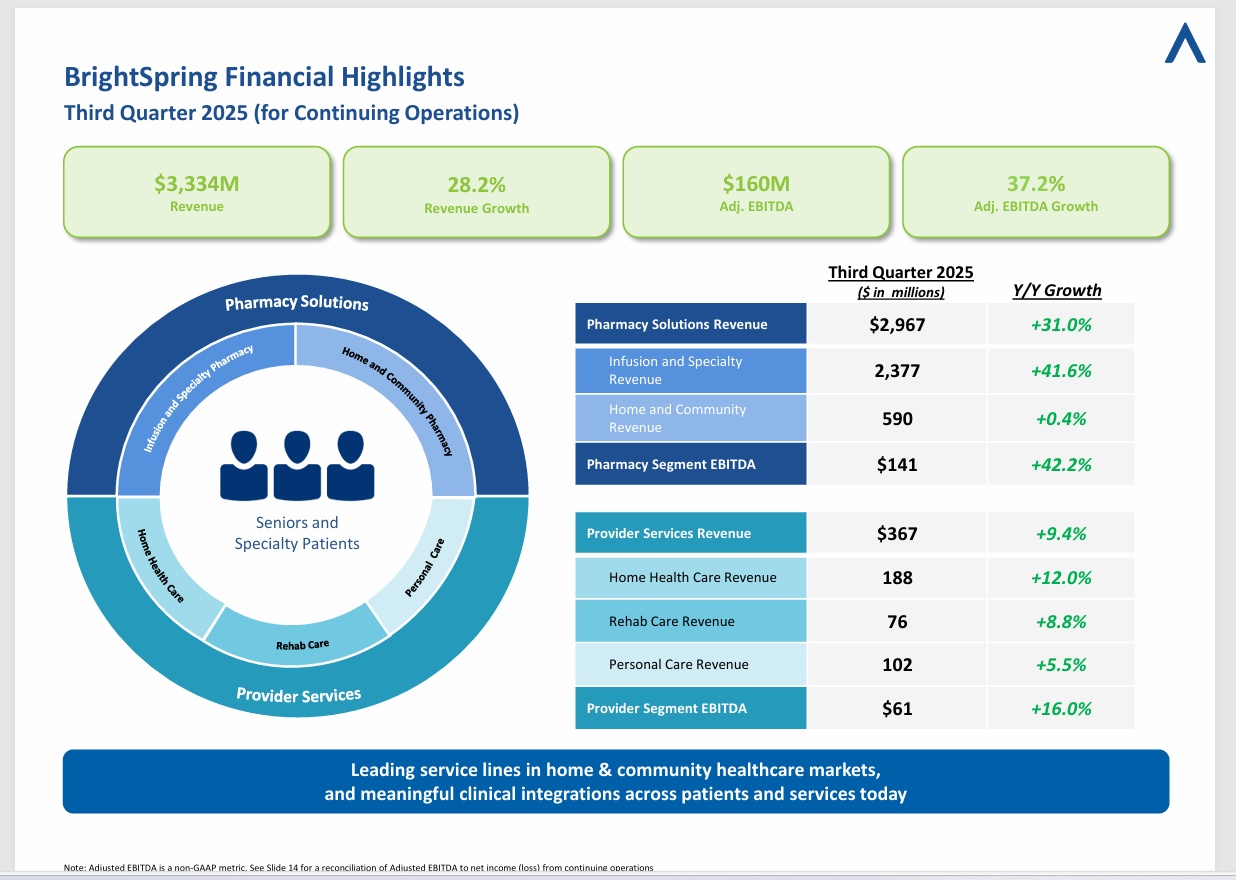
On May 2, 2025, BrightSpring Health Services published its report for Q1 2025. Revenue increased by 26 % year-on-year to USD 2.88 billion, while the company generated net income of USD 0.19 per share, an increase of 111 % and more than double the previous year's figure. an increase of 111%, more than double what analysts were expecting. Investors were also impressed by the increased outlook with expected sales of up to USD 12.5 billion for the 2025 financial year.
Following the figures, the share price exploded by over 30% within a few days. The all-time high of USD 24.82 is now within reach. As long as the market environment remains positive, the share price should continue to rise in view of the extreme earnings surprise of over 100 %.
Conclusion
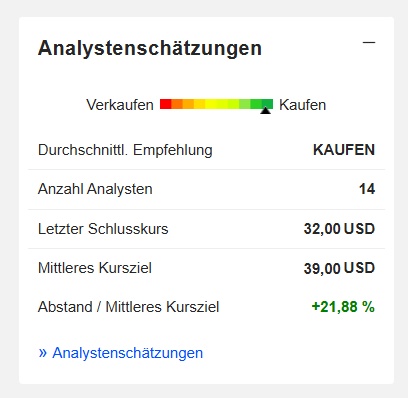
BrightSpring Health Services is convincing with its focus on home care, double-digit sales growth and a spectacular earnings surprise in Q1 2025. The share is benefiting from the strategic realignment and has shown new strength with the recent price jump. Following the rally, the share remains interesting, especially as an anti-cyclical entry opportunity during setbacks.
KKR's investment helps us to improve results for patients.
(The star investor is also invested here @Simpson invested)
Global investment firm KKR acquired BrightSpring Health Services ("BrightSpring") in March 2019. As part of this transaction, BrightSpring merged with PharMerica Corporation ("PharMerica") to become a leading provider of home and community-based healthcare and pharmacy services to indigent and medically complex populations.
KKR's investment has helped us to continually invest in our people and technology during a time of great strain on the healthcare system. Their support has helped us invest over $60 million in our Community Living employees during the pandemic - and increase wages by approximately 23.9% from January 2019 to February 2022.
BrightSpring Gesundheitsdienste - BrightSpring Gesundheitsdienste
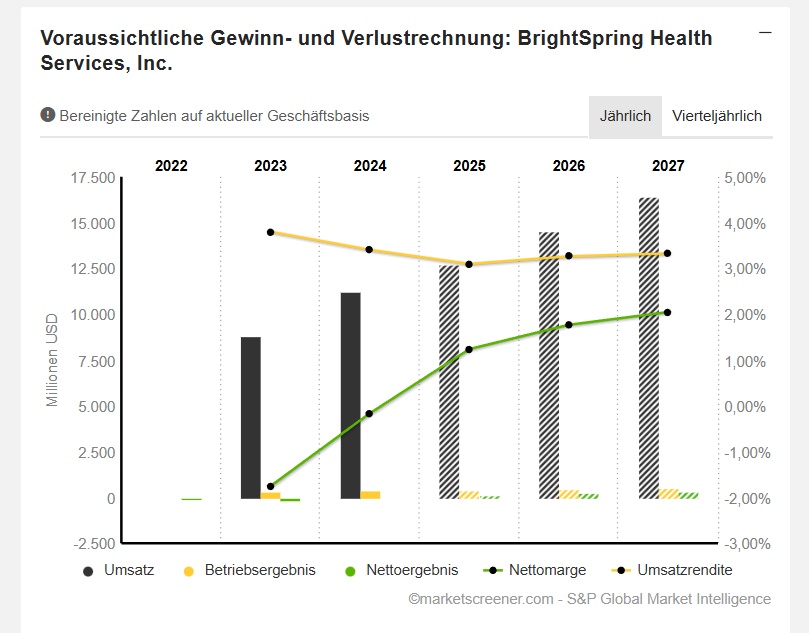
USD in millions
Estimates
Year
Turnover Change
2025 12.723 12,93 %
2026 14.509 14,03 %
2027 16.419 13,17 %
Year
EBIT
Change in
2025 394,3 2,79 %
2026 473,5 20,08 %
2027 546,2 15,37 %
Year
Net result
Change in
2025 157,7 972,92 %
2026 256,7 62,8 %
2027 336,2 30,97 %
Year
Net debt
Free cash flow
2025 2.139 309,2
2026 1.484 348,9
2027 1.260 470,5
Year
EBIT margin
ROE
2025 3,1 % 11,87 %
2026 3,26 % 12,44 %
2027 3,33 % 13,76 %
Year
Earnings per share
2025 0,7186
2026 1,076
2027 1,412
Year
P/E RATIO
PEG
FCF Yield
2025 44.5x -0x 3.52 %
2026 29.7x 0.6x 4.3 %
2027 22.7x 0.7x 5.96 %
No. of shares (in thousands) 206,539
Market value 6,637
@Liebesspieler ???