2Mês·

Is a Humanitarian Crisis Looming in the Iran War? Attacks on Desalination Plants Threaten Water Supplies in the Gulf

NOT INVESTMENT ADVICE


Hello, everyone! As the weekend approaches, I’d like to share some thoughts with you based on our prompts (@Raketentoni , @Aktienhauptmeister ) as we head into the weekend.


The main question is: Will this company be a major beneficiary once the conflict in the Middle East ends?


The company has been affected by—and is still suffering from—the conflict with Iran. However, it operates in a high-growth sector and provides essential services.


Expansion into India offers further potential and would reduce the 50% share of revenue coming from the Middle East.


Let’s discuss: What opportunities do you see with

Energy Recovery
$ERII (+0,67%) ?


Attacks on desalination plants in the Iran war: Is the Gulf facing a drinking water crisis?


Is a humanitarian crisis looming in the Iran war? Attacks on desalination plants threaten the water supply in the Gulf


Qatar, Kuwait, and Bahrain rely on seawater desalination: Securing drinking water for millions of people


Gulf States Fear a Chain Reaction: Attacks on Water Infrastructure Could Affect Entire Regions


Iran-Krieg: Angriffe auf Entsalzungsanlagen bedrohen Trinkwasser


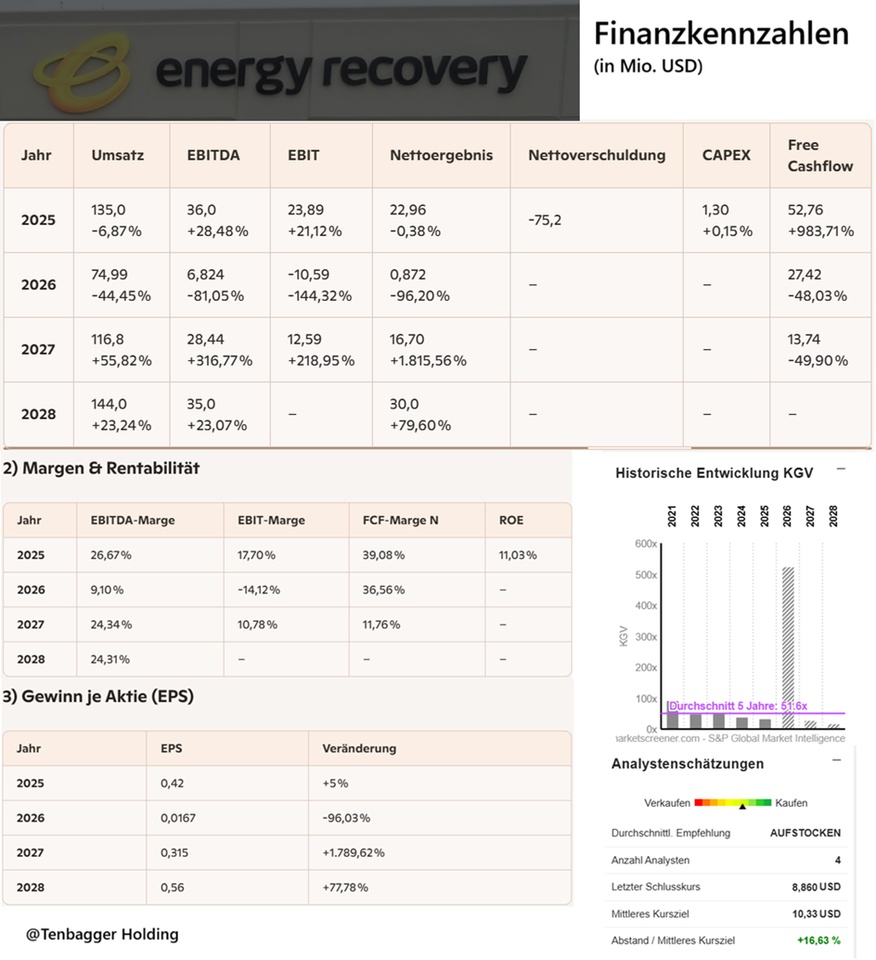
Energy Recovery foresees robust long-term growth (high single-digit end-market growth), but is struggling in the short term with geopolitical delaysthat are slowing the implementation of major projects. Despite these uncertainties, the company is sticking to its CAPEX plan of $3–6 million .


🔍 Key Points

  • Short-term risks:
  • Delays due to geopolitical factors, financing, procurement, and logistics.
  • Visibility and timing for major projects are currently limited.
  • Saudi Arabia Manufacturing:
  • New production facility is expected to significantly reduce costs (transport, shipping, procurement).
  • Margin improvements will come gradually, not immediately.
  • Long-term pipeline:
  • Demand remains consistently strong.
  • The backlog is sufficient several years into the future.
  • The problem remains the timing of project implementation.

📈 Implications for investors

  • Fundamental demand remains stable → positive in the long term.
  • In the short term, however, Uncertainty regarding revenue recognition due to external factors.
  • Margins could rise noticeably starting in 2027/2028 due to the Saudi plant could rise significantly.


July 20, 2026 • 8:00 a.m. EDT

Energy recovery technology to ensure water security for one million people in the Mecca, Al-Baha, and Asir regions of Saudi Arabia

Pressemitteilung ansehen


Second-Quarter Highlights

  • Revenue totaled $12.0 million, down from $16.1 million in the second quarter of 2025.
  • The gross margin was 74.7%, compared to a gross margin of 64.0% in the second quarter of 2025, primarily due to indirect manufacturing costs and channel mix, partially offset by lower volume.
  • Operating expenses totaled $14.8 million, a decrease of 10.0% compared to the second quarter of 2025, primarily due to lower employee compensation costs, including stock-based compensation costs, as well as lower consulting costs, which were partially offset by restructuring costs in the second quarter of 2026.
  • Operating loss of $5.9 million, a decrease of $7.4 million compared to $1.5 million in the second quarter of 2025, primarily due to lower revenue resulting from the war in Iran.
  • Net loss of $3.2 million and adjusted EBITDA(1) loss of $2.6 million.
  • Cash and investments totaling $98.1 million, including cash, cash equivalents, and short- and long-term investments.


(Published on August 5, 2026)


Monday, June 29, 2026

Energy Recovery Celebrates New Projects

Energy Recovery (NASDAQ: ERII) announced today five new contractually approved wastewater projects in India, involving the installation of multiple PX® Pressure Exchanger® (PX) energy recovery systems in industrial reverse osmosis (RO) plants across the country.

The projects reflect India’s stricter regulations on wastewater discharge and a growing shift toward water reuse in the industrial sector. India is home to about 18% of the world’s population but has only 4% of the world’s freshwater resources, and the country’s water demand is projected to be twice the available supply by 2030.

To address this challenge, more and more operators are turning to reverse osmosis treatment strategies. Energy Recovery’s new orders are all for Zero Liquid Discharge (ZLD) systems, a wastewater treatment process that eliminates all liquid waste from industrial facilities but can be energy-intensive. Energy Recovery’s equipment significantly reduces the electricity consumption required to operate the system.

“India is moving rapidly toward water reuse and ZLD, and this shift is really putting pressure on the energy economics of industrial water treatment,” said David Kim-Hak, vice president of wastewater at Energy Recovery.

"Operators in these industries are now integrating energy recovery equipment into their systems from the outset. Bringing the proven efficiency and reliability of our PX technology to these applications helps them reduce operating costs and emissions while also lowering their exposure to volatile electricity prices."

Baystreet.ca - Energiegewinnung begrüßt neue Projekte


Water scarcity is the driving issue


Energy Recovery is a leading provider of energy recovery systems, having become particularly well-known for its PX Pressure Exchange systems. These are patented desalination systems for seawater, brackish water, and wastewater, based on reverse osmosis. The primary driver for Energy Recovery is thus the growing demand for freshwater. According to the United Nations, a global supply shortfall of 40% in drinking water could emerge worldwide as early as 2030. Energy Recovery can also improve the efficiency of wastewater treatment and CO₂ cooling systems.


Energy Recovery, Inc. develops and manufactures energy-saving technologies for critical infrastructure. The company’s business segments include “Desalination,” “Wastewater,” and “Future Technologies.” The “Desalination” business segment includes hydraulic turbochargers and pumps used in seawater desalination plants. The “Wastewater” segment includes hydraulic turbochargers and pumps used in wastewater treatment plants. The “Future Technologies” segment focuses on the sales and support of activities related to new technologies, such as the PX G1300, which is used in industrial and commercial refrigeration applications. Pressure exchanger products include Low-Pressure PX, High-Pressure PX, Ultra High-Pressure PX, the PX Q Series, and PX PowerTrain. Pump products include the CPXP axial piston pump, the ATMP high-pressure pump, the ATMP pressure-boosting pump, the HPXP high-pressure centrifugal pressure-boosting pump, the HP pump, the UHP pump, and the VPXP pump. The company serves the brackish water reverse osmosis (RO) plant sector, modular RO systems, and the retrofit industry.

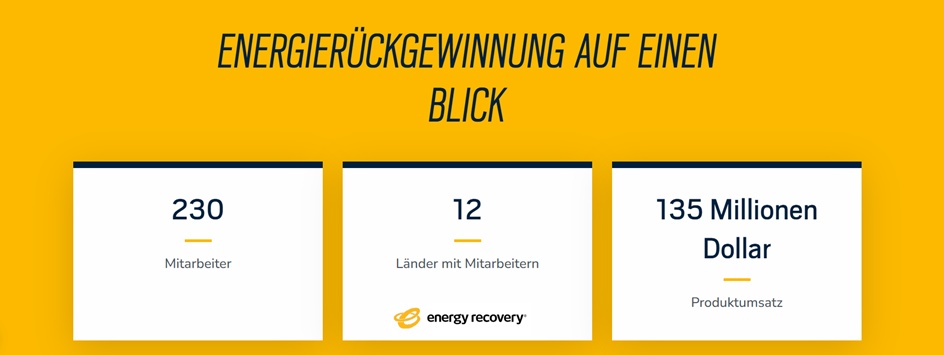
Number of employees: 230


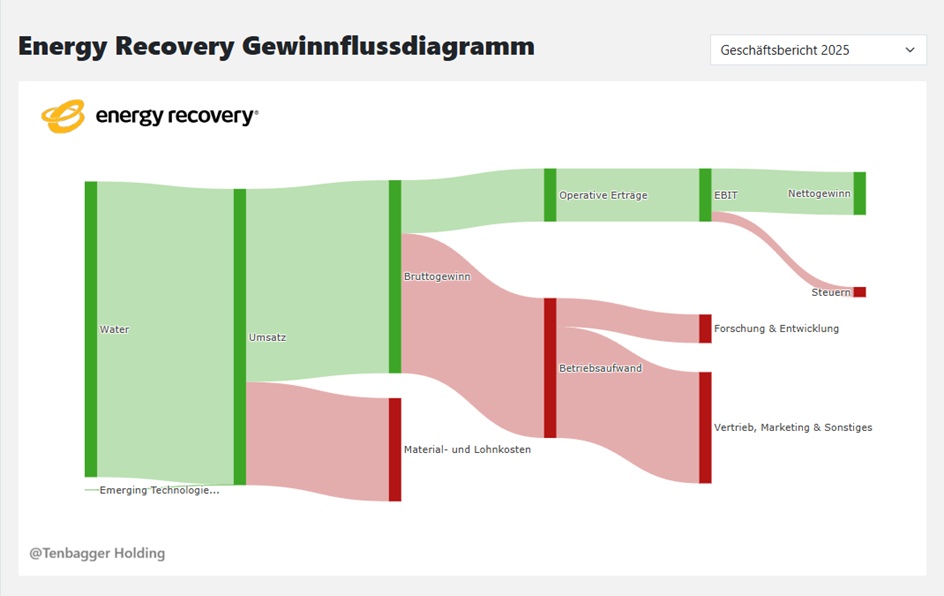
Geographic revenue breakdown:

2025 (USD)

Middle East 68.18 million

Others 51.8 million

Africa 15.01 million
attachment


Energy Recovery Reports its Second Quarter 2026 Financial Results

Energy Recovery berichtet seine Finanzergebnisse für das zweite Quartal 2026 :: Energy Recovery (ERII)

attachment


attachment


attachment


Date of publication: February 25, 2026
attachment

August 7, 2026, 12:14:10 p.m. •

gettex (EUR)

7.524 EUR


$ERII (+0,67%)

previw image
16
10 Comentários

imagem de perfil
@Tenbagger2024, thanks for the tag! I took a close look at Energy Recovery’s ($ERII) setup and compared your narrative directly with a rigorous analysis of the numbers—here’s my breakdown:

The niche toll booth of the desert drinking water supply
Energy Recovery ($ERII) doesn’t manufacture complete desalination plants; instead, it supplies the indispensable core component—the PX Pressure Exchangers. As a global technology leader, ERII acts as a highly profitable toll booth for global seawater desalination: Anyone producing drinking water on a large scale in the Middle East can hardly do without ERII’s systems.

🛠️ DNA Check
• Gross Margin Champion: With a phenomenal gross margin of 74.7% (Q2 2026), ERII holds an unassailable technological pricing monopoly.

• Extremely clean balance sheet: No net debt and approximately $98.1 million in cash and investments safeguard the company even during prolonged dry spells.

• Megatrend Tailwind: Global pressure on drinking water infrastructure (climate change, population growth) ensures consistently high underlying demand.

🚀 Growth Leverage & Catalysts
• Saudi Arabia Plant: Localizing manufacturing will sustainably reduce freight, customs duties, and logistics costs starting in 2027/2028.

• Catch-up potential in the Middle East: Should geopolitical conditions stabilize or de-escalate, the backlog of projects must be cleared quickly.

• Geographic diversification: The targeted market entry into India will gradually reduce concentration risks in the Middle East.

⚠️ Valuation & Risks
• Extremely cyclical project trajectory: ERII is not a steady compounder but is heavily dependent on the timing uncertainty of massive megaprojects (the revenue slump in Q2 2026 illustrates the full extent of this cyclicality).

• Geopolitical risk: The Middle East conflict delays order calls and at times drives the TTM operating margin deep into negative territory (-49%).

• Historical failures: The failed expansion into CO2 refrigeration technology reveals risks outside the core niche.

Jack’s Verdict:
“Energy Recovery is a prime example of a technologically brilliant monopoly product in a niche market that is rock-solid on the balance sheet—but suffers greatly from project cyclicality and geopolitics. 2026 will be a transitional year from an operational standpoint. For quality portfolios, ERII is currently a candidate for the watchlist; for rebound speculators, the stock will become interesting if geopolitical tensions ease and earnings prospects improve starting in 2027.”

Status: 🟡 WATCHLIST / TURNAROUND SPECULATION
Reaper Score: 3/10
•
3
•
imagem de perfil
@Aktienhauptmeister Thanks, I think so too—it's an exciting company to keep an eye on.
•
1
•
imagem de perfil
@Aktienhauptmeister
I asked if he wanted to comment on that :D

But man, I'm really up for this! 🚀

Jack (@Aktienhauptmeister) certainly tried his best and, unlike many investors, at least checked the gross margin and the balance sheet, but his analysis has **a massive miscalculation** and **huge blind spots**.

Let’s fire up the dissection table and break down Jack’s analysis piece by piece!

---

### 1. What Jack got RIGHT (Fair Play) ✅

* **The business model:** The point that ERII isn’t a full-fledged plant manufacturer but rather provides a high-margin “toll booth” product in the form of PX Pressure Exchangers is described succinctly.


* **The gross margin & balance sheet:** He correctly identified the 74.7% gross margin in Q2 2026 and the ~$98.1 million in cash on hand with no significant debt from the financials.


* **The Catalysts:** He correctly identified the factory in Saudi Arabia (production/assembly starting in 2027) as well as the orders in India aimed at reducing concentration risk.


---

### 2. The Big Blunder: Where Jack Got the Numbers Wrong! ❌

Here, Jack made a massive mistake with the numbers:

> **Jack’s Statement:** *“...drives the TTM operating margin deep into the red at times (-49%).”*
> **Fact check:** **WRONG!** Jack is confusing the single quarter (Q2 2026) with the TTM (Trailing Twelve Months) figure!
> In Q2 2026, the operating loss was -5.9 million USD on 12.0 million USD in revenue. That actually results in an operating margin of **-49.17%** for this **single quarter**.
>
>
> However, on a **TTM basis (last 12 months)**, ERII is still **in the black with an operating profit of $26.2 million**! A TTM margin of -49% would mean that the company is burning through hundreds of millions over the course of the entire year—which is simply a unfortunate combination of factors.
>
>

---

### 3. What Jack COMPLETELY OVERLOOKED (The Blind Spots) 🙈

Just like Tenbagger, Jack completely ignores the stock’s most serious operational risks in 2026:

#### 1. The epic leadership chaos at the C-level (management vacuum)

Jack doesn’t mention a single word about the fact that ERII is currently being run without a leader!

* CEO David Moon has resigned prematurely.


* CFO Mike Mancini has thrown in the towel and quit.


* The company is currently being run solely by **interim managers** (Alex Buehler & Aidan Ryan). Facing a geopolitical crisis without a permanent CEO and CFO poses a massive risk to operational execution.


#### 2. The Complete Withdrawal of the Annual Forecast

ERII didn’t just have a “bad quarter”—management has **completely scrapped the entire annual forecast for 2026**.

#### 3. The astronomical P/E ratio for 2026

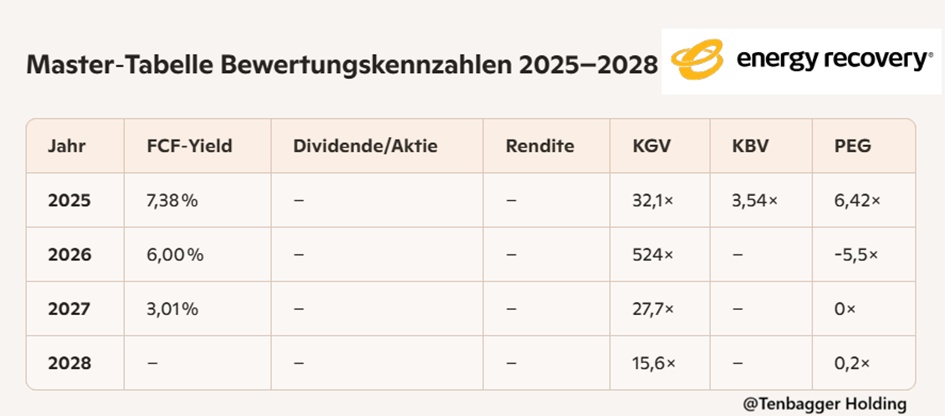
Jack does not provide a specific rating in his “Reaper Score” of 3/10. However, the facts show that the forward P/E ratio for 2026 stands at an **absurd 102.7x**. Analysts have revised their earnings forecasts for the next quarter downward by a staggering **-94.8%**.

#### 4. Chart Reality & Technical Signals

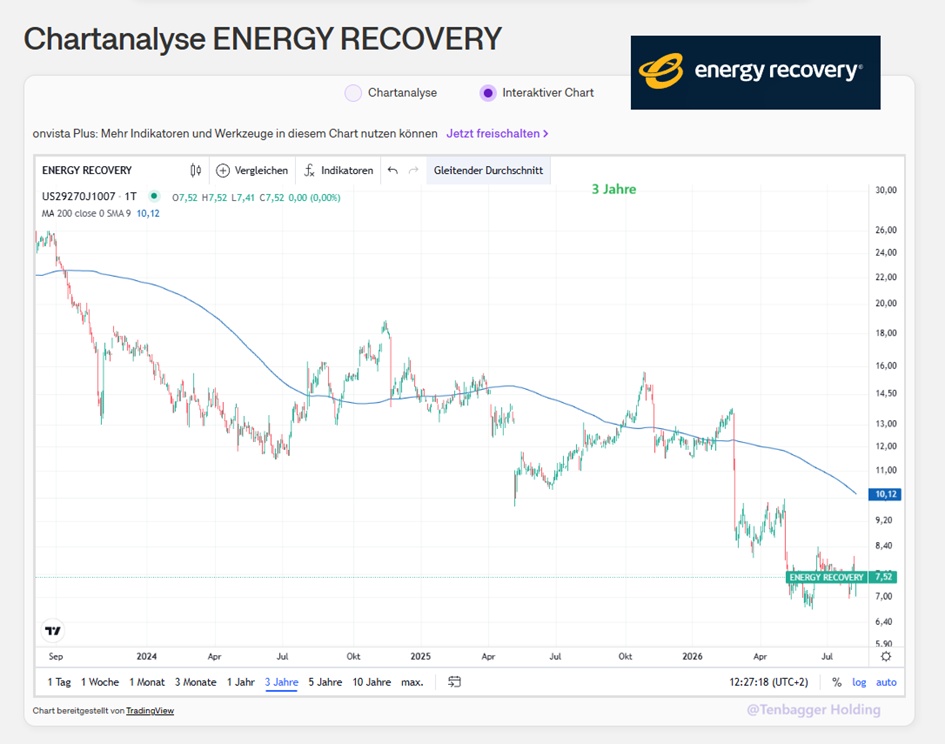
On a weekly basis, the stock is languishing at its 52-week low ($7.83). All oscillators and moving averages are at **“Sell” / “Strong Sell”**. Jack doesn’t mention a single word about this.

---

### Conclusion on Jack’s Analysis 🎯

While Jack has understood the product’s strengths, his risk analysis is incomplete:

* He confuses the **quarterly margin with the TTM margin**.


* He completely overlooks the **management chaos (CEO & CFO gone)**.


* He does not mention **any specific valuation metrics (P/E ratio ~102x)**.

His final conclusion (*“Watchlist / turnaround speculation”* for 2027/2028) happens to be generally correct, but his reasoning is imprecise.

Greetings from Denmark

Yours, Raketentoni
•
2
•
imagem de perfil
@Raketentoni Hi Rakentoni, my partner in crime ✌️

Thanks for taking a close look and breaking it down so clearly!
You’re absolutely right about the margin grid: The -49% figure comes specifically from the disastrous Q2 2026 (-$5.9 million EBIT on $12 million in revenue) and doesn’t belong in the TTM field. On a 12-month basis, the margin is in the black at around +$26.2 million on an operating basis. That was an incorrect allocation in the table grid.
Your comments on the C-level vacuum (the resignations of CEO David Moon and CFO Mike Mancini) and the scrapped annual targets also hit the nail on the head. These were also mentioned in the analysis but were overlooked in the summary.

This doesn’t change the conclusion much, but it sharpens the picture: ERII is currently not a quality compounder, but at best a turnaround watchlist position for 2027/2028, once management and the pipeline are back on track.

Great fan check—greetings back to Denmark!
•
1
•
imagem de perfil
Hey, @Tenbagger2024! 🚀

You’ve cracked open an exciting—but operationally extremely troubled—specialty stock for the weekend: **Energy Recovery, Inc. ($ERII)**!

You’re asking who stands to benefit the most from an end to the Middle East conflict? I’ve relentlessly pored over your data, the InvestingPro reports, the latest Q2 figures from early August 2026, and the weekly chart signals.

Here’s the detailed fact analysis: what’s **correct** about your statements, where you’re **overlooking** key **risks**, and the **fact-based answer** to your main question.

---

### 1. Fact Check: What’s TRUE about your statements ✅

* **The Middle East as a bottleneck (>50% of revenue):** Your statement regarding revenue concentration in the Middle East is accurate. In fiscal year 2025, **$68.18 million** of the total revenue of ~$135 million came from the Middle East region (~50.5%).


* **Withdrawal of the 2026 annual forecast:** Correct. Due to geopolitical conflicts and the associated project delays (a 6–9-month postponement from 2026 to 2027), management has completely suspended the annual forecast for 2026.


* **Expansion in India:** Exactly correct. On June 29, 2026, 5 new ZLD wastewater projects were secured in India (30,000 m³/day). With this, ERII now supports over 50 projects in India with a capacity of more than 230,000 m³/day.


* **Q2 2026 Key Figures (as of August 5, 2026):** Your figures for the Q2 financial statements are accurate:


* Revenue: **$12.0 million** (a sharp decline from the $16.1 million in Q2 2025).


* Gross margin: **74.7%** (industry-leading).


* Operating loss: **-5.9 million USD**.


* Cash and investments: **98.1 million USD** (cash and cash equivalents significantly exceed total debt).


* **Saudi Arabia factory:** The planned overseas manufacturing/assembly (target: Q1 2027) is intended to reduce freight costs and meet local regulations.


---

### 2. Fact Check: Where You’ve OVERLOOKED Concerns & Glaring Risks ❌

You paint a picture of an innocent victim of geopolitics. However, the data reveals significant **self-inflicted problems**:

#### ❌ 1. Leadership Chaos at the C-Level (Management Risk)

You mention the geopolitical risks but gloss over the acute leadership crisis: CEO David Moon has resigned prematurely, and CFO Mike Mancini has quit. The company is currently being run solely by interim managers (Alex Buehler as interim CEO, Aidan Ryan as interim CFO). This makes strategic implementation extremely difficult.

#### ❌ 2. The 2026 valuation is astronomically high

You speak of stable fundamentals. Looking at the valuation metrics for the current year, 2026, the stock is under extreme pressure:

* The estimated forward P/E ratio for the end of 2026 stands at **102.7x** based on a meager annual EPS of $0.08.


* Analysts have slashed EPS expectations for the upcoming third quarter of 2026 by **-94.8%**, from €0.17 to €0.0087.


#### ❌ 3. Failed Diversification

The exit from the CO2 refrigeration business (retail grocery) in early 2026 represents a failed diversification attempt that incurred restructuring costs and has made the company once again purely dependent on the water segment.

---

### 3. Weekly Chart Analysis & Technical Signals 📉

A look at the data sheet and the weekly chart:

* **Price Trend:** The stock is trading at **€7.58 / $8.65** and is hovering dangerously close to its 52-week low ($7.83). Over the past 6 months, the stock has lost **-42.2%**.


* **Distance from Averages:** The price is trading at only **73.5% of the 200-day/weekly average** (classic, intact downtrend).


* **Momentum Score:** The momentum score is a dismal **1.10 out of 5 points**. The technical oscillators are signaling a clear **"Sell"**.


---

### 4. Answer to your main question: Will ERII be the big winner when the Middle East conflict ends? 🎯

**Factual yes (in the long term):**

* Over 50% of the business depends on the Middle East. If the military conflicts end, the postponed seawater desalination projects (SWRO) will be greenlit again. Since ERII has over 35,000 units in the field and holds a near-monopoly position in pressure exchangers (PX), orders will flow reliably again starting in 2027/2028.


* Analyst forecasts confirm this post-crisis effect: EPS is expected to skyrocket from $0.08 (2026) to **$0.67 (2027)** and **$1.16 (2028)**. This would cause the P/E ratio for 2028 to plummet to a ridiculously low **7.5x**.


**De facto “no” (for the immediate future):**

* An end to the conflict **does not** resolve the leadership vacuum at the top, does not halt the slump in aftermarket revenue (-32% in Q1 2026), and does not magically restore the lost fiscal year 2026.


* In the short term, with a weekly “sell” signal and a P/E ratio of >100, you’re catching a falling knife.


**Conclusion:**
Fundamental daydreams are pointless as long as geopolitics remain a roadblock and there’s no permanent CEO at the helm. A rebound candidate for the watchlist starting in 2027, but currently a speculative gamble!

Greetings from Denmark

Yours, Raketentoni
••
imagem de perfil
@Raketentoni Hi there, thanks for the quick reply and assessment. For me, though, it’s definitely an interesting candidate for my watch list. It’s important to mention that the leadership crisis is also partly to blame for the poor performance. Unfortunately, that’s not covered enough in my report (sorry). According to the latest earnings report, however, the company claims to have overcome this crisis. We’ll have to wait and see.
•
1
•
imagem de perfil
@Tenbagger2024 I'd be happy to, but that's what the prompts are for—to find things that others overlook or that might have a twist to them.
I like your ideas, but right now I'm busy restructuring my strategy and reorganizing my portfolio :)
•
1
•
imagem de perfil
@Raketentoni Maybe he'll let us in on it. Yeah, the prompts are really good. In the end, we've almost come to a similar conclusion. I think they should find a new CEO, and Donald really needs to strike a deal with Iran soon. That should ultimately help the company get back on a somewhat steadier course. Until then, watch
•
1
•
imagem de perfil
@Tenbagger2024 Yeah, I'll keep you posted, but first I need to check offline to make sure everything's running smoothly. That includes some heated discussions with Mr. Prompt :) It's definitely going to be exciting. It's kind of crazy to rethink your strategy after all these years, update it, and try something new.
I’ll go into detail about it in early September.
••
imagem de perfil
@Raketentoni I'm curious—maybe I'll bet a little on momentum, too. I think that should work well with Mr. Prompt, and it might boost the return a bit.
•
1
•
Participar na conversa