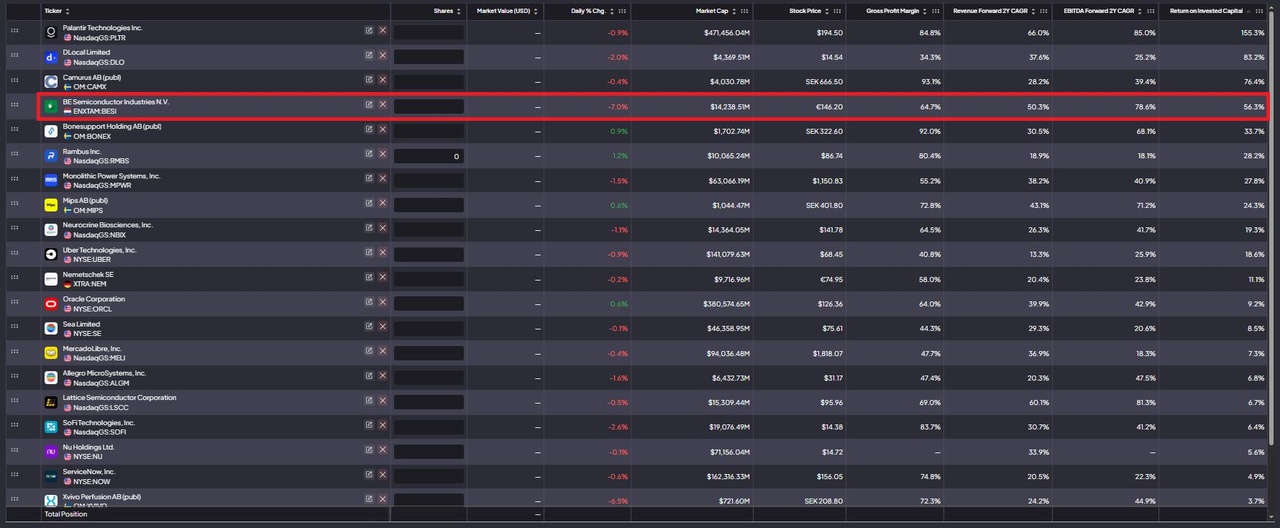
Even with $BESI (-6,48%) things really took off...
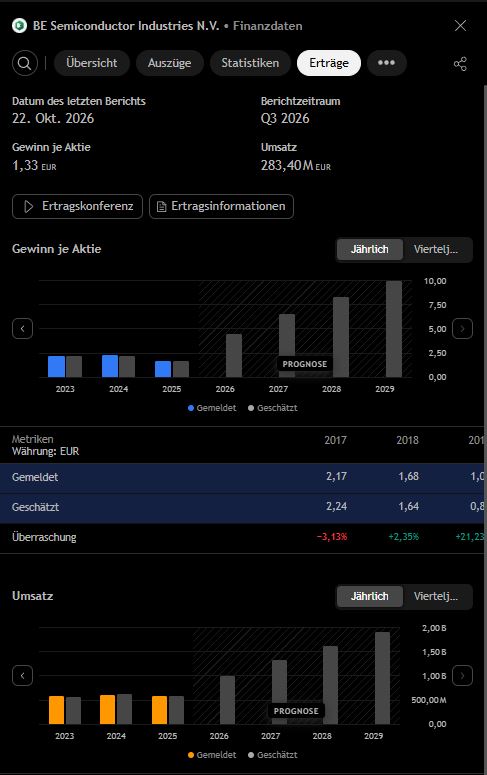
Q3 revenue: 283.4 million – +13.4% QoQ and +113.6% YoY
Order intake: 17% QoQ – +96% YoY
Cash flow: 107.2 million – +20.4% QoQ – +323.7% YoY
Improved gross margins due to product mix and price increases
100 million share buyback program
Outlook
Gross margins between 63–65%
Revenue in Q4 will be flat ±5% (the market likely won’t take kindly to this)
Positive order momentum is expected to continue in the fourth quarter in both the traditional segment and wafer-level assembly, supported by the expansion of AI capacities, data centers, photonics, and market share gains
The introduction of hybrid bonding is progressing, but the market potential remains uncertain. The timing of when the technology will gain widespread adoption in large volumes depends on the end customer