
All-time tech highs, AI everywhere, data centers full. And in the middle of it all, a British company that is quietly making money from the fact that almost every chip in the world licenses its architecture. I try to separate hype from reality.
What ARM really does and why it is structurally strong
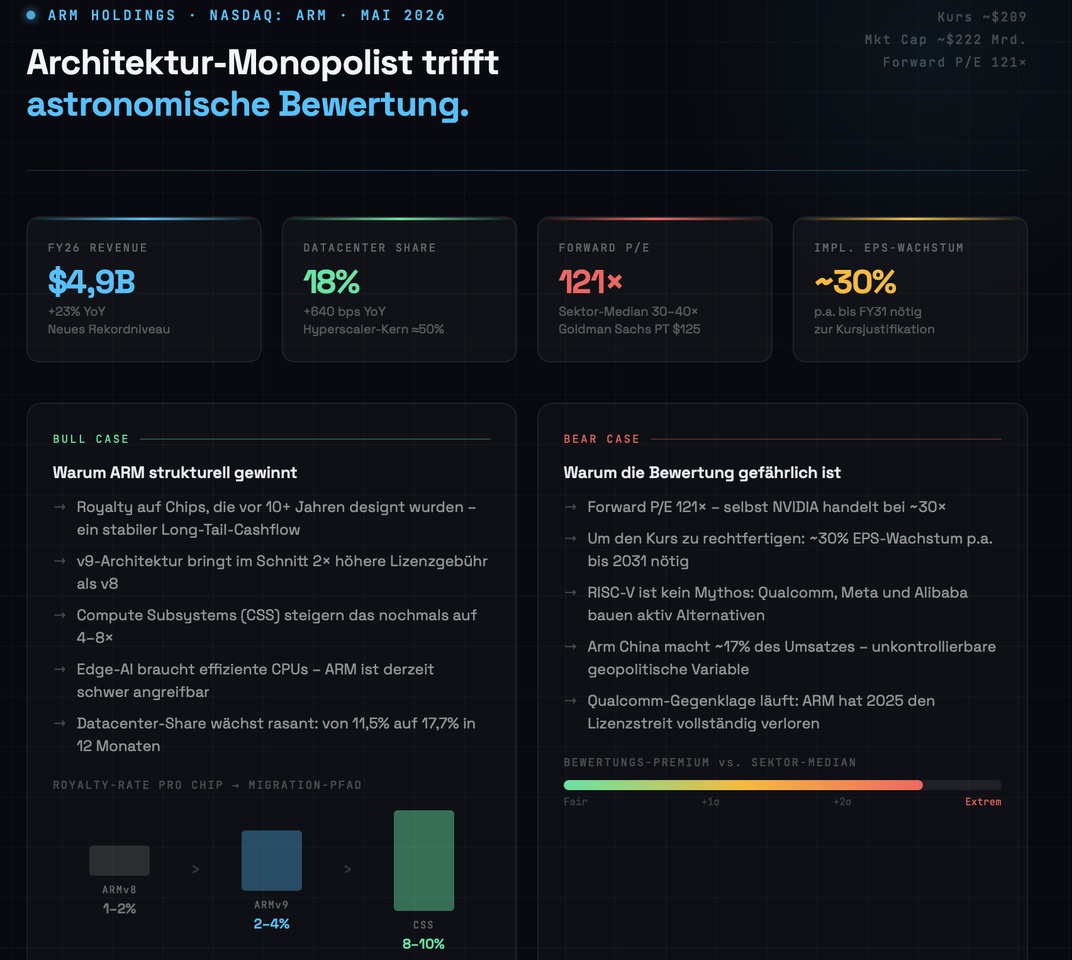
ARM does not sell chips. ARM sells the right to build chips according to its blueprint. And the company still earns money from designs that were developed over 10 years ago.
The new generation is called v9 and the average license price per chip is twice as high as for the previous architecture. If you go one step further and use ARM's complete compute platform (CSS), you pay up to eight times more. Every new chip produced worldwide is a small royalty ticket for ARM.
There is also a structural tailwind: Edge AI shifts computing power from the data center to devices. Smartphones, laptops, cars. ARM is currently involved in practically all relevant designs. In the data center, ARM's market share grew from 11.5 to 17.7 percent in twelve months.
That's a real story.
The problem: the valuation leaves no room for error
ARM is currently trading at 121 times expected earnings. By comparison, NVIDIA trades at around 30 times. These are not slightly different expectations. That's a different league.
To justify the current share price, ARM would have to increase profits by around 30 percent every year until 2031. If this is actually achieved, the current share price may even be cheap. If it doesn't, a multiple compression will follow that will hurt.
Analysts' opinions range between 125 and 300 dollars target price for the same company. That is not a consensus. This is a dispute of faith.
What I have on the screen
RISC-V is not a myth. Qualcomm, Meta and Alibaba are actively building alternatives to ARM licensing. Not a real problem for ARM's core market today, but a signal I'm watching.
In addition, around 17 percent of sales come from Arm China, a unit that neither ARM nor SoftBank controls. In an increasingly fragile geopolitical environment, that's a variable I don't underestimate.
My personal classification
ARM is one of the most fascinating companies in the current tech landscape. The business model is elegant, the structural tailwind is real, the market position is strong.
But the market is already pricing in this success extremely aggressively. Anyone buying today is not betting on a good company. They are betting that a good company will deliver for the next five years in a row without a single major setback.
For me, that is the difference between an exciting share and a sensible purchase at the current price.
Sources: SEC FY26, StockAnalysis, GuruFocus, 24/7 Wall St. (May 2026).
Not investment advice.
Do you have ARM on your radar, and if so: company or hype? 👇
$ARM (+2,36%)
#getquin
#aktien
#halbleiter
#arm
#ki
#technologie
#investieren
#börse
#bewertung
#edgeai


