Hello my dears,
Thank you for the great comments and many 👍 on my posts yesterday.
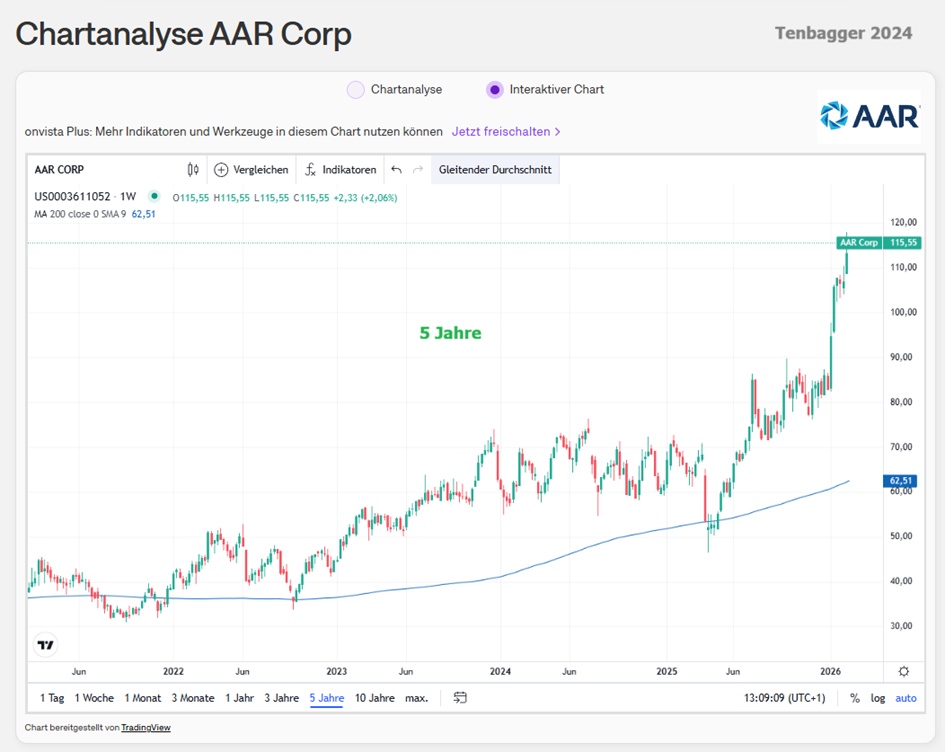
That motivated me, and that's why there's a great company right at the beginning of the week that keeps the planes flying. Or rather, let's say it keeps them flying.
A classic aftermarket specialist.
Today, the company is one of the largest independent MRO and spare parts suppliers worldwide.
For airlines, this means that if a jet has a problem, parts are missing or a major inspection is due, the company is one of the players that can step in - quickly, reliably, worldwide.
An airplane only earns money when it flies. Every minute on the ground costs money.
My dears,
But our company is also clearly a defense player - and not just on the sidelines, but as an established, strategically important partner for the US military and allied forces. Current developments even show that it is actively expanding its defense business. actively expand .
Importance in the defense ecosystem
It is not a classic defense manufacturer like Lockheed or Northrop, but an aftermarket specialist for:
- military spare parts
- repair and maintenance
- logistics infrastructure
- supply chain management
This makes it a critical enabler of military operational readiness - comparable to a highly specialized "maintenance and logistics backbone" for armed forces.
Strategic classification for us investors
The company benefits in the defense sector from
- Stable, long-term government contracts
- high barriers to entry (certifications, trust, track record)
- growing demand for outsourcing in the military MRO sector
- global geopolitical tensions that increase demand for logistics and maintenance services
At the same time, the business remains
- less cyclical than Commercial Aviation
- High-margin in the aftermarket
- politically stable, as DLA and USAF are long-term partners
Dear all, I am of course very interested in your opinion on AAR
$US0003611052 (-0,26%)
As always in the comments.
Aviation service provider increases turnover by 20 % and raises profit margin to 9.6 %!
26.01.2026 at 09 am
AAR Corp [AIR | ISIN US0003611052] is the world's largest independent distributor of aircraft parts for the aviation and defense markets. In addition to the distribution of new parts and the maintenance of aircraft, the company offers a worldwide 24/7 aircraft-on-ground service. It also offers the sale and leasing of used aircraft. Services such as fleet management and the operation of customer-owned aircraft for the US State Department are also provided. The company currently has a market capitalization of USD 4.20 billion.
AAR Corp. is a global aerospace and defense aftermarket solutions company with operations in more than 20 countries. The company supports commercial and government customers through four segments: Parts Supply, Repair & Engineering, Integrated Solutions and Expeditionary Services. The Parts Supply segment primarily includes the sale of used engine and airframe parts and components as well as the sale of new parts. The Repair & Engineering segment primarily comprises the maintenance, repair and overhaul of airframes and components, including landing gear. The Integrated Solutions segment primarily comprises fleet management and the operation of customer-owned aircraft as well as customized, performance-based logistics programs for the supply chain. The Expeditionary Services segment primarily includes products and services that support the transportation of equipment and personnel by the United States and foreign governments and non-governmental organizations.
What is currently driving the share?
The company is benefiting massively from the ageing of global aircraft fleets and the trend towards outsourcing complex maintenance work. As airlines are using their existing aircraft for longer, the demand for spare parts and specialized services is constantly increasing. A new exclusive contract with Pratt & Whitney for the distribution of engine parts secures long-term cash flows. In addition, the recovery in the defense sector and the expansion of capacities in India are driving growth. AAR is leveraging economies of scale to further increase profitability in the current aviation super-cycle.
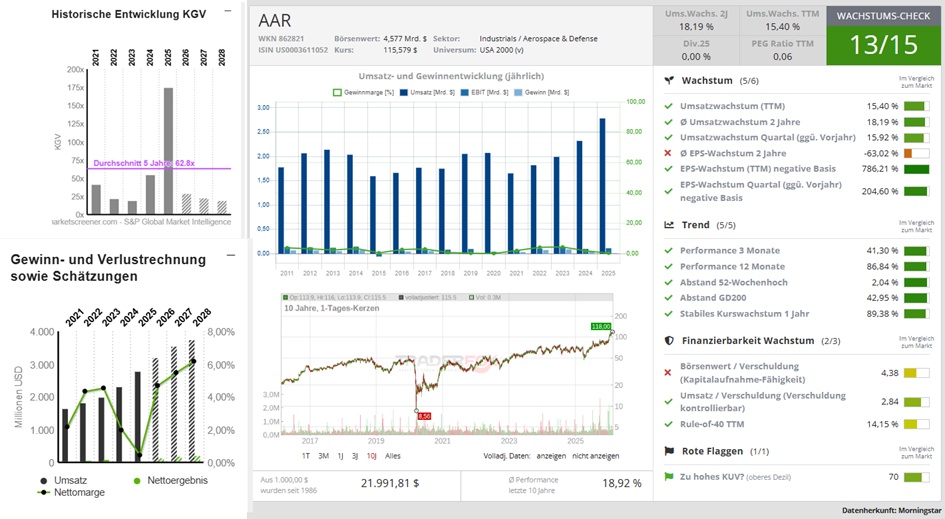
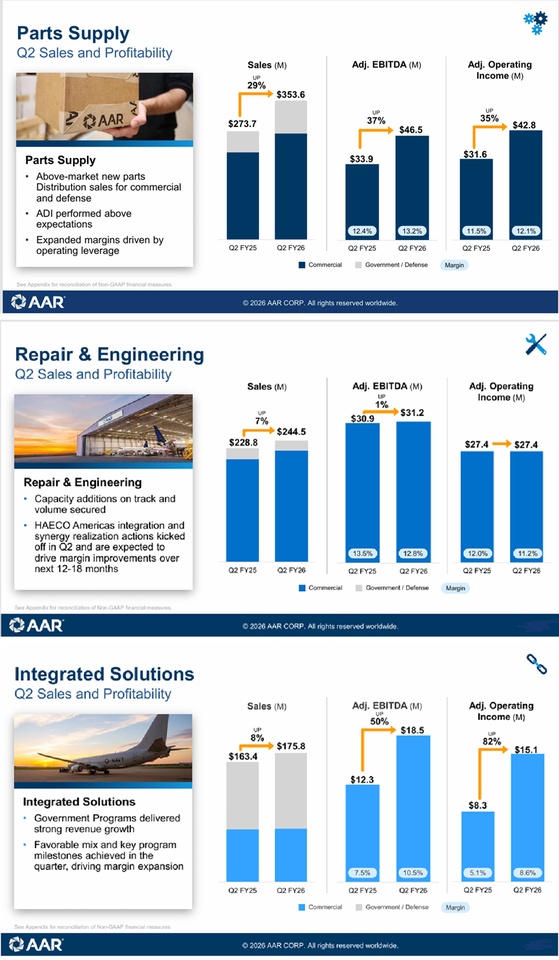
At the beginning of January, the company delivered a strong second quarter with sales up 20% to USD 712 million and adjusted earnings per share of USD 0.89. The Parts Supply segment in particular flourished. The Parts Supply segment in particular flourished thanks to the integration of Triumph Product Support, which lifted the operating margin to a record level of 9.6%. The company is benefiting greatly from economies of scale: The global footprint (over 20 countries) facilitates procurement. The management explicitly names New Parts Distribution and Trax as high-margin growth areas. Trax is an enterprise software platform for technical airline operations (MRO/engineering). It is used by airlines, MROs and leasing companies to manage maintenance, airworthiness and technical processes end-to-end. Trax has been part of AAR Corp since 2016, and with the acquisition of HAECO Americas, the company has not only secured valuable capacity in the booming airframe heavy maintenance sector, but has also attracted massive capacity utilization and efficiency leverage: The acquisition brought in new contracts worth around USD 850 million, which will fully utilize the sites in Greensboro and Lake City (North Carolina/Florida) for the coming years. The share currently scores 13 out of 15 points in the TraderFox growth check.
Q2 highlights
- Sales growth in all segments Achieved above-market growth in new parts sales Expanded operating margins
- Portfolio strengthened by two acquisitions
- ADI accelerates growth in new parts sales
- HAECO Americas expands capacity for comprehensive maintenance and secures long-term contracts
- Renewed exclusive new parts distribution agreements with Collins and Arkwin. Achieved new business success with Trax and further expanded digital capabilities
- Reduced leverage and maintained strategic flexibility through proactive balance sheet management
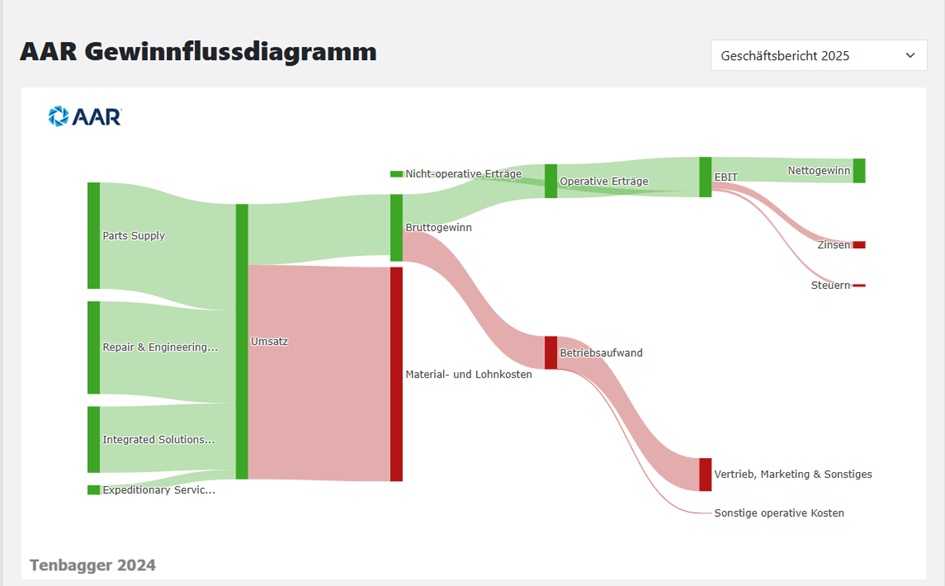
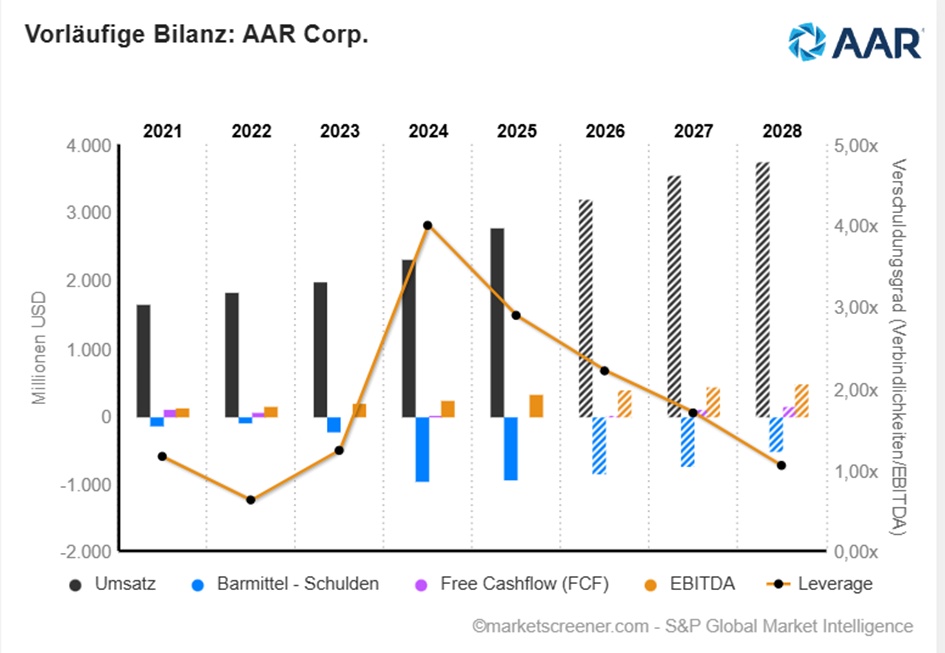
USD in millions
Estimates
Year Turnover Change
2024 2.319 16,5 %
2025 2.780 19,91 %
2026 3.212 15,53 %
2027 3.549 10,49 %
2028 3.762 6,01 %
Year EBIT Change
2024 129,2 -3,51 %
2025 185,2 43,34 %
2026 312,8 68,88 %
2027 358,2 14,53 %
2028 396,5 10,7 %
Year Net result Change
2024 46,3 -48,67 %
2025 12,5 -73 %
2026 151 1.108,08 %
2027 194,2 28,62 %
2028 233 19,96 %
Year Net debt CAPEX
2024 970 29,7
2025 938 34,7
2026 857 36,9
2027 744 39,18
2028 508 44,85
Year Free cash flow Change
2024 13,9 324,19 %
2025 1,4 -89,93 %
2026 21,82 1.458,57 %
2027 102,8 371,13 %
2028 143,5 39,59 %
Year EBITDA margin EBIT margin
2024 10,45 % 5,57 %
2025 11,66 % 6,66 %
2026 12,03 % 9,74 %
2027 12,29 % 10,09 %
2028 12,89 % 10,54 %
Year Earnings per share Change
2024 1,29 -49,01 %
2025 0,35 -72,87 %
2026 3,99 1.040 %
2027 4,937 23,73 %
2028 5,83 18,1 %
Year P/E ratio PEG
2024 55x -1.1x
2025 175x 1.8x
2026 29x 0x
2027 23.4x 1x
2028 19.8x 1.1x
Market value 4,511
Number of shares (in thousands) 39,037
Date of publication 16,07,2025
Performance
1 week +2.06 %
1 month +9.96 %
6 months +56.47 %
1 year +79.73 %