My dears, I remain invested.
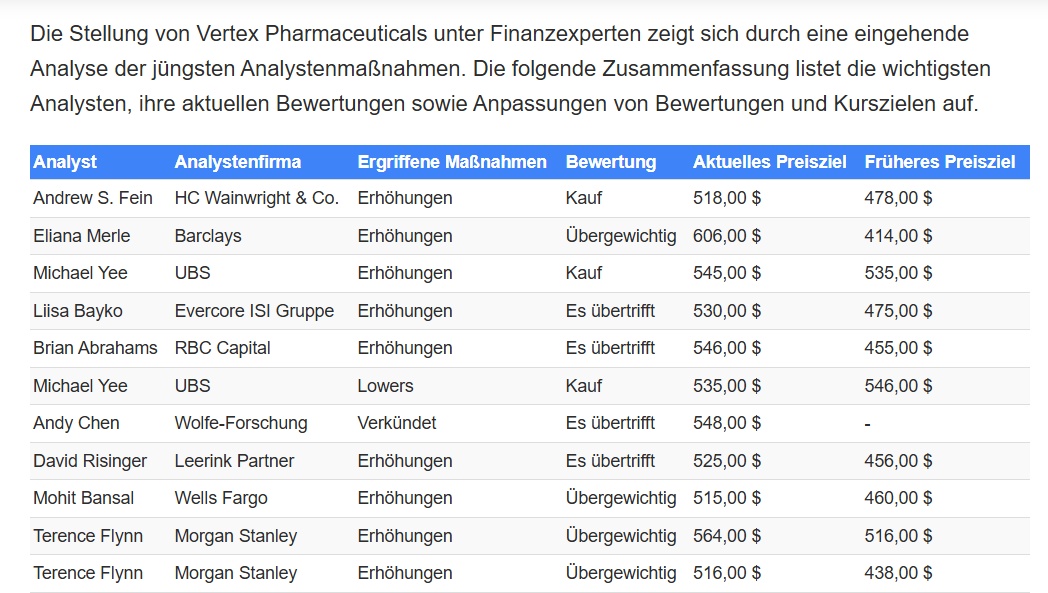
Oppenheimer downgrades Vertex (VRTX) from Perform to Outperform up and sets a price target of USD 540 - around +16 % above the current share price.
The main reason is the strong potential of the kidney pipelineespecially the candidates Povetacizt and inaxaplinewhich are potential blockbusters are seen as potential blockbusters.
These could become a dominant nephrology franchise and diversify Vertex more diversify Vertex beyond its core CF business.
Vertex continues to demonstrate solid fundamentals:
- Sales growth over the last 12 months: +10,33 %
- Total sales: USD 11.72 billion
- Diluted EPS (12 months): USD 14.22
Oppenheimer sees no short-term risks for the CF franchise (exclusivity, competition).
Additional potential: diabetic peripheral neuropathy (DPN).
Unveiling the story behind Vertex Pharmaceuticals
Vertex Pharmaceuticals is a global biotechnology company that discovers and develops small molecule drugs to treat serious diseases. Key drugs include Kalydeco, Orkambi, Symdeko, Trikafta/Kaftrio and Alyftrek in cystic fibrosis, with Vertex therapies continuing to be standard of care worldwide. Vertex has diversified its portfolio with Casgevy, a gene editing therapy for beta-thalassemia and sickle cell anemia, and Journavx, a non-opioid analgesic approved for the treatment of moderate to severe acute pain in adults. In addition, Vertex is evaluating small molecule inhibitors of APOL1-mediated kidney disease. Vertex is also investigating cell therapies to provide a potential functional cure for type 1 diabetes.
My dears, what would a cure for type 1 diabetes mean for Novo?
Net Margin: Vertex Pharmaceuticals' financial strength is reflected in its exceptional net margin, which exceeds industry averages. With a remarkable net margin of 35,2 % the company demonstrates strong profitability and effective cost management.
Debt management: The debt ratio is below industry norms and indicates a solid financial structure with a ratio of 0,11 ratio.