4Mês·

Additional Purchase of Global Payments

Global Payments $GPN (-0,27%) is currently not for the faint of heart, but fundamentally a highly attractive deep-value play. The market is currently acting as if the company were on the verge of bankruptcy, yet it ignores the stable cash flows and the operating margin of nearly 40%.


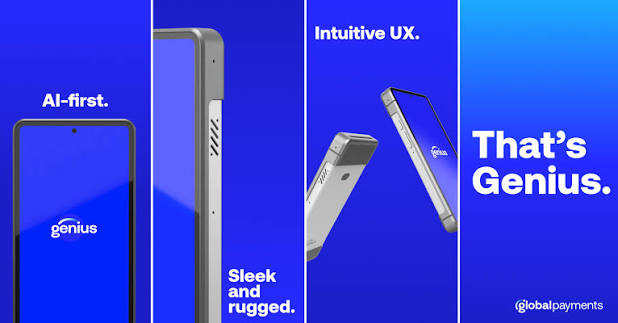
The merger with Worldpay offers enormous cross-selling potential (Genius POS for Worldpay customers). I believe the synergies will start to show up in earnings by 2027.


Looking at the institutional order book (Level 2/3), there are massive buy walls in the range of USD 60–63. The POC is significantly higher at around USD 78. Since I was already invested and remain convinced of the company’s prospects, I took advantage of the current price to buy more shares.
attachment
10.06
Global Payments logo
Comprado x100 em US$ 64,00
US$ 6.400,00
5
6 Comentários

imagem de perfil
I've seen this before. However, it's currently in a classic long-term downtrend. Of course, one can hope for a bottom to form around the high-volume levels. But I think the money would be better invested elsewhere.
••
imagem de perfil
...is likely to decline over the long term; there are currently much more technologically advanced players in the enterprise sector (e.g., Nuvei) that are currently poaching most of the blue-chip clients from other PSPs.
••
imagem de perfil
@TechNerd1337 First of all, Nuvei hasn't been publicly traded for a long time, so I don't understand this point.
And secondly, I'm sticking with my three payment processors: Global Payments, Block, and PayPal.
There will always be someone leading the pack in a particular sector.
But as with the Nuvei example, you can still get kicked out with the mandatory cash settlement.
••
imagem de perfil
@7Trader What I mean is that the outlook for GPN in the PSP sector isn't looking very bright overall. On the one hand, because of players like Nuvei; on the other, because PSP tech has simply become unattractive in the age of AI, and there are more modern players who will gain an edge in agent transactions.
GPN is sitting on a mountain of debt due to the merger, and in an industry with hungry fintech competitors, that makes it a pretty risky stock.
The coming years will be tough for PSPs as volumes shift away from high-margin payment methods toward new, low-margin ones—it’s generally a difficult situation.

I spent years in top management at one of the larger PSPs—so I’m staying away from stocks in that sector ;)
••
imagem de perfil
@TechNerd1337 I’m counting on the market leaders with established business models (PayPal, Block, GPN). They still dominate the market and the physical POS. New fintechs have massive barriers to entry to overcome. And the old giants will continue to evolve. When in doubt, the established players simply buy up the innovation (just as Global Payments constantly does).

By the way, did you happen to visit Wirecard?
••
imagem de perfil
@7Trader Well, that’s also reflected in the PayPal chart. Market dominance no longer pays off on the stock market in this sector.

Wirecard? No. I sold my stake in Nuvei many years ago.
••
Participar na conversa