The next stock I want to talk about is Netflix. I’ll be honest, I still have a hard time buying this stock and for a very simple reason: anchoring bias.
I bought Netflix in mid-2022 in the low $200s and sold way too early. And I mean way too early. At the time, the business genuinely didn’t look great. Subscriber numbers were declining, sentiment was awful, and the stock was getting punished. But my reasoning back then was embarrassingly simple. It was one of the first stocks I ever bought, and I thought, “Netflix is clearly better than Amazon Prime and Disney+, so it’s probably going to come back.” Turns out, I was very right. I just didn’t stick around long enough. I sold somewhere in the mid-$300s.
Ever since then, I couldn’t look at Netflix objectively again. I didn’t assess it based on its current market position or fundamentals. I looked at it through the lens of the price I could have owned it at a few years ago. The exact same thing happened to me with Meta for a while. I bought in 2022, sold too early, and then stayed on the sidelines because I was fixated on the old price.
The mistake was obvious in hindsight. I was focusing on price instead of business quality. The stocks were cheap back then for a reason, because both companies were struggling. Once I managed to rewire my brain, the picture became clear. Netflix today is in a far better position than it was in 2022. Honestly, it’s probably multiple times stronger as a business, which is exactly why buying it again actually makes sense.
Netflix commands roughly 20% of the global streaming market and remains the dominant force in the industry. But management is not satisfied with that. With the proposed acquisition of Warner Bros and HBO Max, Netflix’s market share could move north of 30%. Whether or not the FTC allows that deal to go through is not central to my investment case. Yes, I would love to see Game of Thrones on Netflix, both personally and from a business standpoint, but even without the acquisition, Netflix is attractive at current levels.
In fact, the situation might even tilt in Netflix’s favor. Its main competitor in the process, Paramount Skydance, led by David Ellison, likely cannot stomach a transaction of this size. Netflix, on the other hand, can simply raise prices by a few dollars and earn the cost back over time. That pricing power is immense and still underestimated.
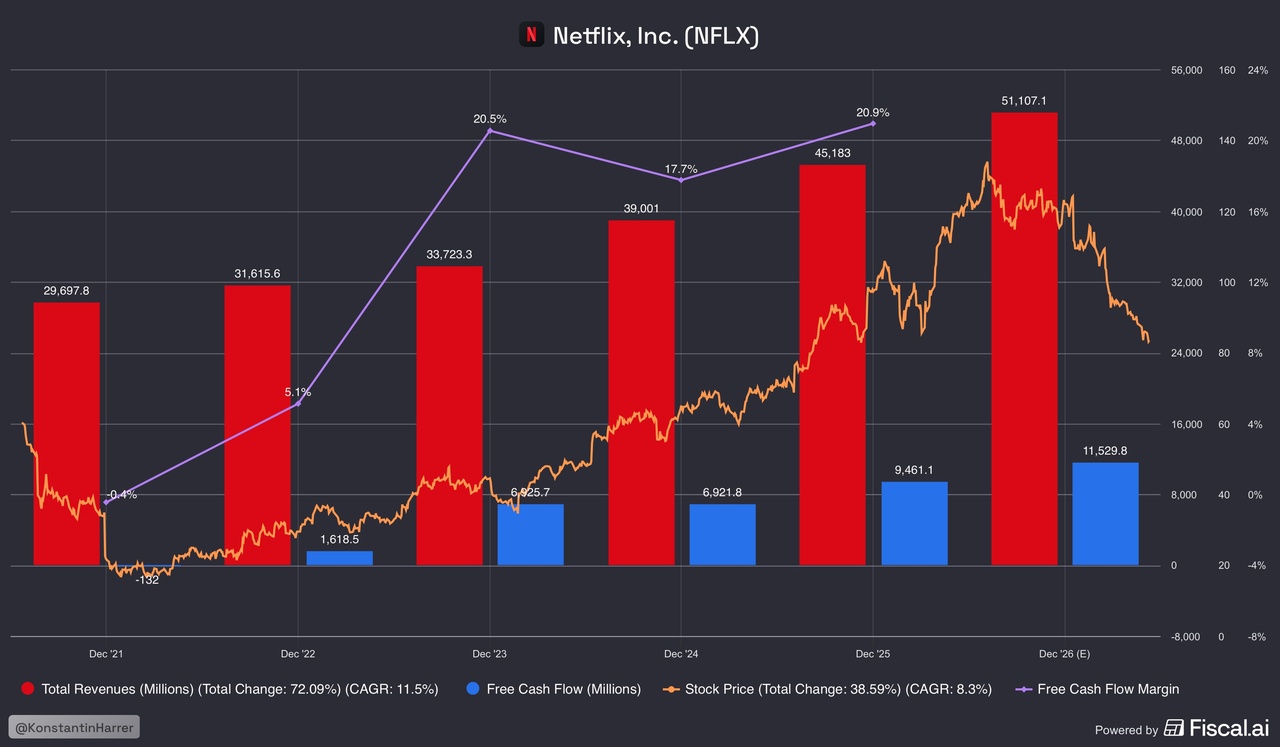
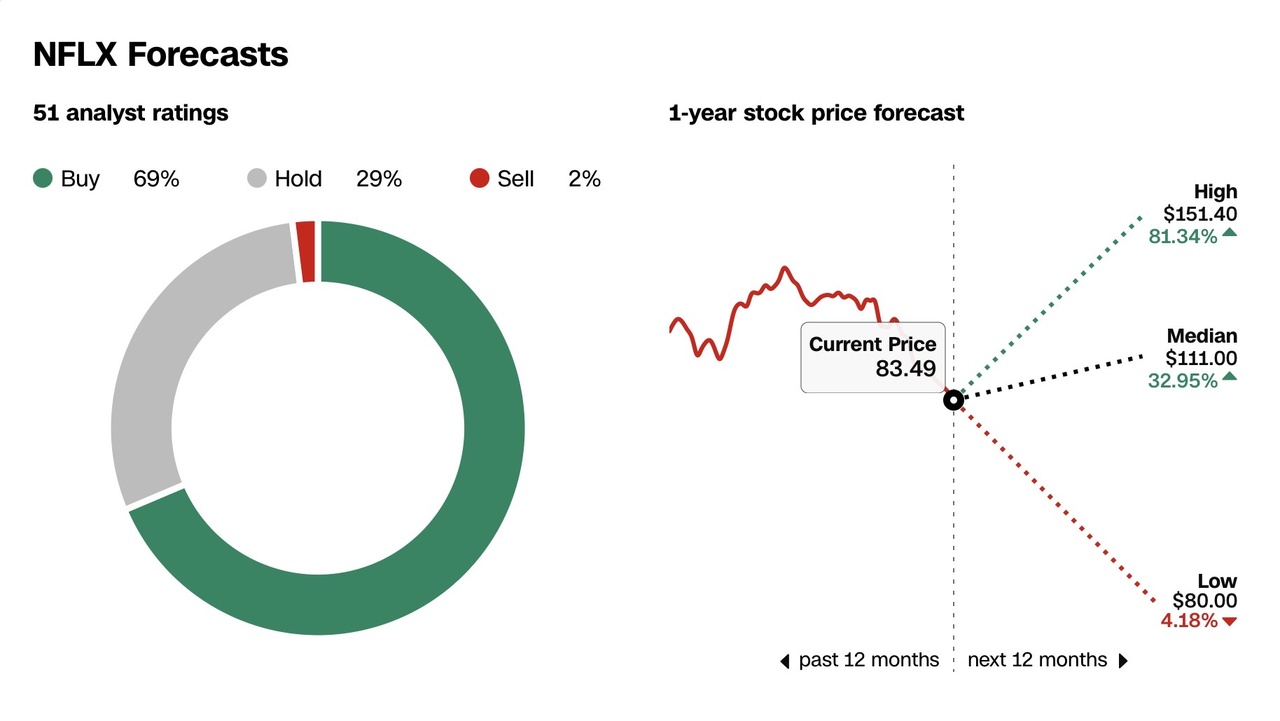
Revenue is projected to grow in the mid-teens regardless of whether the acquisition goes through. Free cash flow is expected to grow in the mid-20% range. The stock is currently trading in the mid-$80s, at a forward P/E of around 27, dropping to roughly 18 on FY28 earnings. The free cash flow yield sits near all-time highs at about 3.2% on current numbers and close to 5% on FY28 estimates. And given Netflix’s pricing power, those numbers could still improve.
No matter how the Warner Bros situation plays out, I’m bullish on Netflix. I recently added to my position, my average entry price is around $90, and the stock now represents roughly 4–5% of my portfolio. On future dips, I’d happily buy more. I see no good reason why the stock shouldn’t rebound from here.