

Hello, everyone,
Today I’d like to introduce you to an AI profit-maker from a field where many of you wouldn’t expect to find one.
I’m really curious to hear your thoughts—and those of the prompts.
LandBridge is transforming its land in Texas into a cash flow machine for the age of artificial intelligence!
During the Gold Rush, those who truly became rich were rarely the gold prospectors themselves, but rather the people who owned the land where the digging took place. LandBridge is applying exactly this principle in Texas’s Permian Basin—except that today, it’s no longer gold being mined, but oil, water, and, increasingly, computing power.
Landholding company in the energy sector launches new service in the data center sector
LandBridge Company (LB) was founded in 2008 and has since established itself as a major player in logistics & transportation as well as resource development (primarily oil and gas). The company was founded with the vision of efficiently utilizing land resources and creating sustainable solutions for industries such as energy, logistics, and real estate. A major milestone was its initial public offering on June 28, 2024. The company is headquartered in Texas.
LandBridge offers a wide range of services designed to meet the needs of the energy and industrial sectors. The company owns over 315,000 acres of land in and around the Delaware Basin in Texas and New Mexico, an active region in the United States for the exploration and production of crude oil and natural gas. Its land holdings span three separate areas: the “Stateline,” “Northern,” and “Southern” areas. The “Stateline Position” comprises approximately 169,000 acres of land, located primarily in Loving, Reeves, and Winkler counties in Texas, as well as in Lea County in New Mexico, near and along the state line between Texas and New Mexico. The “Northern Position” comprises land in Eddy and Lea counties in New Mexico and in Andrews County in Texas, consisting of approximately 61,000 acres of land plus an additional 33,000 acres of land. The Southern Area comprises approximately 87,000 acres in Reeves, Ward, and Pecos counties in Texas within the Delaware Basin.
In addition to energy projects, the company also supports other commercial and industrial developments on its lands, including solar power generation, data centers, and waste disposal facilities.
Its main competitors include companies such as Cushman & Wakefield, a global real estate services provider that offers similar land management and consulting services, as well as CBRE, which also operates in the commercial real estate and infrastructure sectors. Another notable competitor is Texas Pacific Land Corporation (TPL), a publicly traded Texas-based company that also owns and manages significant tracts of land in the Permian Basin.
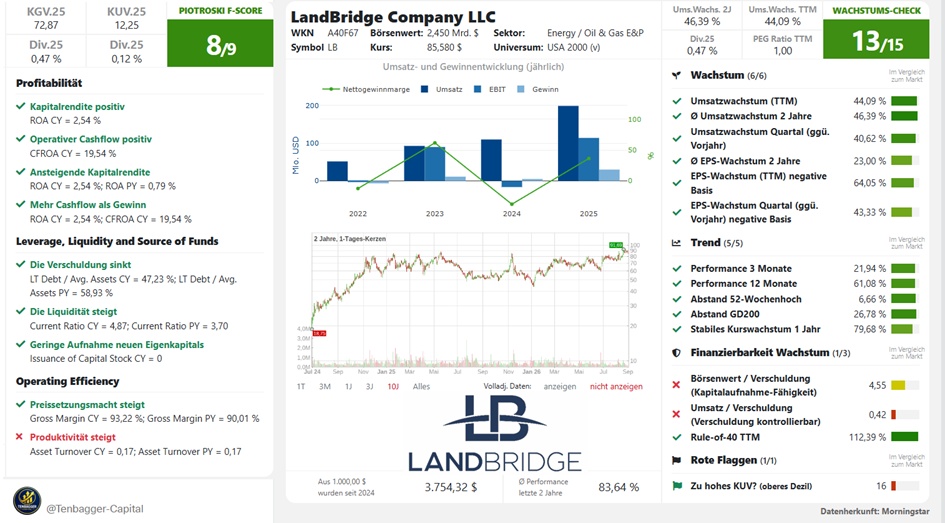
LandBridge is transitioning from a pure landowner to a multi-asset play: Energy + Solar + Data Center Infrastructure. The market is focusing on → relative strength.
🔥 LandBridge 2026 – The True Significance of the Solar and Data Center Deals
1) Western Midstream + DESRI → LandBridge Becomes an Energy Infrastructure Player
The agreements with Western Midstream Partners LP and DESRI are not just “any old projects.” They mark a strategic repositioning for the company.
What Western Midstream Means
Western Midstream is one of the largest midstream players in the Permian Basin. When LandBridge enters into contracts with them, it means:
- LandBridge becomes part of the pipeline and infrastructure value chain
- Land rights will be monetized on a long-term basis
- This generates long-term, recurring cash flows
- LandBridge becomes indispensable
This is a classic “moat builder.”
What DESRI stands for
DESRI is a leading developer of renewable energy projects. The deal for 26,000 hectares of solar land is:
- enormous (comparable solar farms range from 500 to 2,000 hectares)
- a decade-long cash flow driver
- a ESG boostthat attracts institutional investors
- a second business model in addition to oil & gas
Interpretation: LandBridge is becoming an energy landlordthat allows both fossil fuel and renewable energy infrastructure on its land—and profits from it.
2) Entry into data centers → the game-changer for valuation
The first lease agreement in the data center market + an $8 million down payment is the development that’s electrifying Wall Street.
Why?
Data centers need exactly what LandBridge has:
- huge, contiguous tracts of land
- power connections
- water rights
- proximity to pipelines
- political stability (Texas/New Mexico)
- Low regulatory barriers
LandBridge has all of this—and in monopoly-quality form.
What the $8 million down payment really means
This isn’t a small pilot project. It’s a commitment from a major playerthat recognizes LandBridge as a location for AI and cloud infrastructure.
This opens up three new revenue streams:
Land leases for data centers
Energy leases (solar + gas)
Infrastructure leases (water, cooling, utilities)
This is a completely new business model with extremely high margins.
3) Why These Two Topics Will Dominate the Narrative in 2026
Wall Street loves companies that:
- own monopoly-like assets own
- capitalize on multiple megatrends simultaneously capitalize on
- build scalable, recurring cash flows build
- non-cyclical are
- AI exposure have
- Energy exposure have
LandBridge will meet all six criteria by 2026 all six criteria.
That’s why the stock is strong.
That’s why the consolidation is bullish.
That’s why LandBridge will be valued differently in 2026 than in 2024/2025.
🎯 Key Takeaway
LandBridge will no longer be an oil-and-gas landowner by 2026.
It is a multi-asset infrastructure company that simultaneously monetizes solar, midstream, and data centers.
The two deals + the entry into data centers are the strategic transformationthat will reshape its valuation in the long term.
Financial Results for the Second Quarter of 2026
- Revenue of $66.8 million, representing a 41% increase year-over-year and a 31% increase quarter-over-quarter
- Net income of $31.0 million, representing a 68% increase year-over-year and a 74% increase quarter-over-quarter, with a net profit margin of 46%
- Adjusted EBITDA(1) of $59.8 million, representing a 41% increase year-over-year and a 33% increase quarter-over-quarter, and an adjusted EBITDA margin(1) of 89%
- Cash flow from operating activities of $41.4 million, representing an increase of 11% year-over-year and 1% quarter-over-quarter
- Free cash flow(1) of $40.2 million, representing an 11% increase year-over-year
- Operating cash flow margin of 62%; free cash flow margin(1) of 6
- Announced quarterly cash dividend of $0.12 per share
Recent Highlights
- LandBridge continues to see growing and accelerating momentum in its West Texas digital infrastructure thesis:
- LandBridge is currently in LOI, option, or final-stage negotiations with 7 power and digital infrastructure partners, representing a potential of over 10 GW of power generation. Execution of an agreement to acquire 560 acres of property beneath the Northern Delaware Basin landfill in Lea County, New Mexico, for a total of $20 million. The transaction is expected to close in the third quarter of 2026.
- 1) Announcement that the Board of Directors has unanimously approved the conversion and relocation of the company from a Delaware limited liability company to a Texas corporation, following the positive recommendation of the previously announced special committee of independent directors.
LandBridge Aktie auf Rekordhoch: Barron’s-Bericht und Umstrukturierung beflügeln Kurs
- Investing.com
- Aug. 20, 2026
According to an experienced investor, LandBridge could become one of the most attractive vehicles for a concentrated exposure to the U.S. energy sector. The company combines strategically located midstream infrastructure with significant land holdings and a debt-free balance sheet
Earnings Call: LandBridge meldet Rekordumsatz für Q2 2026 – Aktie legt um 4,7 % zu
- Investing.com
- Aug. 6, 2026
August 5, 2026, at 4:10 p.m.
LandBridge gibt Ergebnisse des zweiten Quartals 2026 bekannt
April 2, 2026, at 8:30 a.m.
🔎 Performance at a Glance – LandBridge Company LLC
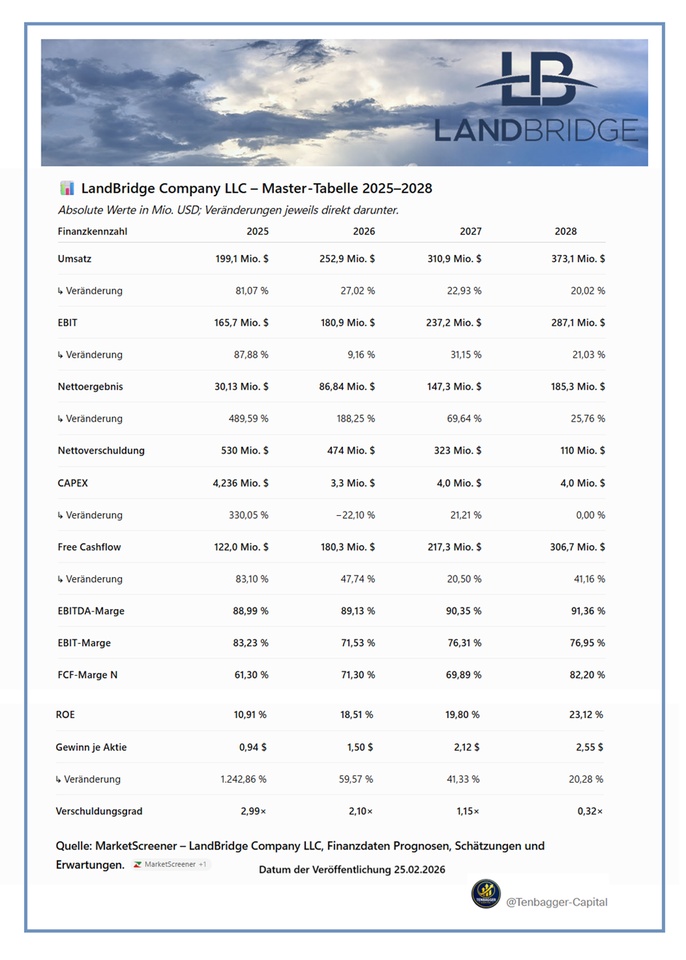
Revenue:
199.1 → 252.9 → 310.9 → $373.1 million
➡️ Continuous growth of approximately 20–27% per year.
EBIT:
165.7 → 180.9 → 237.2 → $287.1 million
➡️ Following a more moderate increase in 2026, EBIT growth will accelerate significantly again.
Net income:
30.13 → 86.84 → 147.3 → $185.3 million
➡️ massive jump in profits over the entire period.
Free cash flow:
122.0 → 180.3 → 217.3 → $306.7 million
➡️ Particularly strong: FCF is growing faster than revenue and will reach an exceptionally high level by 2028.
Net debt:
530 → 474 → 323 → $110 million
➡️ Debt reduction of approximately 79% by 2028.
Debt-to-equity ratio:
2.99× → 2.10× → 1.15× → 0.32×
➡️ This is expected to improve dramatically.
FCF margin:
61.30% → 71.30% → 69.89% → 82.20%
➡️ Extremely high cash flow generation.
ROE:
10.91% → 18.51% → 19.80% → 23.12%
➡️ The expected return on equity is rising steadily.
⭐ My overall assessment
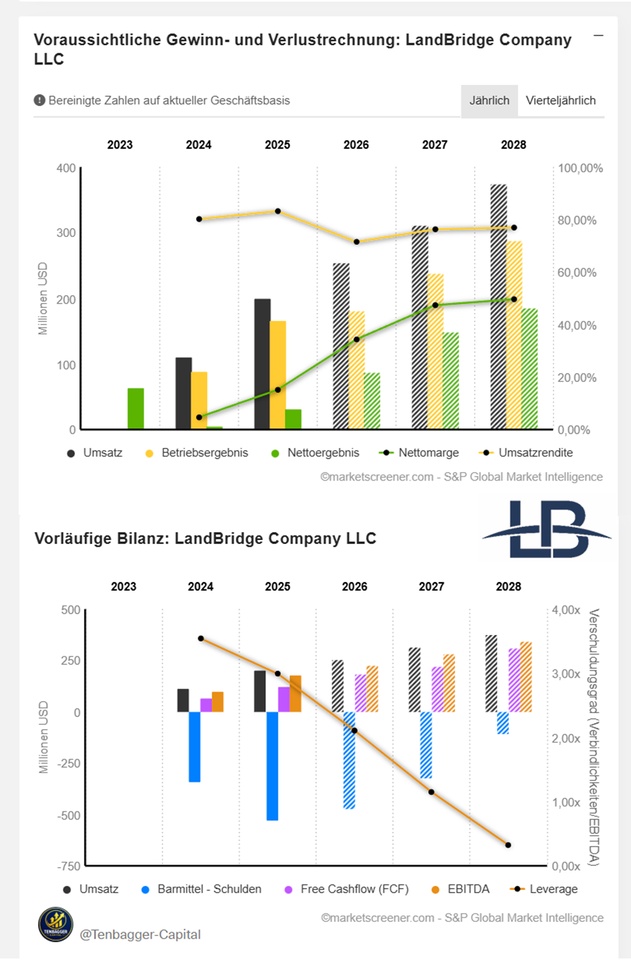
In the MarketScreener forecasts, LandBridge shows a very strong combination of growth + cash flow + debt reduction:
📈 Revenue is growing
📈 Profits are growing strongly
💰 FCF is rising at an exceptional rate
📉 Net debt falls sharply
📉 Debt-to-equity ratio drops from 2.99× to 0.32×
📈 ROE rises to over 23%
The key point: The story isn’t driven solely by revenue growth. At the same time, cash flow generation is expected to increase massively, and debt is set to virtually disappear. This makes the outlook through 2028 fundamentally very interesting.
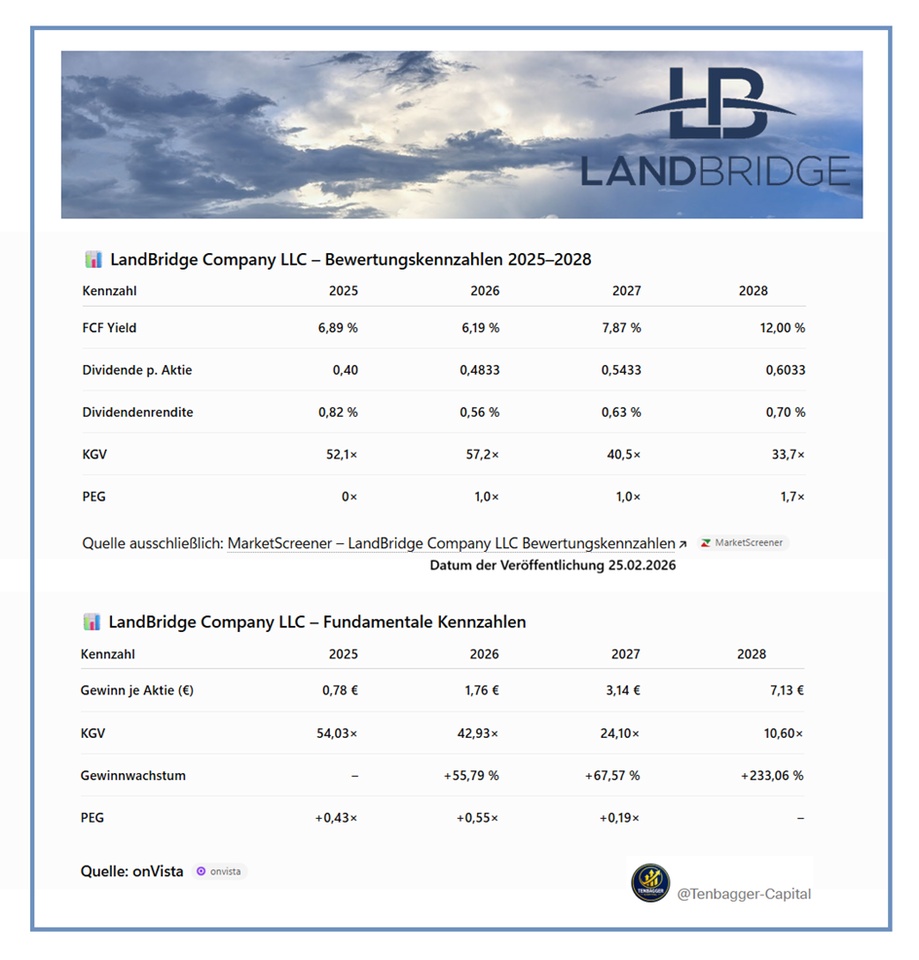
🔎 Performance (Source: onVista)
EPS: €0.78 → €7.13
P/E ratio: 54.03× → 10.60×
Earnings growth: up to +233.06% in 2028
PEG: 2027 at 0.19× particularly low.
Based on these onVista figures, the trend is therefore is very strong: Earnings per share are rising sharply, while the P/E ratio is falling significantly at the same time.
Note: onVista may update its estimates on an ongoing basis. Your table therefore corresponds exactly to the screenshot you provided.
🔎 Performance at a Glance (Source: Market Screener)
- FCF Yield: 6.89% → 12.00% → very significant improvement.
- Dividend per share: 0.40 → 0.6033 → steady growth.
- P/E ratio: 52.1× → 57.2× → 40.5× → 33.7× → Valuation is becoming more attractive despite rising profits.
- PEG: 0× → 1.0× → 1.0× → 1.7×.
- Dividend yield: remains at 0.56–0.82% .
Quick summary: What stands out about LandBridge is the combination of rising FCF yield and a significantly falling P/E ratio through 2028 is particularly interesting. However, even in 2028, the stock will still be 33.7× earnings .
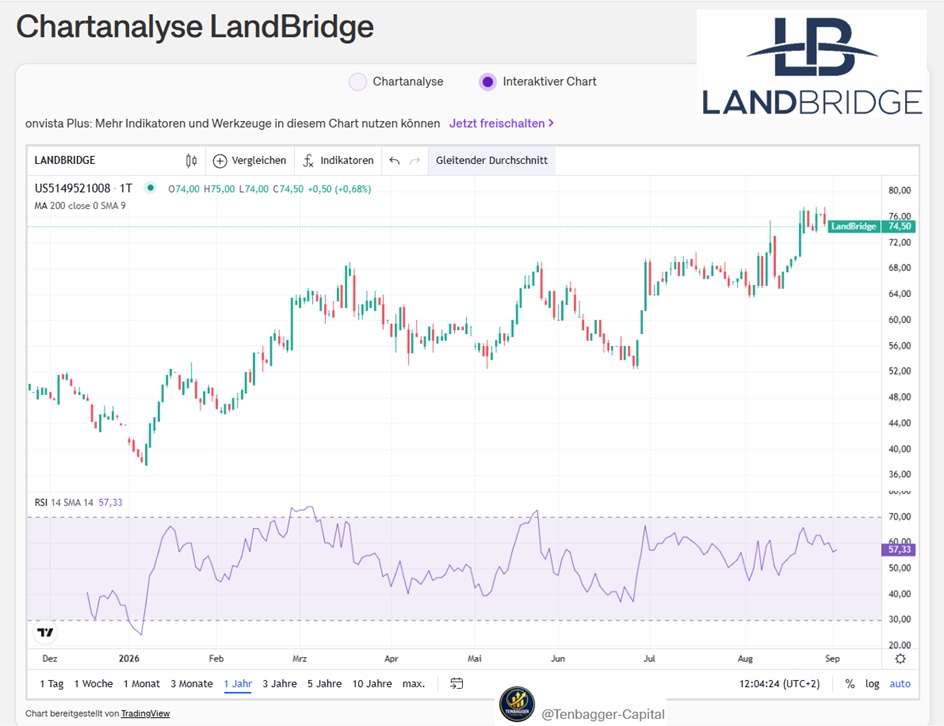
September 2, 2026 1:13:52 PM •
gettex (EUR)
74.50 EUR


