
PSA: Since I don’t really have the time—and, to be honest, the motivation (except for the introduction and some formatting)—here’s the result of my research so far, compiled and summarized with the help of AI. In the slides I created, the debt-to-EBITDA ratio is still listed as 0.3; following the acquisition of Patagonia, it has provisionally risen to approximately 1.06. I hope this analysis is still of interest to those who are interested in companies and markets of this kind. I’m not quite done analyzing the company myself and haven’t invested (yet), but it looks very likely that I’ll open a position. Of course, this isn’t investment advice—there are better ways to burn through your money, like a visit to a beer garden.
Now we’ll finally get to what I recently came across and that will likely make its way into my portfolio sooner or later. The role I’m hoping this will play is that of an EM quality play in the energy sector—the largest private energy producer in its home country, with a (more than) solid balance sheet and a surprising focus and diversification.
I’m talking about none other than Central Puerto S.A. $CEPU (+2,84%) The stock is traded either on its home exchange or via the U.S. ADR, which is linked here. I’ve been digging into it for a few hours now and would like to briefly introduce the company to you. Since I find it very exciting—and given that it’s already more than profitable—I’d say the outlook, management’s approach, and the execution of their plans deserve some due diligence 📈
Executive Summary - Central Puerto S.A. $CEPU (+2,84%)
Central Puerto is a high-quality infrastructure company operating in one of the world’s historically least trustworthy investment regions.
The investment opportunity depends does not on Argentina becoming a developed economy.
Instead, it is based on three assumptions:
- Central Puerto continues to deploy capital intelligently.
- Argentina continues its gradual macroeconomic normalization.
- The market is slowly narrowing the country’s structural valuation discount.
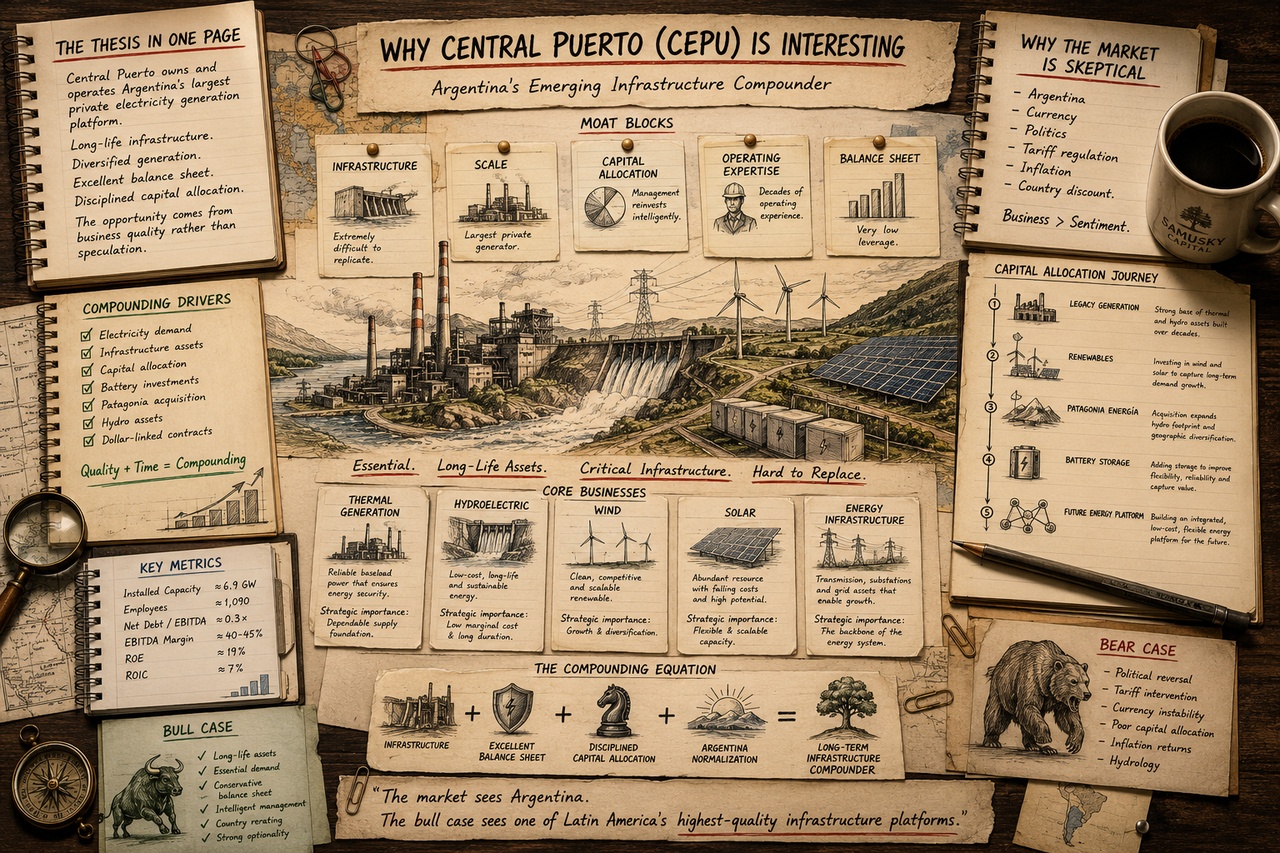
Unlike many investments in emerging markets, the company itself appears fundamentally much stronger than its home country’s reputation.
Business Model -> Argentina’s largest private electricity generator
Sector -> Independent Power Producer (IPP)
Generation mix -> Thermal • Hydroelectric • Wind • Solar
Growth platforms -> Battery storage • Natural gas • Forestry • Energy infrastructure
Installed capacity -> approx. 6.9 GW
Employees -> approx. 1,090
Market Capitalization -> approx. 2–2.5 billion U.S. dollars
Investment Thesis:
The market currently views $CEPU (+2,84%) the company primarily as an Argentine utility.
We increasingly view the company as:
A disciplined infrastructure capital allocator operating in Argentina.
It is precisely this distinction that forms the core of the investment thesis.
Long-term shareholder returns could come from three independent sources:
Organic earnings growth.
Smart reinvestment of generated cash flows.
A gradual decline in the Argentine country risk premium.
Why do we like this company?
Infrastructure
Demand for electricity remains essential regardless of the economic cycle.
Long-Lived Assets
Power plants generate stable cash flows over decades. Replacement costs are extremely high.
Diversified Power Generation
The company is not dependent on a single technology.
- Thermal Power Plants
- Hydropower
- Wind power
- Solar energy
- Battery storage
Conservative Balance Sheet
Even after the acquisition of Patagonia Energía, the ratio of net financial debt to EBITDA is estimated to be only 1.0–1.1× and thus remains conservative for a capital-intensive infrastructure company.
Management
Management consistently prioritizes reinvesting capital over maximizing short-term distributions.
This approach appears rational as long as these reinvestments generate attractive returns over the long term.
- Financial Overview
- EBITDA margin -> approx. 40–45%
- Operating margin -> over 30%
- Return on Equity (ROE) -> approx. 19%
- Return on Invested Capital (ROIC) -> approx. 7% (normalized estimate)
- Net financial debt / EBITDA -> approx. 1.1×
- Cash Flow Generation & Liquidity -> Strong
- Financial risk -> Rather low
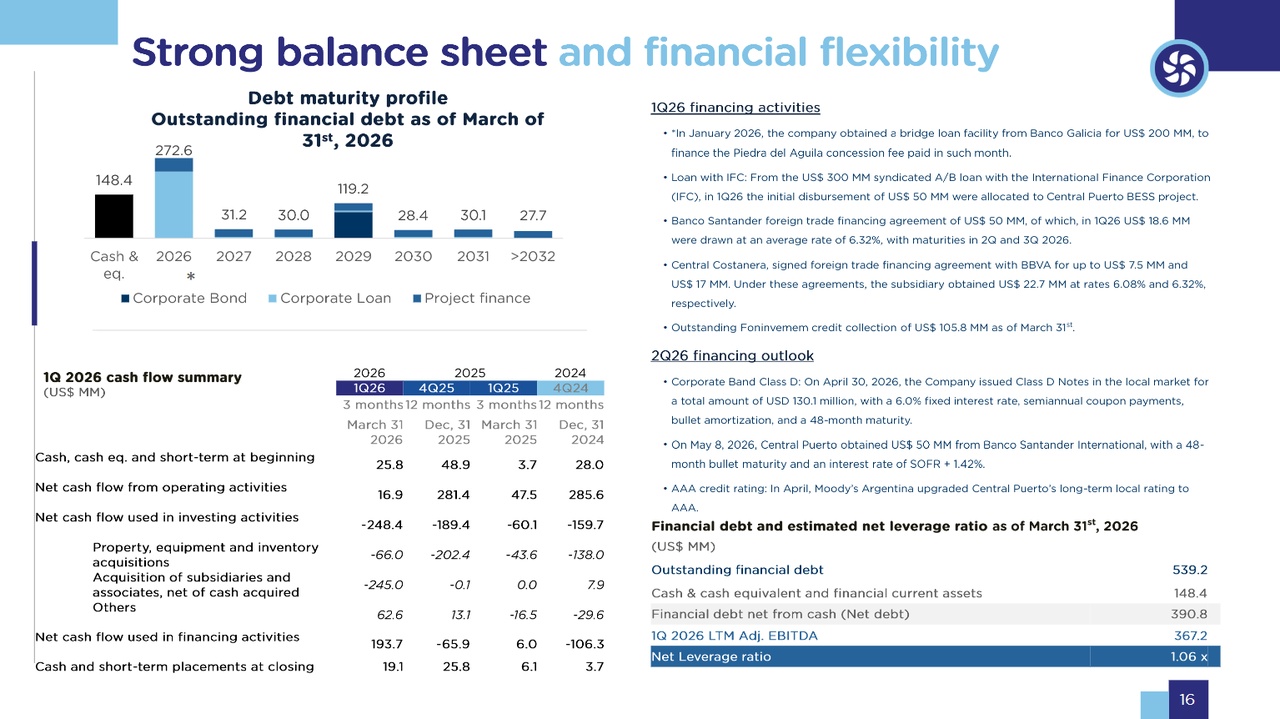
Important Note
ROIC currently appears relatively moderate, as significant funds have been invested in acquisitions and growth projects in recent years.
The key question is therefore:
Will these investments generate attractive returns in the long term?
Capital Allocation
This area is increasingly becoming one of the strongest components of the investment thesis.
Recent investments include:
- Acquisition of Patagonia Energía
- Battery Energy Storage Systems
- Efficiency improvements at existing thermal power plants
- Energy infrastructure
- Development of a forestry platform
Rather than maximizing dividends in the short term, management appears to be focusing on building the company’s future earnings potential.
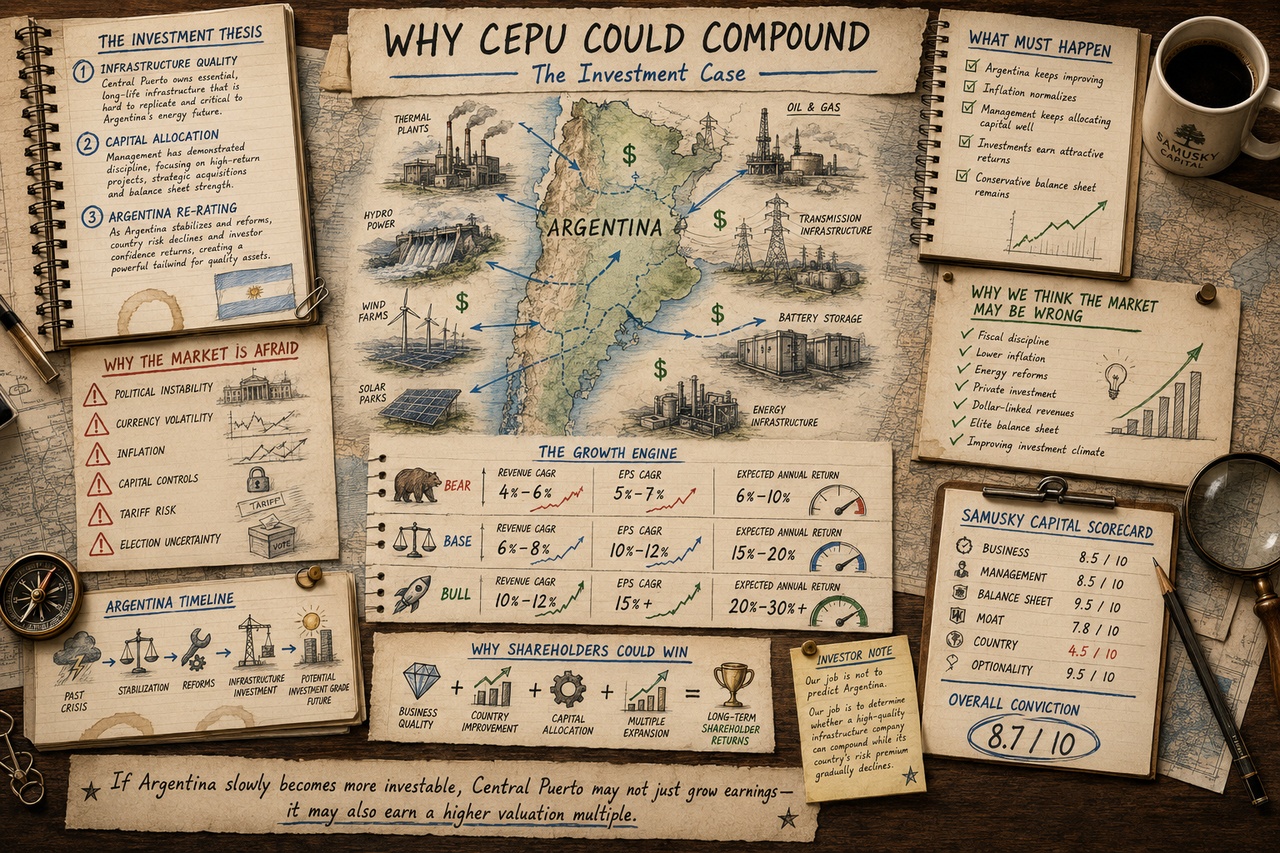
Facts vs. Assumptions
✅ Facts
- Argentina’s largest private electricity generator.
- Diversified power generation portfolio.
- High operating margins.
- Conservative debt levels despite the recent acquisition.
- Management actively reinvests capital.
- Acquisition of Patagonia completed.
- Battery storage projects are under development.
- Infrastructure assets with a long economic useful life.
🪧 Assumptions
- Argentina continues its economic normalization.
- The country risk discount will decline over time.
- The Patagonia acquisition will generate attractive long-term returns.
- The battery storage investments will achieve a satisfactory ROIC.
- Dividends will resume as soon as attractive reinvestment opportunities diminish.
- The regulatory environment remains largely stable.
This distinction is crucial.
The facts support the company as it stands today.
The assumptions determine future returns.
🐻 Bear Case
The political reform process stalls, regulation remains restrictive, and new projects deliver disappointing results.
Expectations
Revenue growth (CAGR) -> 4–6%
Earnings per share growth (EPS CAGR) -> 5–7%
Expected shareholder return -> 6–10% p.a.
⚖️ Base Case
Current reforms continue, and management remains disciplined in capital allocation—Patagonia and battery storage are contributing increasingly to earnings.
Expectation
Revenue growth (CAGR) -> 6–8%
Earnings per share growth (EPS CAGR) -> 10–12%
Expected return to shareholders -> 15–20% p.a.
🚀 Bull Case
Argentina is experiencing sustained economic normalization, the country’s valuation discount is narrowing significantly—and infrastructure investments are accelerating.
Expectation
Revenue growth (CAGR) -> 10–12%
Earnings per share growth (EPS CAGR) -> over 12%
Expected shareholder return -> potentially 20–25%+ p.a.
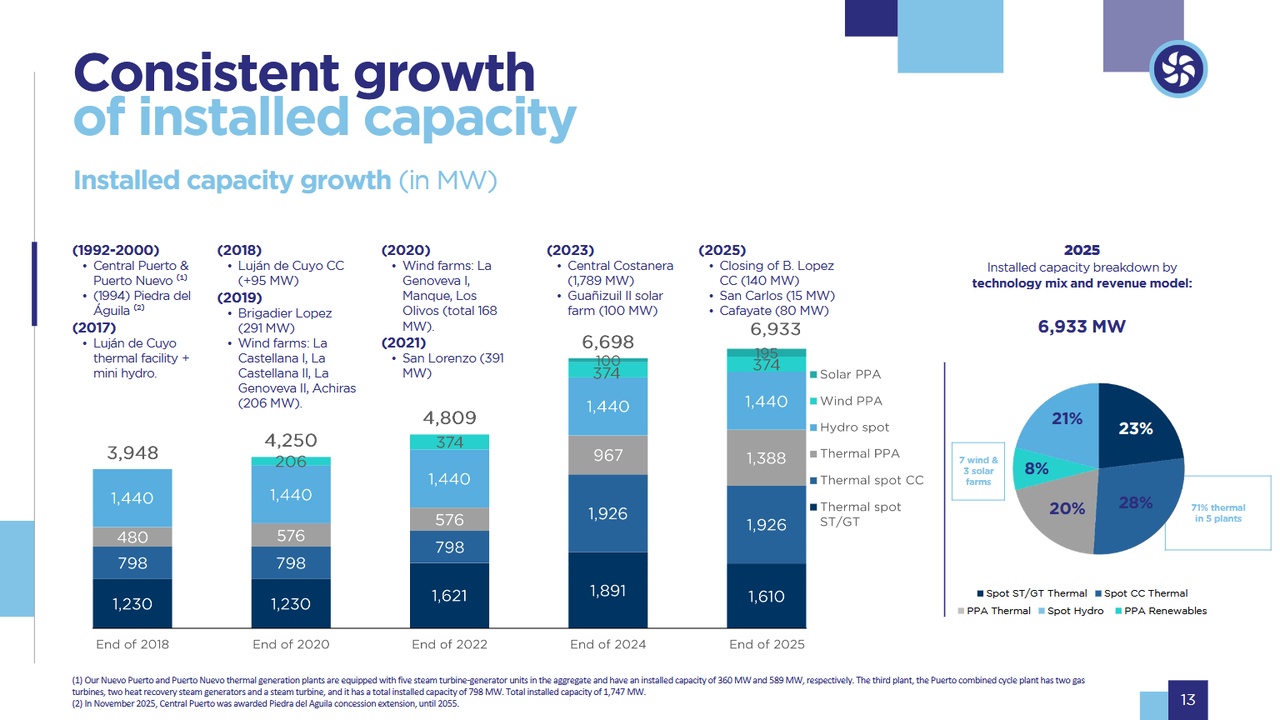
This scenario assumes both successful operational execution and a significant revaluation of Argentine assets.
Why is the market cautious?
The valuation discount primarily reflects sovereign risks rather than operational weaknesses.
⚠️ Among the biggest concerns are:
- Political uncertainty
- Historically high inflation
- Exchange rate volatility
- Capital controls
- Government intervention in the energy sector
- Argentina’s overall reputation as an investment destination
Why We Believe the Market Might Be Wrong
The underlying company appears to be significantly stronger than its home country’s reputation would suggest.
✅Positive factors:
- Solid balance sheet
- Disciplined management
- Essential infrastructure
- Long-lasting assets
- Diversified power generation
- Revenue Partially Denominated in U.S. Dollars
- Continuous investment pipeline
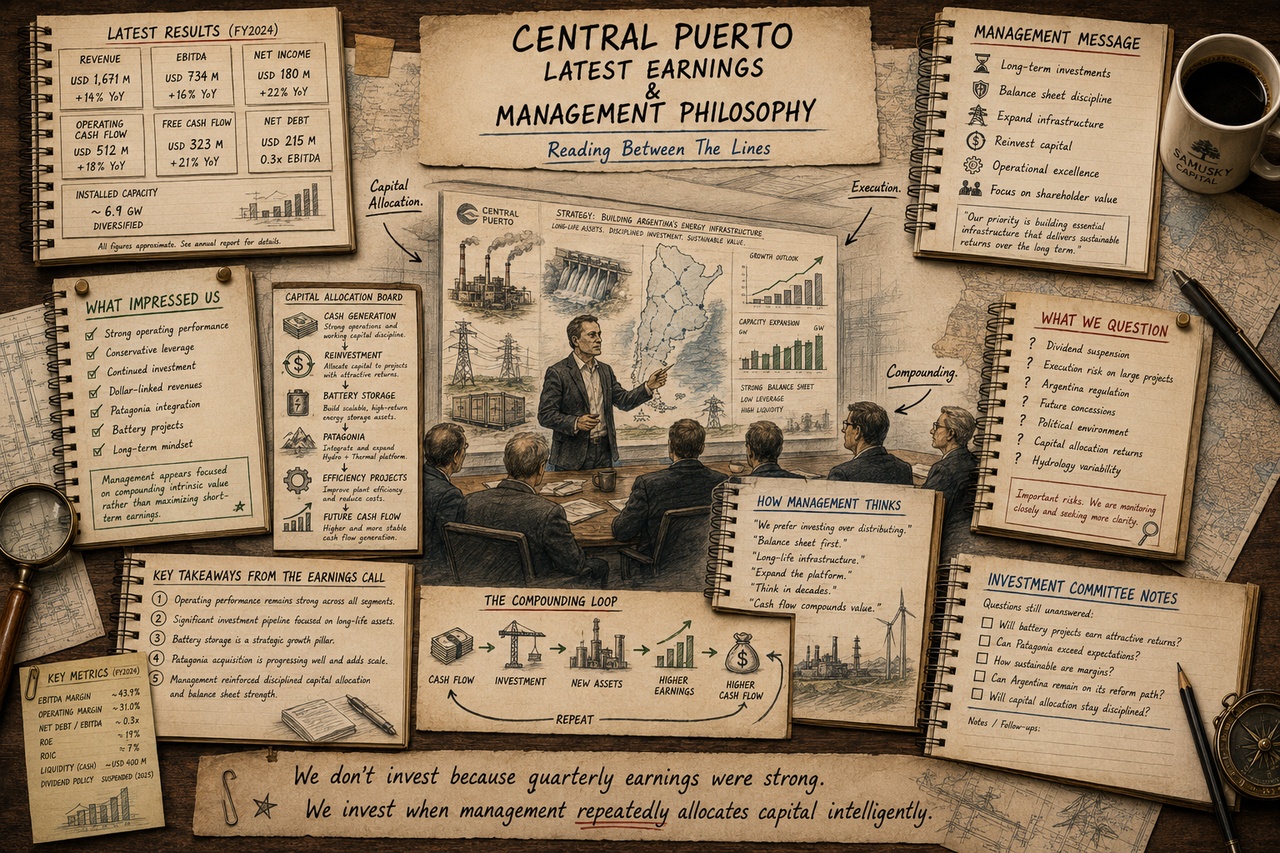
🔎The investment thesis requires consistent execution
✅ Argentina is continuing its reform course.
✅ Management remains disciplined in its capital allocation.
✅ New investments are generating returns above their cost of capital.
✅ The balance sheet remains conservative.
✅ Free cash flow continues to grow over the long term.
🫗Investment Kill Switches
❌ Argentina significantly rolls back its economic reforms.
❌ Capital allocation becomes permanently value-destroying.
❌ Debt rises sharply without adequate returns.
❌ Regulatory interventions permanently impair profitability.
❌ Growth investments fail to improve the return on capital over the long term.
💭Open Questions❓
❓What long-term return on capital will Patagonia actually achieve?
❓What returns will the battery storage projects generate?
❓How will future extensions of hydropower concessions affect profitability?
❓What will the normalized owner earnings be after the current investment cycle is completed?
❓When will resuming the dividend make economic sense?
🗺️Role in (my) portfolio
An infrastructure compounder from an emerging market. The company increases geographic diversification while aligning with the portfolio’s preference for essential infrastructure and capital-intensive quality companies.
Drivers of expected returns:
Earnings growth + disciplined reinvestment + gradual revaluation of country risk.
Unlike many other holdings, CEPU could benefit from both successful corporate performance and an improved macroeconomic outlook for Argentina.
🙏Investment Committee’s Assessment
Company Quality
⭐⭐⭐⭐☆ (8.5/10)
Management
⭐⭐⭐⭐☆ (8.5/10)
Balance Sheet
⭐⭐⭐⭐⭐ (9.5/10)
Capital Allocation
⭐⭐⭐⭐☆ (8.5/10)
Competitive Advantage (Moat)
⭐⭐⭐⭐☆ (≈7.2/10)
Country Risk
⭐⭐☆☆☆ (4.5/10)
Long-Term Optionality
⭐⭐⭐⭐⭐ (9.5/10)
Overall Conviction
High interest – Further due diligence is warranted.
Final Statement from the Investment Committee
Central Puerto appears to be a fundamentally strong infrastructure company operating in a structurally weak government environment. While the operating business exhibits many characteristics of a long-term compounder—essential assets, conservative financing, and disciplined capital allocation— the investment case ultimately hinges on whether recent investments generate attractive returns and whether Argentina continues on its path toward greater macroeconomic stability. Based on current information, the company’s quality appears to be higher than its market valuation reflects. At the same time, the discount due to country risk remains both the greatest risk and the most significant potential opportunity in this investment thesis.
That’s all from me for now. I’d of course welcome comments and any attempt to convince me otherwise 😅 or to challenge my investment thesis—I’ll do what I want anyway :) But I find it very interesting to read and examine other opinions.


