

Hello my dears,
Yesterday we already presented you Jakub's garden party value. But Matteo from Italy was also at the party.
And when Juan told him that his last value from Italy had only arrived mixed. Matteo didn't have to think twice.
Because the three of them had been talking about the good performance of $CAT (-0,27%) Caterpillar's good performance. And they both felt the effects of the ailing rail network on their journey.
So, at the suggestion of Matteo, we would like to introduce you to Tesmec $TES (+1,25%) to you.
Juan, Matteo, Jakub and I, of course, are looking forward to your many comments.
Tesmec SpA is an Italian-based company that develops, manufactures and markets integrated solutions for the construction and maintenance of infrastructures such as offshore and deep-sea networks and pipelines. data and materials as well as technologies for quarries and open-cast mining. Tesmec is mainly active in two markets: The development, manufacture, marketing and sale of integrated systems and machines for the laying of electricity and fiber optic cables and for the laying of railroad power lines and the development, manufacture, marketing and sale of high-performance crawler excavators used in excavation work for the laying of underground networks and pipelines or in earthworks and, to a lesser extent, multi-purpose machines for construction sites. The company operates through subsidiaries such as Marais Technologies SAS and others.
Number of employees: 900
Founded in northern Italy in the 1950s as a family business and now a listed company, the Group has grown over generations, driven by the desire to develop versatile solutions and first-class systems. Over the years, the Group's presence has expanded on all continents, positioning itself as a leading force in the evolution of infrastructures.
OUR VISION
FOR THE FUTURE
OUR MISSION
FOR THE PLANET
COMMITTED TO ENERGY TRANSITION, DIGITALIZATION AND SECURITY
- Technology partner in markets driven by energy transition, digitalization and sustainability with INNOVATIVE, VALUE ADDING INTEGRATED SOLUTIONS for the construction, maintenance and efficiency of INFRASTRUCTURES for TRANSPORT AND DISTRIBUTION OF ENERGY, DATA AND MATERIALS
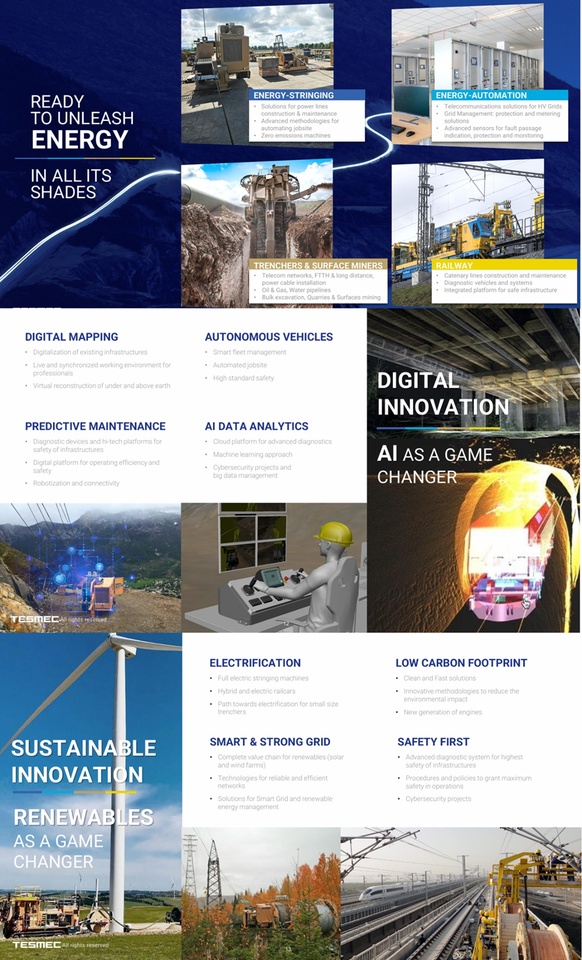
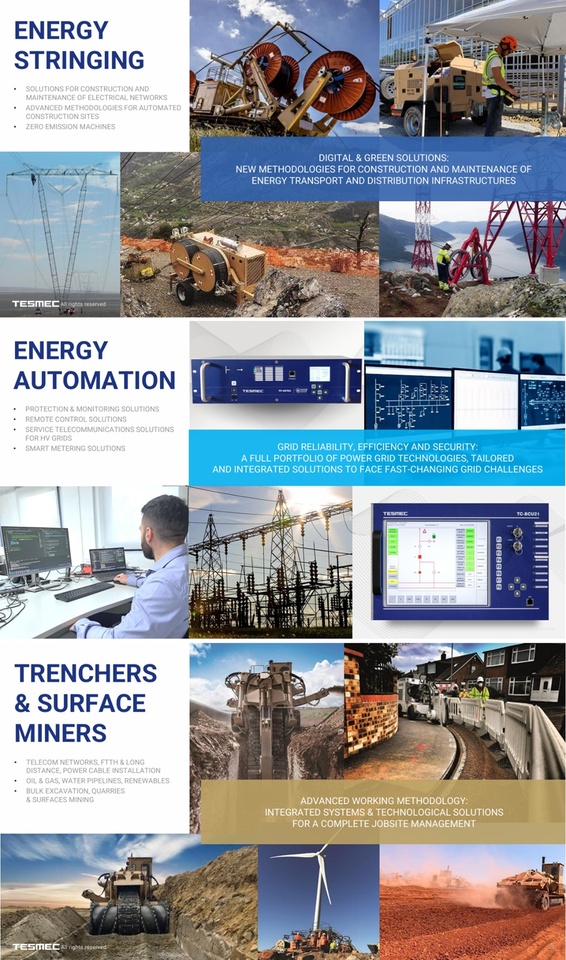
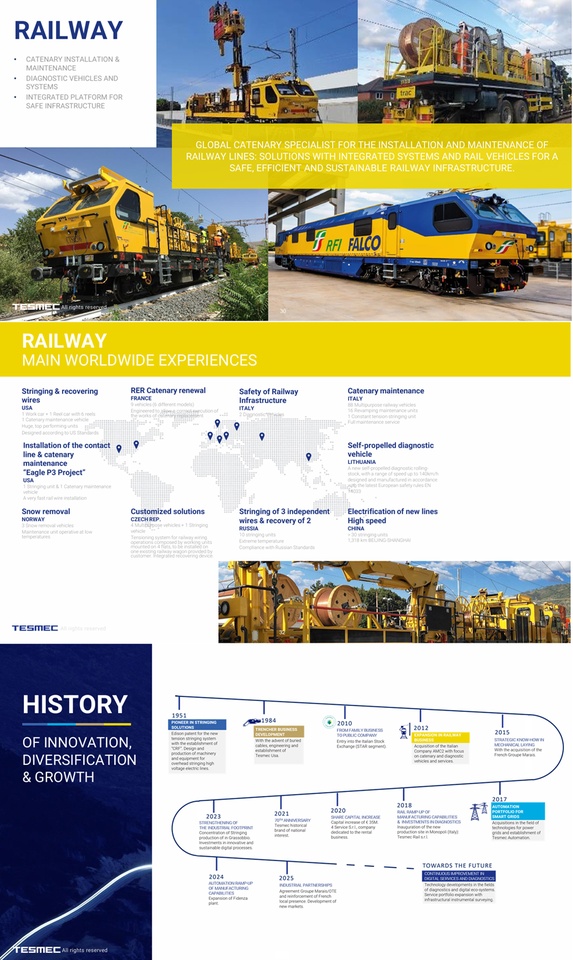
Tesmec Presentation November 2025
Presentations
03/03/2026
Die Tesmec-Gruppe stärkt ihre technologische Positionierung und vergibt zwei Ausschreibungen im Gesamtwert von 71 Millionen Euro mit den Slowenischen Eisenbahnen zur Lieferung von Fahrzeugen für die Instandhaltung des Eisenbahnnetzes. TesmecTesmec bringt die neue Re.M-App auf den Markt: intelligentere, schnellere und vernetztere Flottenüberwachung | Tesmec
In Bulgaria, a new rail-guided, self-propelled OCPC 401 machine for overhead line maintenance was put into operation at Kurilo station on March 10, 2026. The vehicle supplied by Tesmec is the 16th vehicle in a framework delivery of 20 machines; the 17th is due to arrive between March 23 and 27.
Sales breakdown by business division:
2025 (EUR)
Trencher 108 million
Energy 96.65 million
Railway 53.41 million
Geographical distribution of sales:
2025 (USD)
Italy 64.07 million
Europe 44.17 million
North and Central America 40.26 million
Brazil, Russia and China 39.55 million
Middle East 35.11 million
Africa 34.45 million
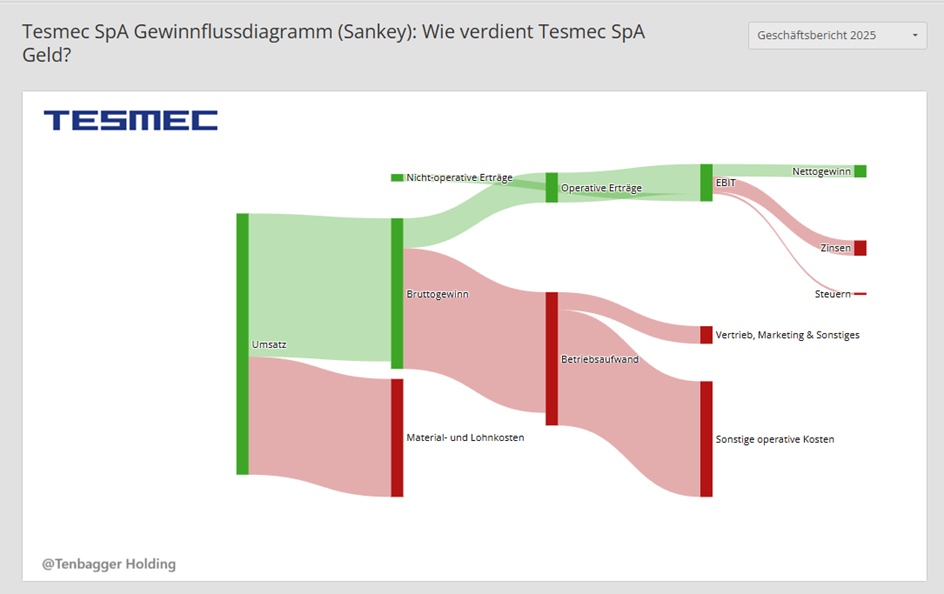
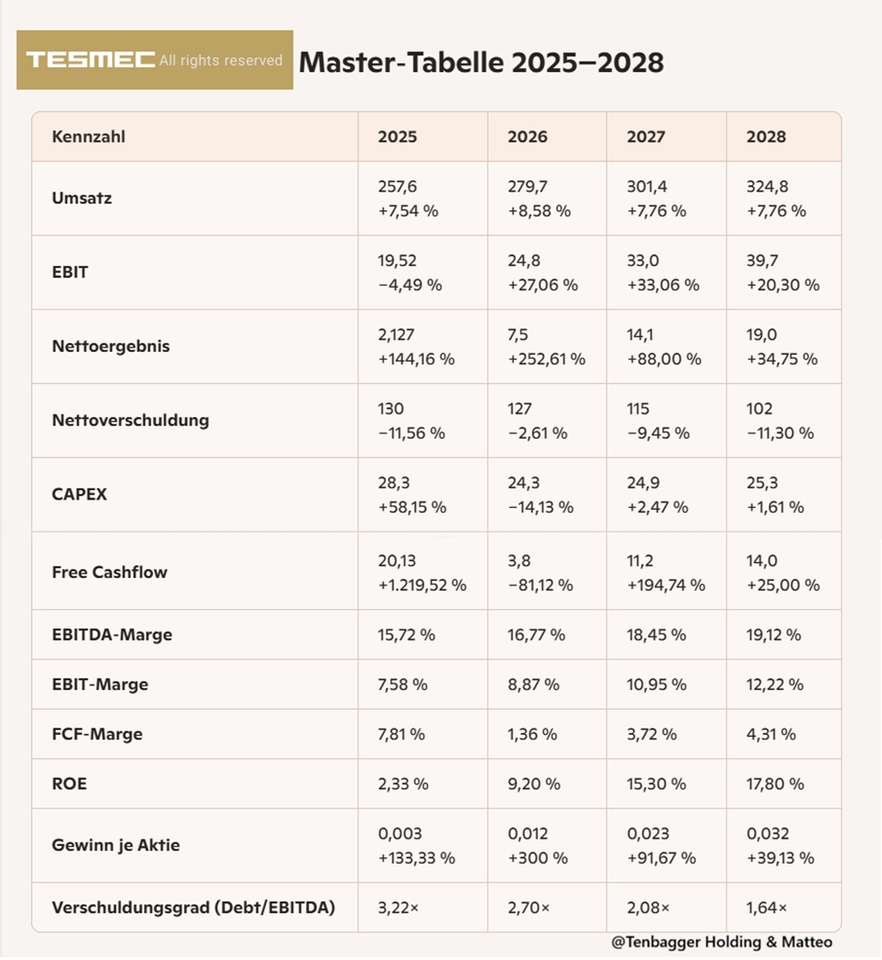
(All figures in € million)
Short Juan summary (Tesmec, based on your MarketScreener tab)
(compact, clear, the way you always want it)
Tesmec picks up cleanly from 2025: Sales grow steadily through each year, EBIT and net income scale much faster than sales - classic operating leverage. Margins improve across the board, especially the EBIT and EBITDA margins. The balance sheet is improving: net debt is falling year on year, leverage ratio is falling from over 3× to under 2×. Free cash flow remains volatile, but clearly positive and rising. From 2027, Tesmec looks like a real quality mid-cap with increasing profitability and decreasing risk.
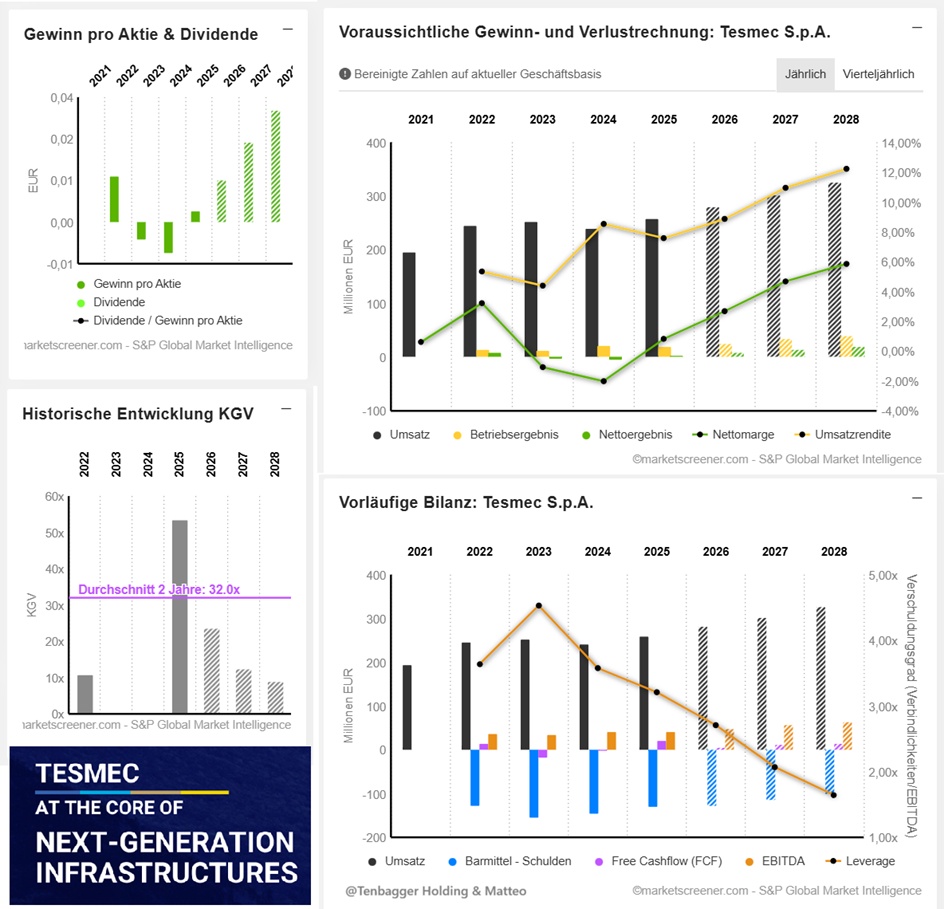
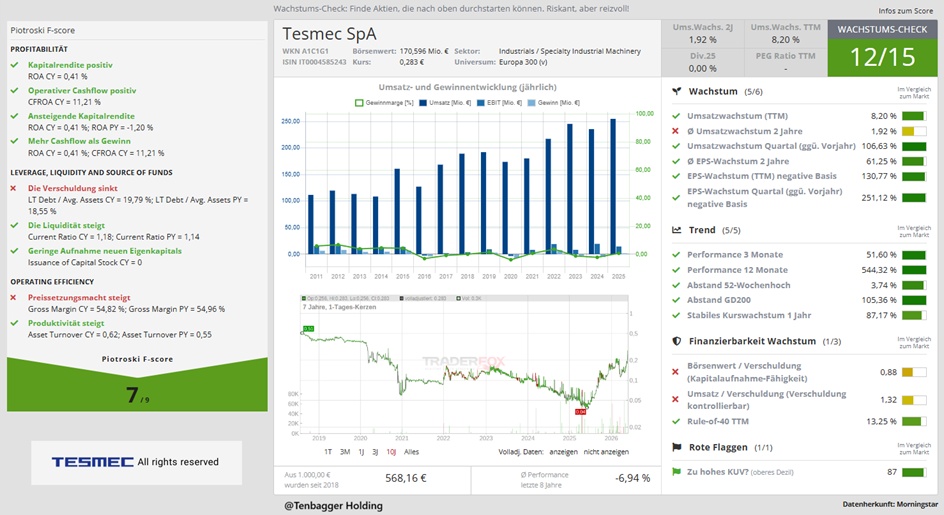
Market value 170.6
Number of shares (in thousands) 601,748
Date of publication 11.03.2026
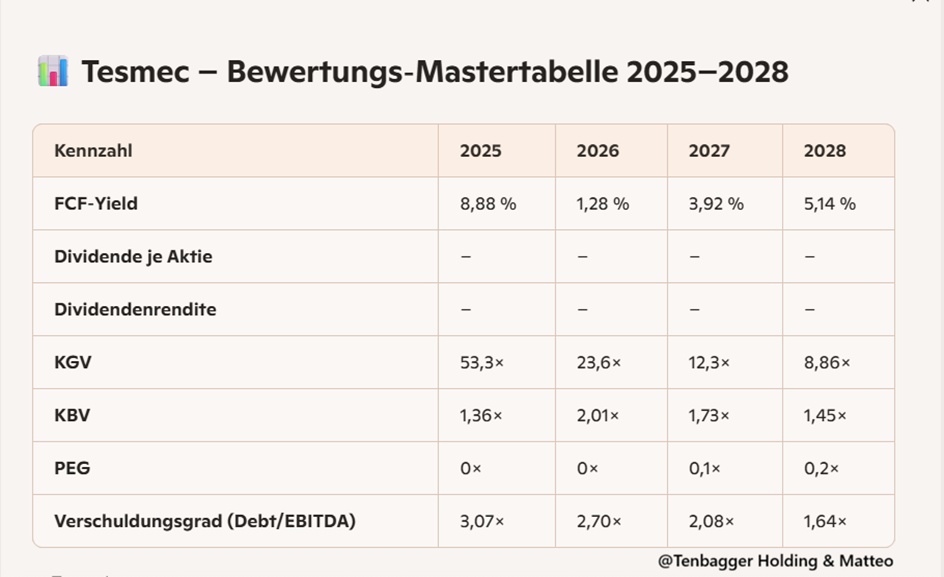
Short Juan summary (Tesmec 2025-2028 valuation)(compact, clear, exactly your style)
Tesmec looks like a classic valuation turnaround: the P/E ratio falls from expensive (2025) to attractive (2028), while the leverage ratio runs cleanly towards 1×. The P/B ratio remains low and stable, which supports the value case. PEG makes sense for the first time from 2027 and shows that growth and valuation fit together again. No dividend, but the FCF yield will increase significantly from 2027. Overall: Tesmec will become cheaper, more stable and of better quality every year - a valuation profile that will become really interesting from 2027.
Short Juan conclusion (financials + valuation)
Tesmec shows a clear picture from 2025: operating leverage + falling debt + falling valuation. Stable sales growth, EBIT and net income grow significantly faster - margins are rising sharply. At the same time, the leverage ratio falls year on year, which noticeably relieves the balance sheet.
On the valuation side, Tesmec is becoming cheaper every year. more favorableThe P/E ratio halves several times, the P/B ratio remains low, and from 2027 growth matches the price (PEG) for the first time. The FCF yield picks up again from 2027 and also confirms the turnaround in terms of cash flow.
In short: Tesmec is developing from a low-margin stock with a strained balance sheet to a more profitable, favorably valued mid-cap with clearly decreasing risk and increasing quality.
Performance
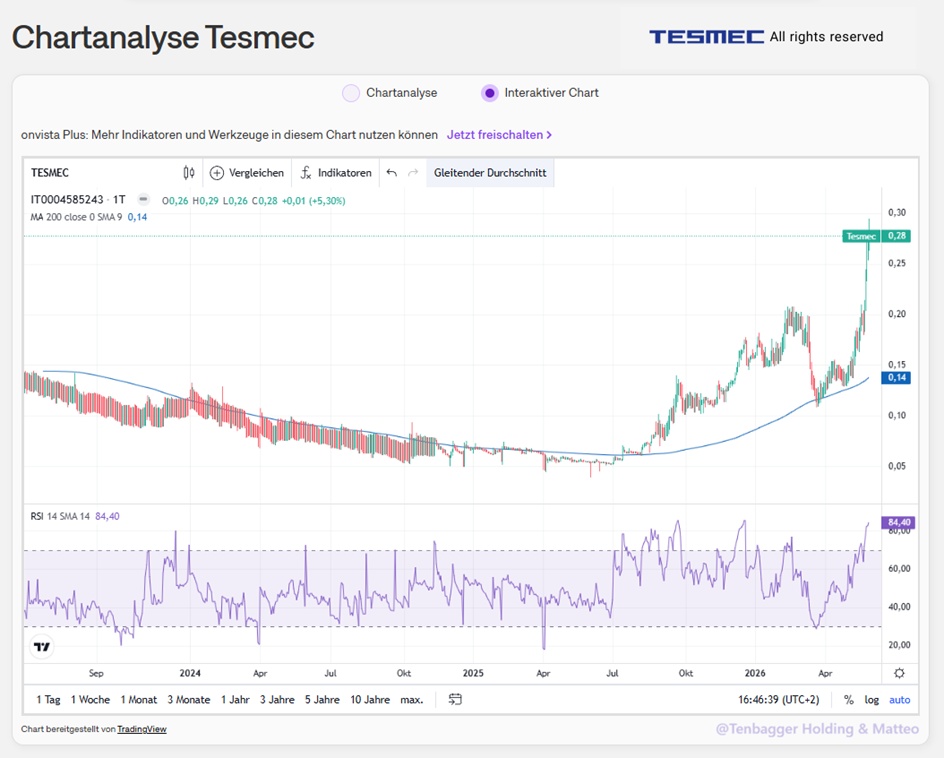
1 week +53.93 %
1 month +113.19 %
6 months +109.65 %
1 year +406.38 %
3 years +118.90 %
29.05.2026, 22:22:35 -
Lang & Schwarz (EUR)
0.278 EUR