Hello my dears,
dear Jack has been checking and commenting on Juan's performances from time to time. First of all, a big thank you for that. (@Aktienhauptmeister )
In the meantime, the two have become friends. In this context, Juan has now gone over to Jack's company presentation once again. And has also created a Tenbagger Matrix created.
All under the motto
"Successful together"
We look forward to your comments on
A10 $ATEN (-4,49%)
SAN JOSE / LONDON (IT BOLTWISE) - A10 Networks is moving into the spotlight following quarterly results showing Q1 2025 revenue of $60.7 million and the expansion of recurring revenue Investoren. The focus is on application security, DDoS defense and the question of how robust cash flow and margins will remain in an intensely competitive environment. For market participants, the decisive factor is whether Thunder integrations in the provider and 5G environment deliver the announced stability.
The focus of many Investorare currently focusing less on individual product features and more on the financial mechanics behind cybersecurity solutions.Angeboten: How quickly does demand turn into predictable, recurring revenue - and how cleanly does this translate into margins and cash flow? A10 Networks brings precisely this area of tension into the discussion after the company presented its results for the first quarter of 2025. With a turnover of 60.7 million US dollars for the quarter ending March 31, 2025, the provider of application delivery and security functions provides a current snapshot. What will be more decisive, however, is how consistently the mix of hardware, licenses and security subscriptions continues in subsequent quarters.
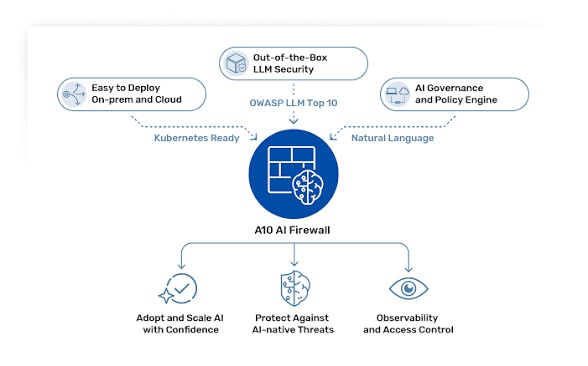
From a technical perspective, A10 Networks relies heavily on its Thunder platform, which combines application delivery controller capabilities, DDoS mitigation and carrier-grade NAT functions into an integrated set. This is attractive for providers, cloud environments and large enterprise customers because it bundles security and performance requirements closer to the network and service layer. Scaling is particularly relevant in everyday life: many organizations operate hybrid workloads and therefore require solutions that can be operated both in traditional data centers and in virtualized or cloud-based operating models. A10 addresses this expectation via virtual appliances and cloud-based services that are linked to an increasingly software-centric operating concept.
Click on the link ⬇️ for the full article
A10 Networks: Quartalszahlen und wiederkehrende Umsätze im Fokus der Cybersecurity-Investoren
Strong AI demand: BTIG raises price target for A10 Networks
29,04,2026
Summary of the article - A10 Networks
BTIG raises the price target for A10 Networks from 22 to 30 USD and confirms Buy. Reason: strong AI demandwhich caused Q1 to significantly exceed expectations.
Key points:
- Q1 sales: USD 75m (+13.4% YoY), above BTIG estimate and consensus.
- Operating result & EPS both above consensus.
- Gross margin: 79 %.
- Share currently highly valued (P/E RATIO 46.7), driven by AI optimism.
- Outlook 2026 confirmed: +10-12 % sales growth, 28-30% EBITDA margin.
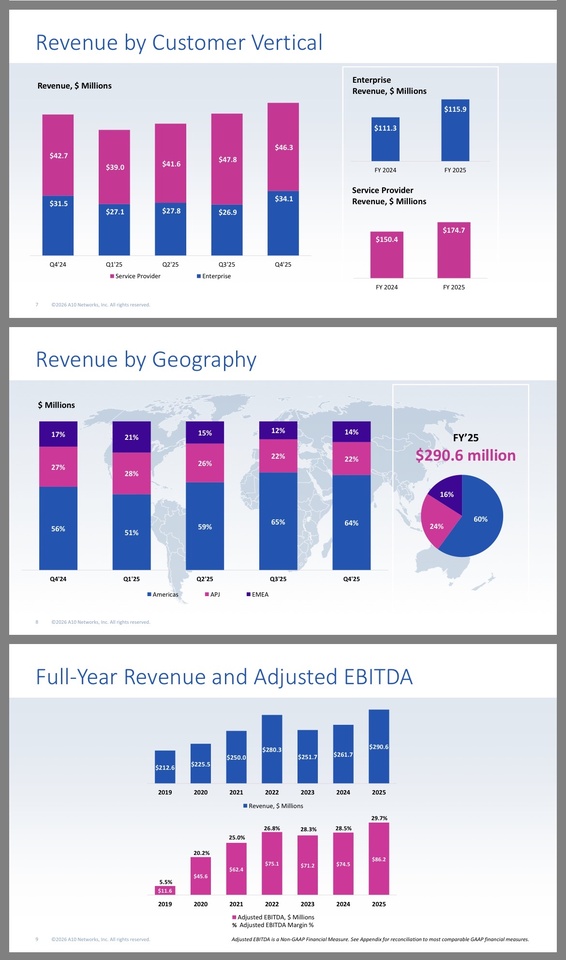
- Strongest demand from America, telecom stable, headwind in Middle East & Japan.
- BTIG slightly raises sales forecasts for 2026/27.
Despite good figures, short-term share price decline due to supply chain concerns.
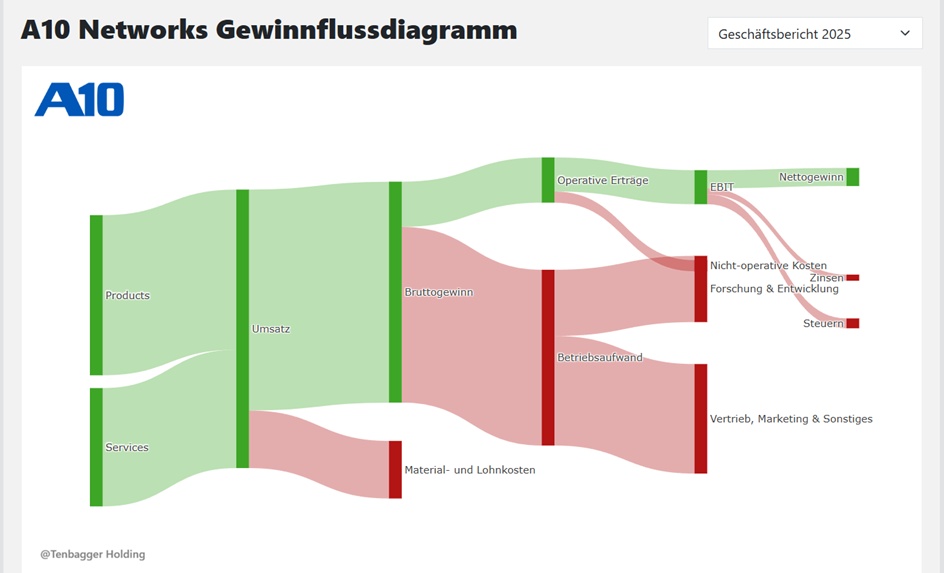
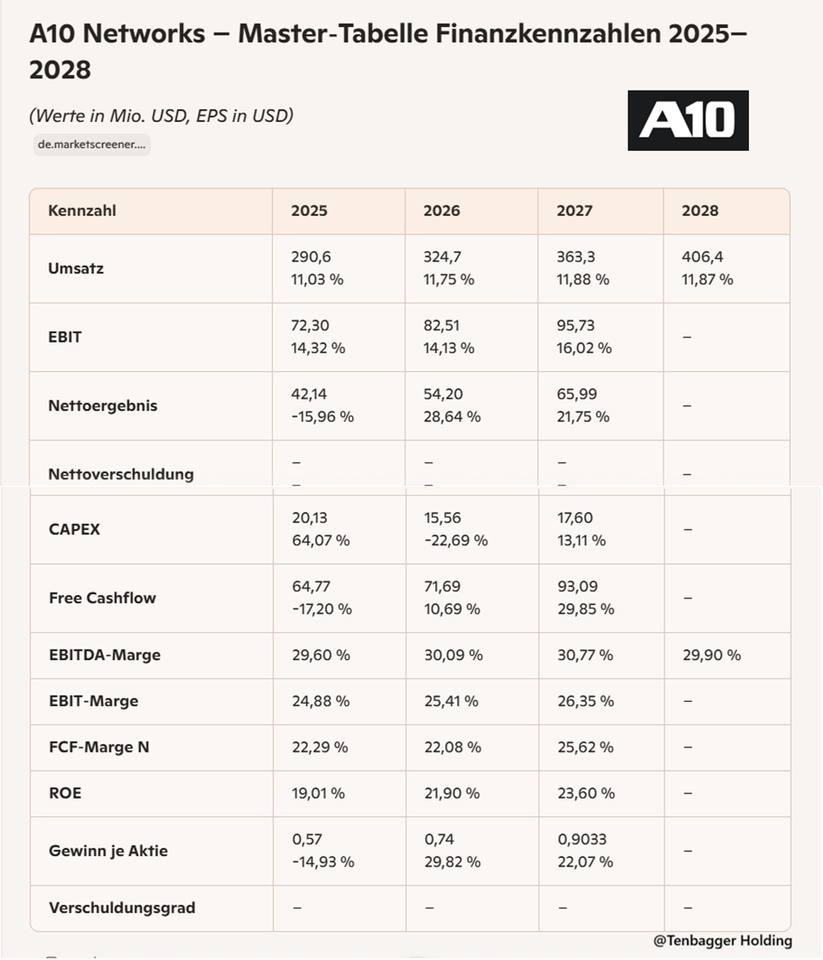
Juan-Investment-Summary - A10 Networks (Financials + Valuation)
(compact, analytical, perfect for your watchlist decisions)
1) Growth & scaling
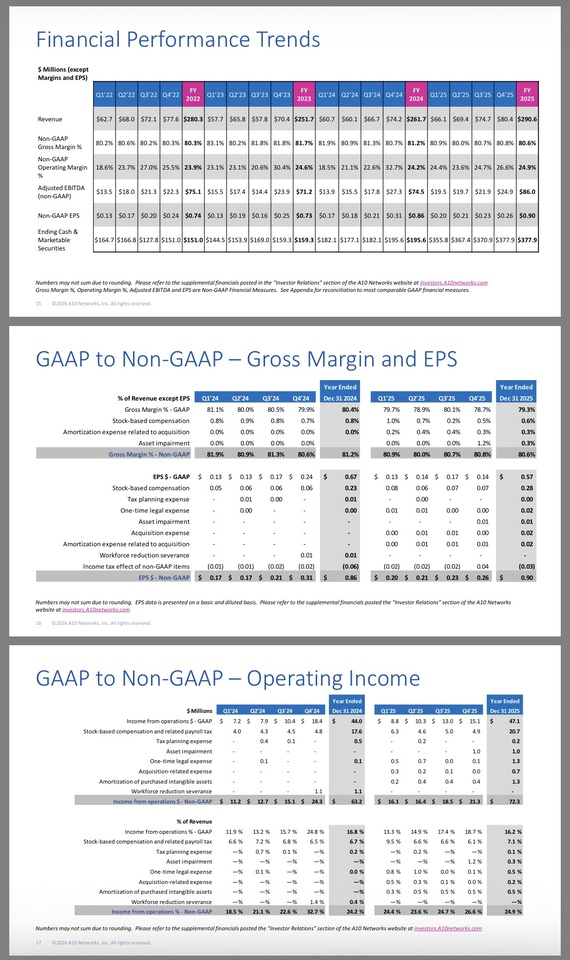
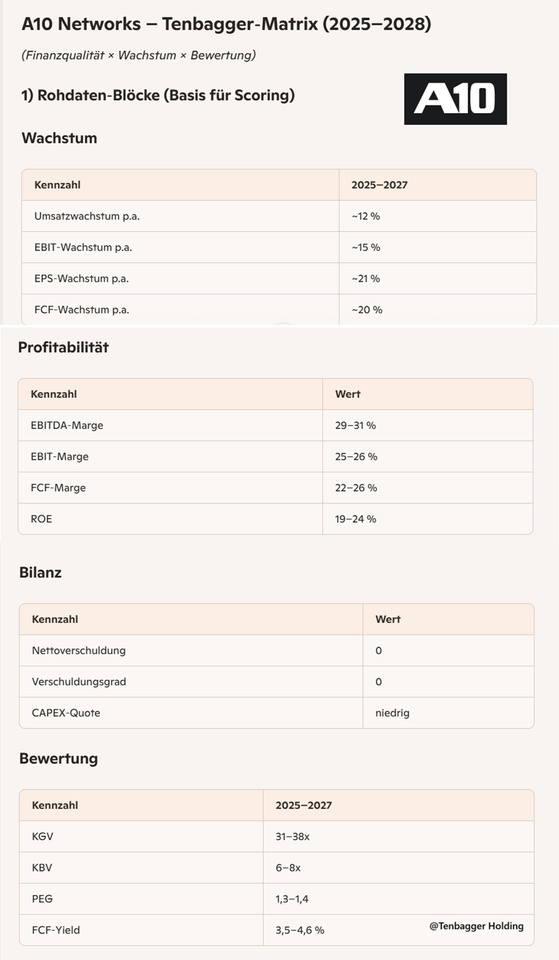
- Revenue growth 2025-2027 from 290.6 → 363.3 m USD.
- Growth stable at ~12 % p.a. → Clean, predictable scaling path.
- EBIT increases from 72.3 → 95.7 million USD → operating levers work.
2) Profitability
- EBITDA margin increases to 30,8 % (2027).
- EBIT margin climbs to 26,35 % → strong for an infrastructure/security play.
- FCF margin 2027 at 25,6 % → Cash machine.
3) Cash flow & CAPEX
- FCF grows from 64.8 → 93.1 m USD (2025-2027).
- CAPEX remains moderate → Asset-light model.
- FCF conversion >130 % → extremely efficient.
4) Balance sheet quality
- Net debt: 0 over all years → debt-free.
- Debt-equity ratio not relevant → Financial risk minimal.
5) Valuation
- P/E RATIO 2026/2027: 38.2x → 31.3x → Expensive, but growth-driven.
- P/E RATIO 2026/2027: 8.32x → 7.02x → clear quality premium.
- EV/Sales 2027: 5,6x → typical for profitable security software.
- PEG ~1 → valuation fair for growth.
6) Earnings quality
- EPS increases 2025-2027 from 0.57 → 0.9033 USD.
- ROE stable high (19-24 %) → Return on capital employed strong.
- Juan's conclusion
- A10 Networks is a highly profitable, debt-free security infrastructure player with stable double-digit growth, strong margins and excellent cash conversion. The share is not cheapbut the valuation is fundamentally justifiedQuality, scaling, cash flow - all clean.
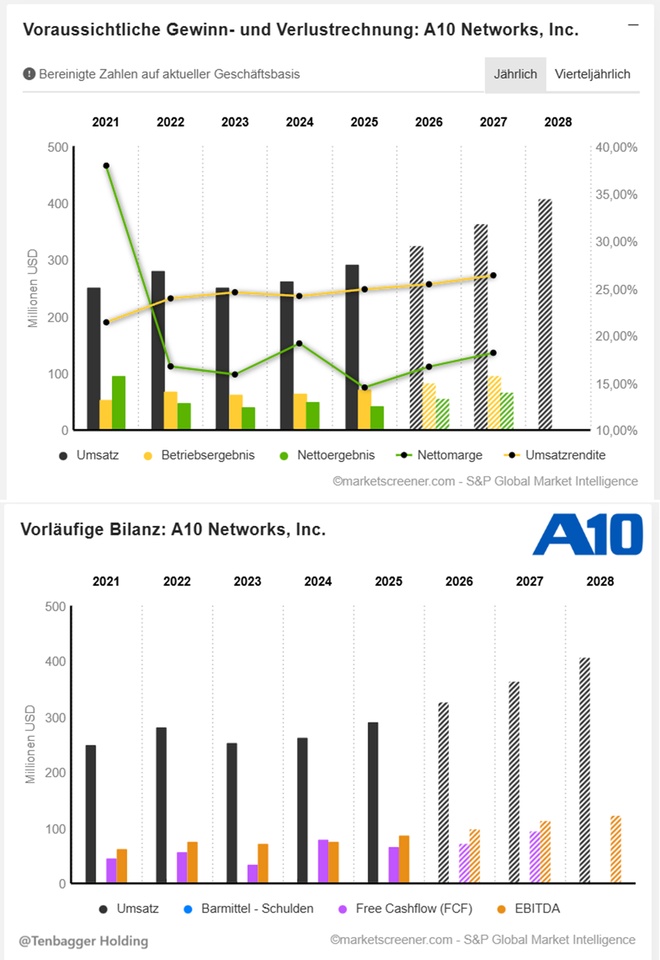
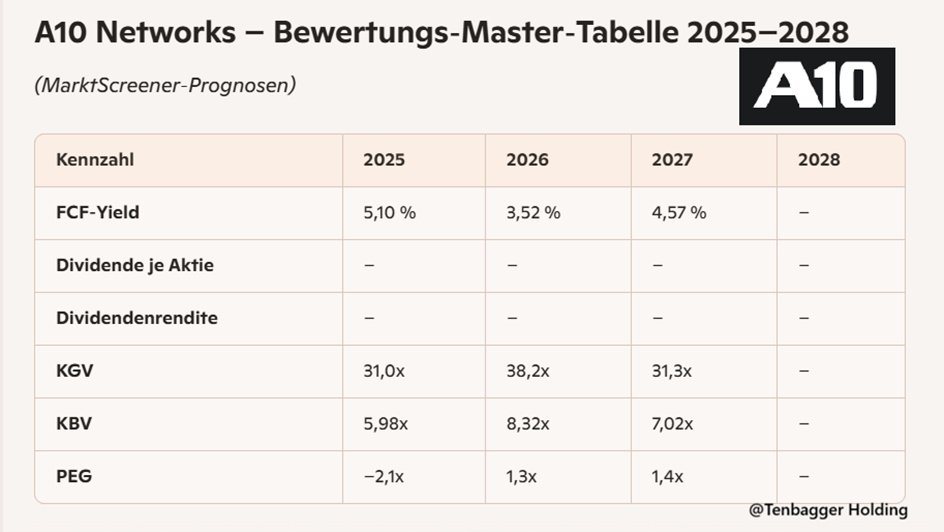
Market value 2,036
Number of shares (in thousands) 71,998
Date of publication 04,02,2026
3) Total score (Tenbagger potential)
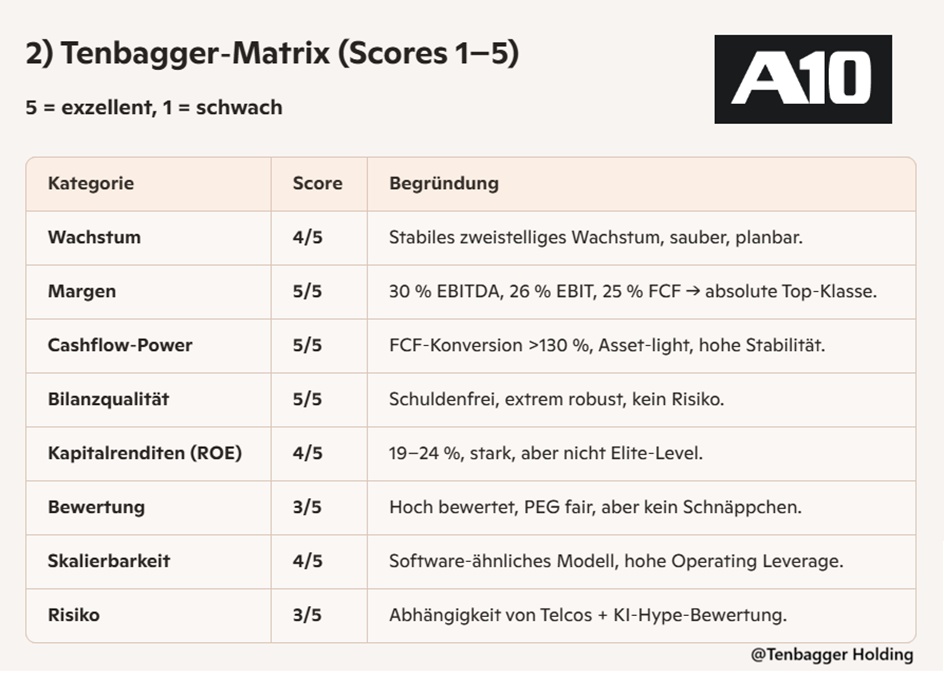
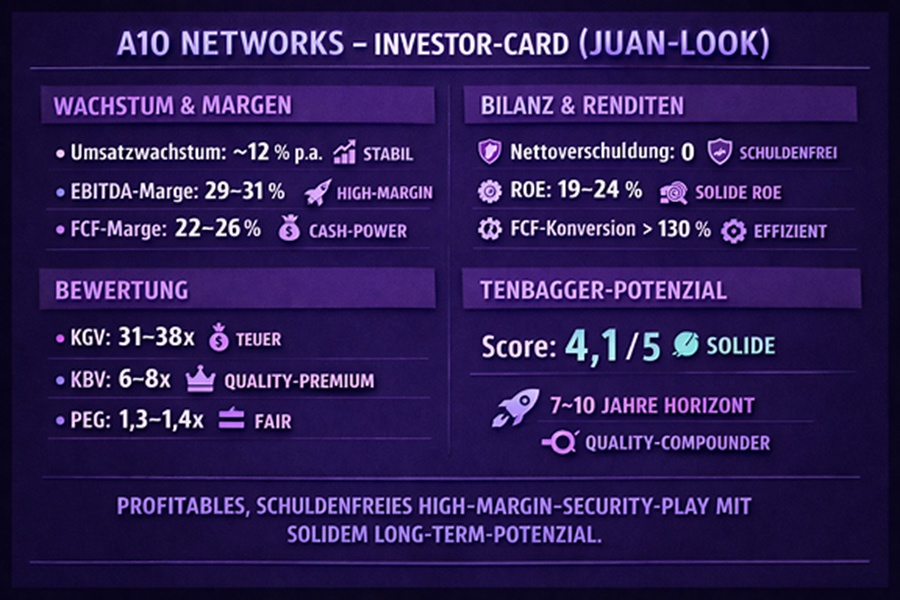
A10 Networks - Tenbagger score: 4.1 / 5
Juan interpretation
A10 is a highly profitable, debt-free compounder with strong margins and clean growth. The valuation is ambitious, but not irrational.
Tenbagger potential: medium-high (quality compounder, no early-stage moonshot). The story is Quality + cash flow + scalingnot "hypergrowth".
4) Ultra-compact Juan summary
A10 is a profitable, debt-free high-margin security player with stable double-digit growth. Valuation expensive, but fundamentally justified. Tenbagger potential solid, but over 7-10 years rather than 3-5.
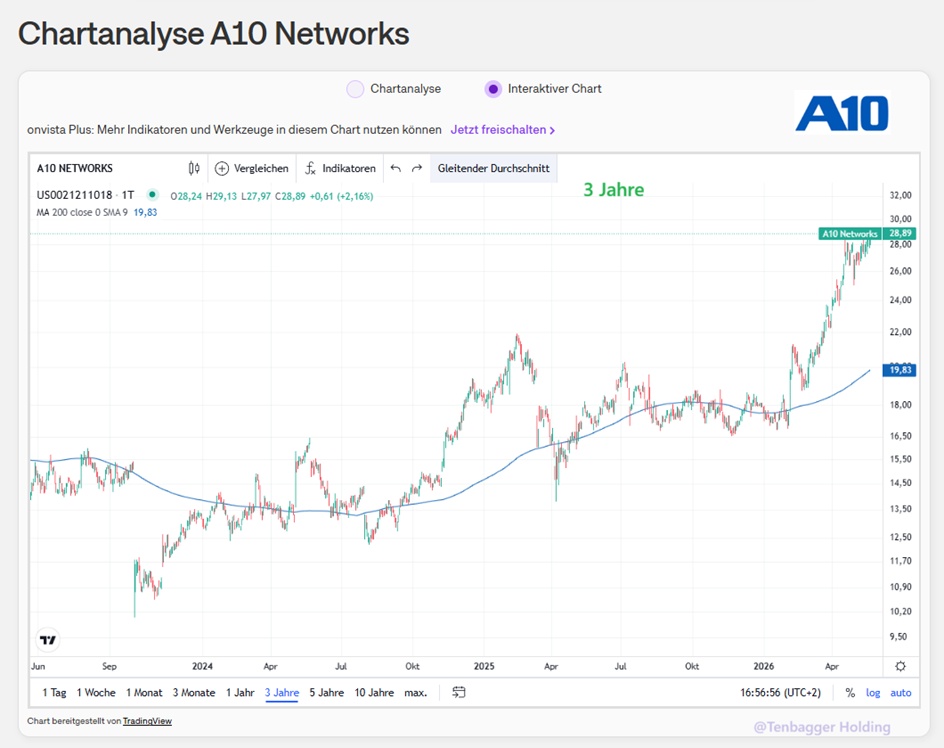
21,05,2026
yesterday, 22:00:03 -
NYSE (USD)
28.68 USD
+0.40 USD+1.41 %