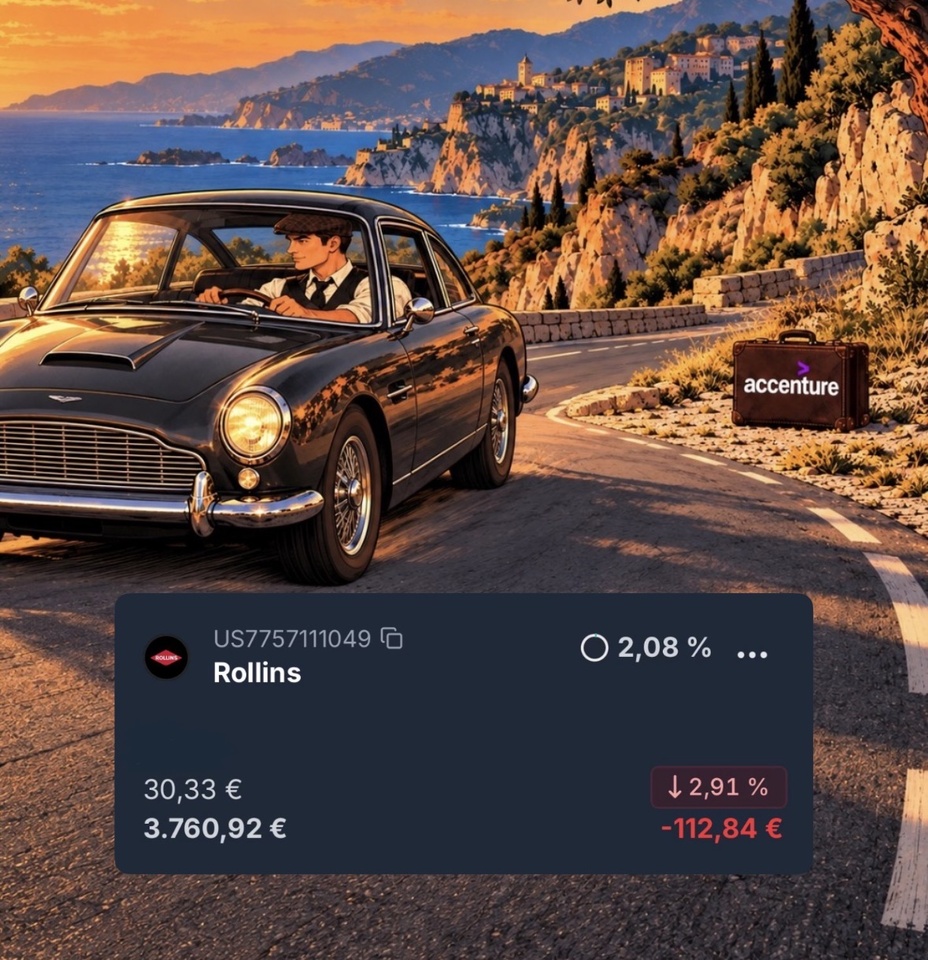
It was about time I made my $ACN (+0%) position by cut in half. As competition has intensified, competition . However, my main reason for selling was to risk minimization … not because I had somehow concluded that ACN’s engine was broken. In fact, everything is still running smoothly there.
After the split, the stock is trading at approximately 2.35% of my portfolio. In my opinion, that’s a healthy position size.
With the proceeds, I bought the overvalued stock of $ROL (+1,13%) .
The operating growth of the pest control company has been… actually pretty good. However, the stock is ultimately facing operational hurdles . The reasons for this were:
- AI-powered marketing: By using AI tools instead of traditional search engines to find providers, Rollins saw a sharp decline in digital customer inquiries in the consumer sector.
- Margin Pressure and Rising Costs: Significantly higher personnel and insurance costs, coupled with a declining gross margin, weighed on profitability.
- Disappointing Results and Lowered Forecast: Falling short of market estimates and a reduced annual forecast hit the already highly valued stock hard.
Over the past decade, the market has consistently assigned Rollins an excessively high P/E ratio of 50 or more . In the long run
No, you didn’t misread that 🙃
One reason for this was precisely the defensive nature and the sustainability of contracts and revenue.
No matter what the state of the economy is: hygiene and the elimination of insect infestations, termite infestations, and the like are a MUST (requirement) for hotels, restaurants, hospitals, pharmaceutical companies, consumer goods companies, etc.
That means: It has to be taken care of. And that’s where ROLLINS comes in.
And other companies, such as $ECL (+0,76%)
I have a P/E ratio of ~30 for Rollins after the stock had nearly halved in value.
My new Rollins position currently yields about 2.1% of my portfolio. So it won’t hurt if the stock continues to underperform for a little while longer.
The stock itself might still be overvalued ... and in my opinion, it is, if you look at the other metrics like P/E, P/B, P/C... (you know the drill).
Compared to valuations over the past decade , however, the figures are now significantly lower because in the past, investors paid a premium for quality of the company. With a valuation like that, it’s also harder for the company to impress, because expectations are too high… which, in a way, makes a bit of sense.
Be that as it may… the future will decide whether something will pay off or not.
Do you have Rollins in your portfolio?