
Mercedes stock (formerly Daimler, WKN 710000) is under pressure following a downward revision of its forecast: On October 27, 2026, Mercedes-Benz cut its outlook for the passenger car division in an ad hoc announcement; the stock fell 3.9% that day. At EUR 40.68 (Xetra closing price on Oct. 30, 2026), the stock is trading about 35% below its 52-week high of EUR 62.34 and just above its annual low of EUR 38.89.
The third quarter itself exceeded expectations, but weakness in China, higher material costs, and weak cash flow are weighing on the outlook. On the other hand, the stock offers a dividend yield of about 8.6%, a P/E ratio of about 7.7, and net liquidity in the industrial business of EUR 31 billion. From a technical analysis perspective, a wait-and-see approach is advised: a classic buy signal will only emerge above EUR 48.
Key Points
- Price: 40.68 EUR (Oct. 30, 2026), about 35% below the 52-week high of 62.34 EUR
- Forecast lowered: Passenger car return on sales for 2026 now only 2 to 3% (previously 3 to 5%)
- Q3 2026: Adjusted EBIT of 1.78 billion EUR (−15%), industrial free cash flow of only 172 million EUR
- Dividend: EUR 3.50 per share for 2025, approximately 8.6% yield
- Average price target from six analyst firms: 52.58 EUR (range 42.50 to 70 EUR)
- Chart: Buy signal only above 48 EUR; below 38.89 EUR, 34.75 and 31.20 EUR are potential support levels
What are the current key figures for Mercedes stock?
- Price (Xetra): 40.68 EUR (Oct. 30, 2026)
- 52-week high/low: 62.34 EUR (January 2026) / 38.89 EUR (October 8, 2026)
- Market capitalization: approx. 39.1 billion EUR
- P/E ratio 2026e: approx. 7.7 (estimated earnings of 5.29 EUR per share)
- Dividend for 2025: 3.50 EUR, approx. 8.6% yield
- Revenue Q3 2026: 30.7 billion EUR (previous year: 32.1 billion EUR)
- Adjusted EBIT for Q3 2026: EUR 1.78 billion (−15%)
- Consolidated net income for Q3 2026: EUR 1.52 billion (previous year: EUR 1.19 billion)
- Adjusted return on sales, Cars, Q3: 2.5% (previous year: 4.8%)
- Q3 Free Cash Flow, Industrial: EUR 172 million (previous year: EUR 1,367 million)
- Net liquidity, Industrial: EUR 31.0 billion (September 30, 2026)
What news is currently driving Mercedes stock?
- Oct. 30, 2026: DZ Bank maintains its “Buy” rating but lowers the fair value from 55 to 48 EUR.
- Oct. 29, 2026: Deutsche Bank lowers its target price from 70 to 65 EUR (Buy); UBS lowers its target price from 45 to 42.50 EUR (Neutral).
- October 28, 2026: Q3 results. Passenger car sales down 8% to 407,232 vehicles; industrial free cash flow at just 172 million EUR.
- October 27, 2026: Ad hoc announcement with downward revision of forecast. Consolidated EBIT now only at the previous year’s level, due to China and higher costs in the fourth quarter. The stock falls 3.9% to 39.78 EUR.
- Oct. 8, 2026: Annual low at EUR 38.89.
- September 30, 2026: According to dpa-AFX, Mercedes is relaunching its voluntary severance program in Germany, with a start date expected in December.
What does Mercedes-Benz do—and how does the group make its money?
Mercedes-Benz Group AG, based in Stuttgart, manufactures premium passenger cars and vans and finances them through its own financial division. Its stock (ISIN DE0007100000, WKN 710000, ticker symbol MBG) is exactly the one that many investors still look for today as a Daimler stock. The group has been called Mercedes-Benz Group since February 2022, after the truck and bus business was spun off as Daimler Truck in December 2021.
Mercedes-Benz Cars: Passenger cars ranging from the A-Class to Maybach. In 2025, 1,801,291 vehicles were sold (−9.2%); adjusted EBIT was EUR 4.8 billion, and the return on sales was 5.0% (previous year: 8.1%). Just how hard China is currently hitting German premium manufacturers is also evident from the Porsche Aktie —the slump in the Middle Kingdom is having an even more brutal impact there.
Mercedes-Benz Vans: The Sprinter, Vito, and V-Class generated an adjusted EBIT of EUR 1.76 billion and a return on sales of 10.2% in 2025, with 359,136 vehicles sold.
Mercedes-Benz Financial Services: Leasing, financing, and insurance generated an adjusted EBIT of EUR 1.27 billion in 2025. In the third quarter of 2026, the contribution rose by 42% to EUR 445 million.
Here is how the profit is broken down: Approximately 61% of adjusted segment EBIT comes from Cars, 23% from Vans, and 16% from Financial Services (based on our own calculations). Consolidated revenue in 2025 was EUR 132.2 billion.
Fundamental Analysis: Is the Mercedes Stock Undervalued?
Based on earnings, Mercedes stock is cheap, but not exceptionally cheap: At EUR 40.68, the 2026 P/E ratio stands at around 7.7, which is only slightly above the 10-year average of 7.5. According to Aktienfinder, the fair value based on adjusted earnings is therefore currently roughly in line with the current share price.
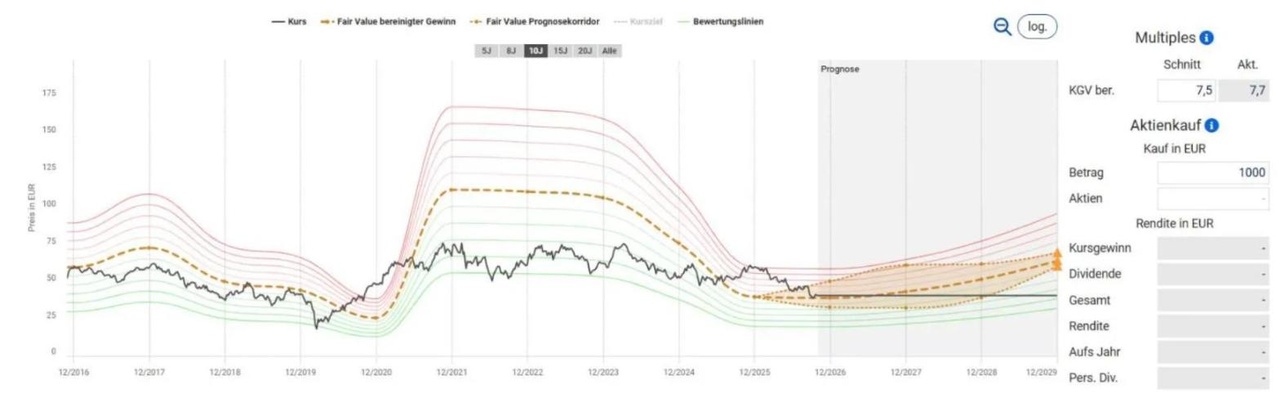
Industry Comparison: According to Aktienfinder, BMW has an adjusted P/E ratio of 5.6, while Volkswagen’s is over 30 due to a sharp drop in earnings.
Margin trends: This is where the real problem lies. The passenger car margin fell from 8.1% (2024) to 5.0% (2025) and to just 2.5% in the third quarter of 2026. For the full year, Mercedes expects 2 to 3%; for the fourth quarter, according to the CFO, the passenger car business is expected to break even at best.
Cash Flow and Balance Sheet: Free cash flow from the industrial business plummeted to 172 million EUR in the third quarter (previous year: 1,367 million EUR). Nevertheless, the balance sheet remains its strongest asset: EUR 31.0 billion in net liquidity corresponds to nearly 80% of the market capitalization. Investors have been witnessing for years how long such weak margins can keep a high-dividend stock down, as seen with BASF Aktie.
How high will the Mercedes dividend be in 2026 and 2027?
For 2025, Mercedes-Benz paid EUR 3.50 per share, which represents a yield of about 8.6% at the current price. In 2024, the dividend was still 4.30 EUR, and in 2023 it was as high as 5.30 EUR. The payout ratio was most recently around 66%. Based on an estimated earnings per share of 5.29 EUR, a dividend of just under 3.50 EUR would theoretically be possible again. However, this is not certain, as EBIT and cash flow are under pressure. Additionally, according to the CFO, a share buyback program of up to 1 billion EUR is underway through the 2027 annual shareholders’ meeting.
Mercedes Stock Price Targets and 2026 Forecast
Following the forecast revision, the average price targets from six analyst firms stand at 52.58 EUR, about 29% above the current price. Four firms recommend buying, while two remain neutral. Just how quickly expectations in the auto industry can shift is also illustrated by the Tesla Aktie.
Key price levels:
- 52-week high: 62.34 EUR (January 2026)
- Current price: 40.68 EUR (Xetra closing price on Oct. 30, 2026)
- First resistance level: 44.20 EUR
- Second resistance level: 47.98 EUR (buy signal only above this level)
- Critical support level: October low at 38.89 EUR; below that, 34.75 EUR and 31.20 EUR
Analysts’ price targets:
- Average price target: 52.58 EUR (six firms, October 27–30, 2026)
- JPMorgan: 70.00 EUR, Overweight (October 27, 2026)
- Deutsche Bank: 65.00 EUR, Buy (October 29, 2026)
- DZ Bank: 48.00 EUR fair value, Buy (October 30, 2026)
- Jefferies: 46.00 EUR, Buy (October 28, 2026)
- RBC: 44.00 EUR, Sector Perform (October 27, 2026)
- UBS: 42.50 EUR, Neutral (October 28, 2026)
Chart Analysis
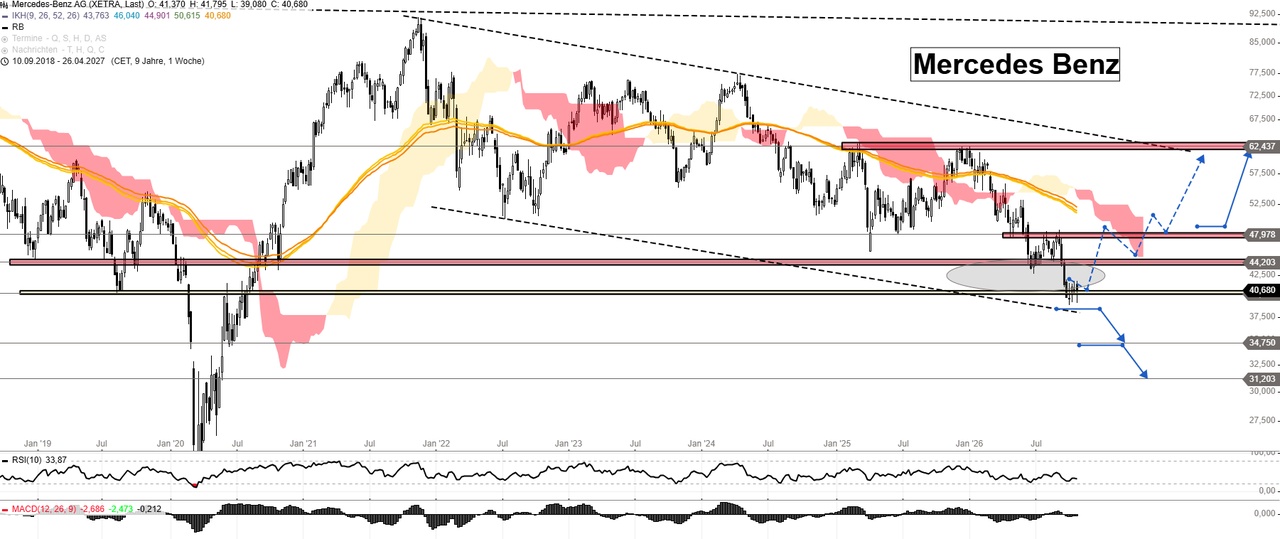
Since its high in early 2022, the Mercedes stock has been moving within an overarching downtrend and fell below the key support level of 44.20 EUR in September. On the weekly chart, the stock is currently in an interesting range around 40.68 EUR; however, a wait-and-see approach is advised. A classic buy signal would only emerge above 48 EUR—more precisely, above 47.98 EUR. If this occurs, the path toward 62.44 EUR would be clear. If, on the other hand, the price falls below the current monthly lows at 38.89 EUR, there is a risk of declines to 34.75 EUR and, in the broader trend, to 31.20 EUR.
Conclusion: Should you buy, hold, or sell Mercedes stock now?
My assessment: Wait and see. Mercedes stock is fundamentally undervalued, but it’s still too early to buy. The downward revision to the forecast indicates that the low point in the passenger car business has not yet been reached. On the other hand, there’s an 8.6% dividend yield, a P/E ratio of around 7.7, EUR 31 billion in net liquidity, and ongoing share buybacks—a solid foundation, but not yet a buy signal.
From a technical analysis perspective, a classic buy signal won’t emerge until the price rises above 48 EUR. If the stock falls below the October low of 38.89 EUR, it could drop to 34.75 EUR and, further down, to 31.20 EUR. Investors looking for stability rather than cyclicality among German blue-chip stocks should take a look at Telekom Aktie for comparison.
Opportunities
- ✅ Dividend of 3.50 EUR per share, approximately 8.6% yield
- ✅ 2026e P/E ratio of around 7.7, close to the 10-year average
- ✅ Net liquidity in the industrial sector: 31.0 billion EUR, nearly 80% of market capitalization
- ✅ Q3 beat expectations: Consolidated EBIT of 1.77 billion EUR (consensus: 1.6 billion EUR)
- ✅ Vans and Financial Services remain stable
- ✅ Average price target: EUR 52.58, approximately 29% above the current price
Risks
- ⚠️ Forecast lowered: Passenger car profit margin in 2026 only 2 to 3%
- ⚠️ Weakness in China: Passenger car sales down 8% in the third quarter
- ⚠️ Q3 industrial free cash flow only EUR 172 million
- ⚠️ Dividend has fallen from 5.30 to 3.50 EUR since 2023
- ⚠️ Overarching downtrend; buy signal only above 48 EUR
- ⚠️ Below 38.89 EUR, 34.75 and 31.20 EUR are potential targets
Sources
Mercedes-Benz Group: Ad hoc announcement dated October 27, 2026; Q3 2026 interim report; 2026 Annual Shareholders’ Meeting · Investing.com: Q3 2026 conference call · dpa-AFX: Ratings from JPMorgan, Deutsche Bank, DZ Bank, UBS, and RBC, as well as a report on the severance program · finanzen.net: Price targets · JESMB and ORF: Fiscal Year 2025 · MarketScreener: 2026 Earnings Estimate · Aktienfinder: Valuation and Fair Value · Stock3: Weekly Chart · Alpha Vantage: Xetra Price Data · Unsplash: Cover Image
What do you currently think of the $MBG? (+5,14%)


