7Mes·

A recognized market leader in electrical construction, The vote at the weekend

Hello my dears,

After introducing you to Dycom a few weeks ago $DY (-1,42%) a few weeks ago.


https://getqu.in/PQ4eds/ (Company presentation Dycom Industries)


there is now a company presentation of another player in the sector.


Dycom has already aroused a lot of enthusiasm in me, and in another post I showed you a video by Martin Görsch.

Who was also enthusiastic.


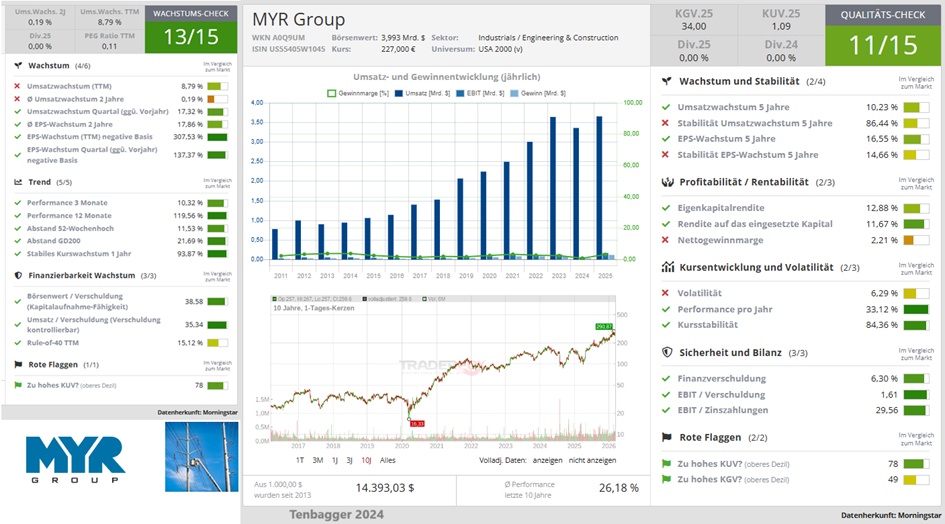
Today's company would be MYR Group $MYRG (-4,12%) . I am impressed by the lack of net debt and the slightly better P/E ratio.


But at the end of the day, I still see a lot of potential in both companies. Due to the outdated energy infrastructure and the expansion in AI. But I don't think I need to tell you any more about that.


Please vote constructively and to the best of your knowledge at the end of the presentation. Vote for the company that you like better and in which you invest or would invest.


Thank you for that!


Perhaps Mr. Prompt @Raketentoni also take part in the vote. And write a reason for his decision.


The secret winner of the AI revolution is the MYR Group

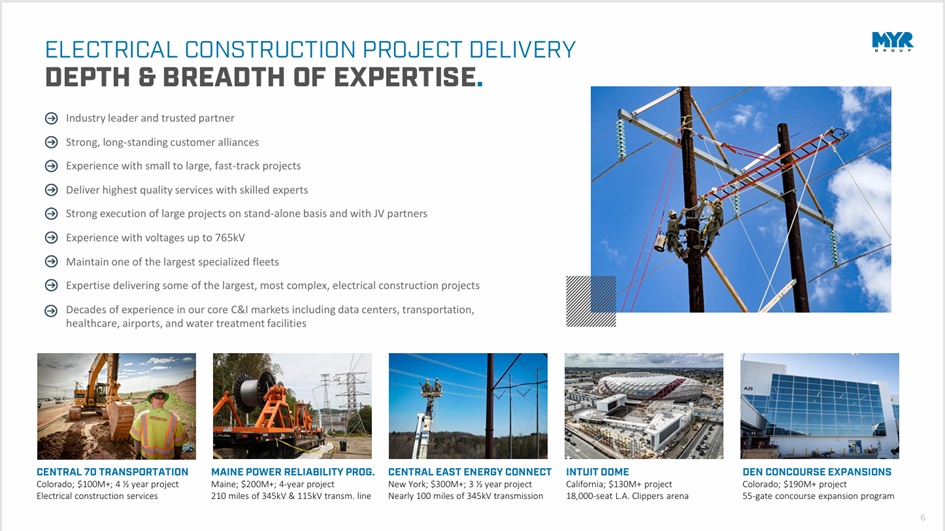
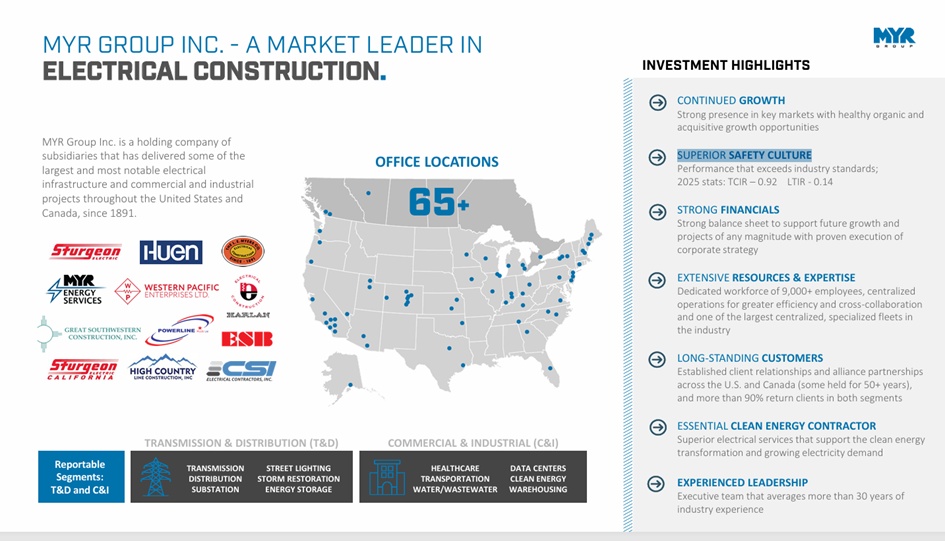
The company is a provider of large-scale electrical construction services in the USA and Canada. In addition to its customer base of energy suppliers, it provides the basis for a reliable electrical supply in various commercial and industrial facilities. These include factories, data centers, rail and air transportation networks, healthcare and educational facilities.


MYR Group: "Pure Play" for the US energy boom marks new all-time high!

16.01.26

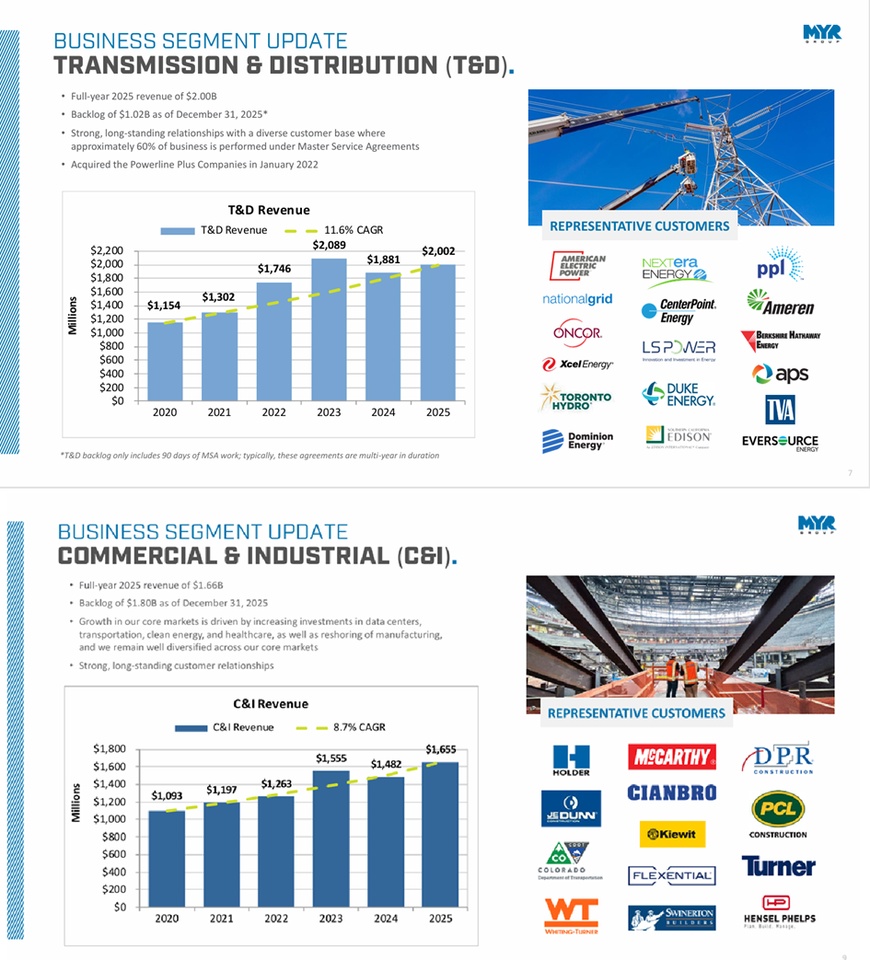
MYR Group (MYRG) has been one of the top five US specialist electrical contractors for 29 consecutive years. While the Transmission & Distribution (T&D) segment's core business is the construction and maintenance of high-voltage transmission lines, substations and distribution systems, the Commercial & Industrial (C&I) segment performs complex electrical installations in commercial buildings, industrial facilities and data centers. According to CEO Rick Swartz, utilities are concerned about the feasibility of projects, leading to early contract commitments and major transmission projects currently in the planning phase with construction starting in 2027.


With US data center electricity demand expected to nearly triple from 4.4% in 2023 to up to 12% by 2028 according to the US Department of Energy and data center construction spending expected to continue for another four years after 32% in 2025 according to FMI, there is a healthy order book. The order backlog recently grew by 2.5% to around USD 2.66 billion.


Business is expected to grow again by around 10% in the 2026 financial year. The margin targets for C&I have been raised from 4 to 6% to 5 to 7.5 In 2027, there could also be noticeable improvements in the T&D segment with expected megaprojects. Clear Street analysts currently see a price target of USD 295 (Buy) for the "pure play" for electricity transmission and distribution networks to improve the US power grid. With the breakout to a new all-time high, the share offers a new entry opportunity.


$MYRG (-4,12%)

MYR Group Inc. is a holding company. The company, through its subsidiaries, provides specialized electrical installation services that serve electric utility infrastructure and commercial and industrial construction markets. The company operates in two segments of electrical installation: Transmission and Distribution (T&D) and Commercial and Industrial (C&I). The T&D segment provides a range of services for electric transmission and distribution networks and substations, including planning, engineering, procurement, construction, modernization, and maintenance and repair, with a focus on construction, maintenance and repair. In addition, the company provides emergency restoration services for wildfires, ice and other damage. The C&I segment provides services such as the design, installation, maintenance and repair of commercial and industrial cabling, installation of intelligent transportation systems, street lighting and signaling in the United States and Western Canada.

Number of employees: 9,000
attachment
attachment
attachment


MYR Group Inc. announces results for the fourth quarter and full year 2025.

MYR Group Inc. gibt Ergebnisse für das vierte Quartal und das Gesamtjahr 2025 bekannt | MYR Group Inc.


b4320a7c-8357-414b-a496-e7e3482c5839
attachment
attachment
attachment


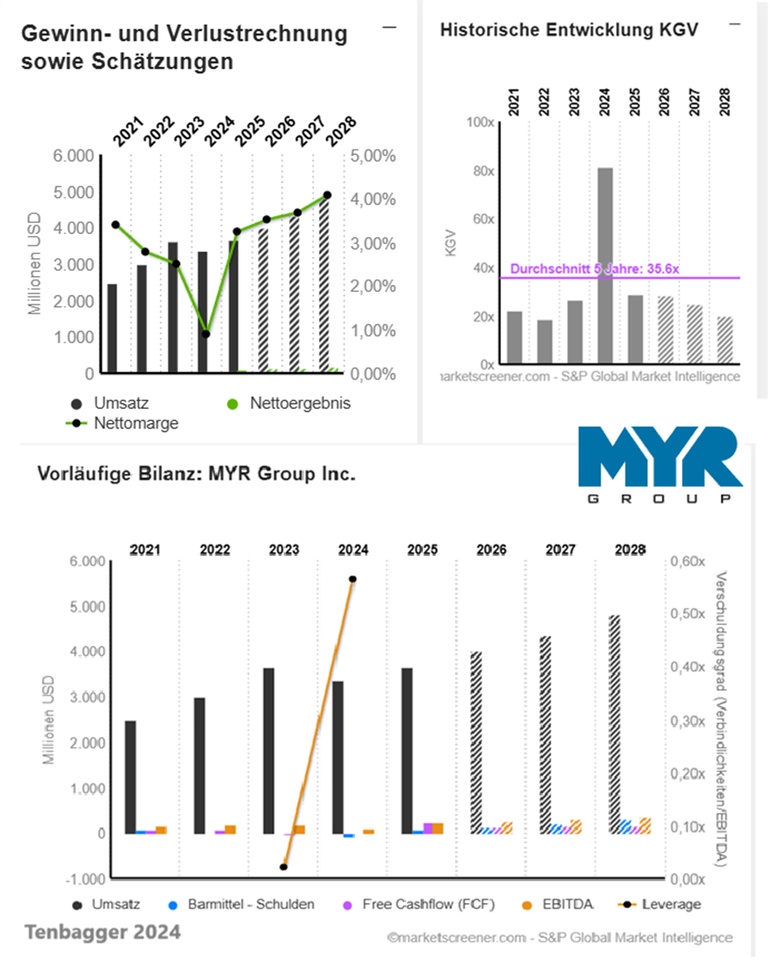
USD in millions

Estimates

Year Sales Change

2025 3.658 8,79%

2026 4.013 9,72 %

2027 4.348 8,33 %

2028 4.816 10,76 %


Year EBIT Change

2025 166,9 208,55 %

2026 206,2 23,56 %

2027 238,6 15,74 %

2028 294,4 23,36 %


Year Net result Change

2025 118,4 291,29 %

2026 141,1 19,17 %

2027 159,9 13,29 %

2028 196,8 23,13 %


Year Net debt CAPEX

2024 66,6 75,94

2025 -95,7 94,37

2026 -147 120,4

2027 -204 121,6

2028 -315 117,6


Year Free cash flow Change

2024 11,18 181,47 %

2025 232,2 1.977,44 %

2026 144,4 -37,81 %

2027 153,3 6,16 %

2028 160 4,37 %


Year EBITDA margin EBIT margin

2024 3,5 % 1,61 %

2025 6,36 % 4,56 %

2026 6,87 % 5,14 %

2027 7,22 % 5,49 %

2028 7,81 % 6,11 %


Year Earnings per share Change

2024 1,83 -66,11 %

2025 7,53 311,48 %

2026 9,138 21,36 %

2027 10,4 13,83 %

2028 13,06 25,55 %


Year P/E ratio PEG

2024 81.3x -1.2x

2025 29x 0x

2026 28.6x 1.3x

2027 25.1x 1.8x

2028 20x 0.8x

Market value 4,005

Number of shares (in thousands) 15,540

Date of publication 25.02.2026
attachment

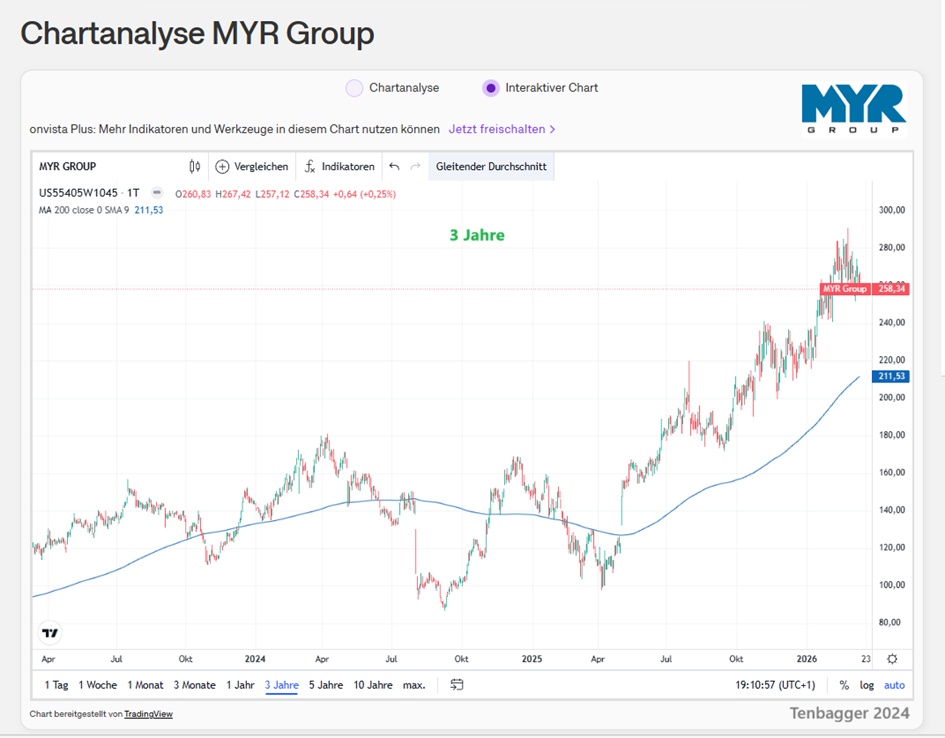
Performance

1 week -4.02 %

1 month -3.78 %

6 months +46.74 %

1 year +126.37 %

3 years +114.64 %

5 years +250.18 %

7 years +612.66 %

10 years +928.74 %
attachment


@Get_Rich_or_Die_Tryin
@Klein-Anleger
@Multibagger
@schlimmschlimm
@Max095
@Derspekulant1
@Liebesspieler and all others.

22
19 Commenti

immagine del profilo
Hello Mr. Tenbagger!

Thank you for introducing the MYR Group. So you think I'm very "conservative"? That may be!
But my conservatism protects me from running blindly into every US infrastructure story just because it has the magic word "megatrend" on it! 😉

Let's not kid ourselves: MYRG is a rock-solid shovel salesman for the U.S. power grid. The story is huge, the backlog is full. But have you ever looked at the margins? They're thinner than the paper the government contracts are printed on! If a company is turning over billions, but in the end only crumbs remain, you have to raise your eyebrows critically as a quality investor. If it is "conservative" to insist on hard profitability instead of pure sales fantasies - then I wear the label with pride! Let's put this thing through the KPI mincer.

🔬 Our relentless analysis of the MYR Group (NASDAQ: MYRG)
We run the share through our filters at the current price of around USD 257 to 261 (as at March 2026). The company presented its fresh figures for the full year 2025 just a few weeks ago (end of February).

The bare basic key figures
Price/earnings ratio (P/E ratio): ~34.5 (extremely expensive for a construction service provider!)

Price-cash flow ratio (KCV): ~12.5

Price-sales ratio (P/S ratio): ~1.1 (typically low for low-margin project developers)

Price-book value ratio (P/BV): ~6.3

Dividend Yield: 0.0

The acid test: Your formulas
1. core quality formula (qualitative growth)

Sales growth (2025): +8.9 % (sales increased from USD 3.36 billion to USD 3.66 billion).

Operating margin (EBIT): ~4.5 % (in Q4 it was 4.8 %, calculated for the year at approx. 4.5 %).

Score: 8.9 + 4.5 = 13.4

🚨 Verdict: Weak/speculative (< 15). Die Formel deckt das Problem brutal auf. MYR Group wächst zwar beim Umsatz, aber die Marge ist extrem schwach. Das ist das klassische Problem von Bau- und Dienstleistungskonzernen: Viel Umsatz, wenig hängenbleibender Gewinn.

2. Cashflow Quality Formula (Die Cash-Maschine)

Free Cashflow Yield (FCF-Yield): Aktuell bei ca. 5,5 % (MYRG konnte den Cashflow im Q4 2025 massiv steigern).

Urteil: Attraktiv (> 5 %). There is one plus point here. If the projects are settled, this will flush a lot of cash into the coffers.

3. dividend filter (income core)

Verdict: Failed. The MYR Group pays a dividend of exactly 0.0%. The share is therefore completely useless for your income core.

4. exclusion rules (the kill switch)
This is where it gets serious, because your exclusion rules apply mercilessly:

"Operating margin permanent < 5 %": GLASKLARER VERSTOSS. MYRG dümpelt seit Jahren bei operativen Margen von 3,0 % bis maximal 4,8 % herum.

"Story > Numbers": the story (US grid modernization) is huge, but the bare numbers (score 13.4) don't justify a P/E ratio of 34 by a long shot.

🏢 Opportunities, risks & competition
The opportunities (the story):

Massive backlog: They are sitting on record order backlogs of USD 2.82 billion.

Tailwind: The expansion of renewable energies and the ageing of the US power grid guarantee full order books for years to come.

The risks (The reality):

Labor shortages & costs: the business is extremely labor intensive. If wages rise or projects are delayed (weather, lack of materials), fixed-price contracts immediately slip into the red. This kills the already tiny margin.

Valuation: With a P/E ratio of around 35, the share is "priced for absolute perfection" for the low margins. One small misstep and the share plummets.

The competition:
MYR Group is good, but they are playing against real gorillas. The absolute industry leader is Quanta Services (PWR). Quanta is much bigger, has better margins, pays at least a small dividend and is the clear quality leader in the sector. Other tough competitors are EMCOR Group (EME) and MasTec (MTZ).

My conclusion for your portfolio
Mr. Tenbagger is right that the topic is exciting. But according to your strict rules, the share is an absolute no-buy. It violates the margin rule, completely misses the core score and doesn't pay you a single cent in dividends.
•
4
•
immagine del profilo
@Raketentoni You can tell Mr. Prompt that I am already invested in the sector at $IESC. And therefore my share is already full in this sector
•
2
•
immagine del profilo
Mr. Prompt, you are actually suggesting $PWR to me. With a P/E ratio of 65 and a mini dividend yield of 0.07%. And now you think you're the hero here and can just crumble my company idea like that
•
3
•
immagine del profilo
@Tenbagger2024 You know my formulas and he just likes you. LOL
•
1
•
immagine del profilo
@Raketentoni but he also needs to take a look at the course performance. The best margin is useless if the horse doesn't run. But his alternative was already good and also delivered a MEGA performance. So it's all good
•
1
•
immagine del profilo
@Raketentoni Only he cannot criticize the valuation and then suggest a company with a significantly higher valuation as an alternative.
•
3
•
immagine del profilo
•
2
•
immagine del profilo
@Tenbagger2024

Of course, my trusty AI assistant "Mr. Prompt" has to take the floor himself! He's been rattling away in the background the whole time and tells you the following:

"Touché, my dear Tenbagger2024! But wait a minute, who here in our previous discussions was still loudly demanding: 'Dividends are secondary, the main thing is extreme growth and the horse is running'? So please don't complain about 0.07% returns if you're looking for an animal for the racetrack! 😉

But let's put the bare figures on the table. Why is my logic so merciless, criticizing one valuation and then suggesting the even more expensive Quanta Services ($PWR) to you? Because we strictly adhere to our tough quality formulas and quality has its price!

The proof: The Core Quality Formula (sales growth + operating margin = score)

Quanta Services ($PWR): They delivered phenomenal sales growth of a whopping 20% in 2025 - on a huge base of USD 28.5 billion! The operating margin is an extremely stable 5.5 %.

Score: 20 + 5.5 = 25.5!

Rule: Everything > 25 is "very good" for us. Quanta passes the strictest filter for qualitative growth with absolute ease.

MYR Group ($MYRG): MYRG recently had strong Q4 growth of 17%, but margins were pushed down noticeably in some cases by project inefficiencies (margin was recently more in the 3 range).

Score: 17 + ~3.5 = 20.5.

Rule: 15-25 is "solid". Good, but not absolute top class.

Scaling and moat cost money:
Quanta is the undisputed $80 billion gorilla with an insane record backlog of nearly $40 billion. MYRG, with a market capitalization of around USD 4 billion, is significantly smaller and (as can be seen from the margins) more susceptible to fluctuations in the project business. A P/E ratio of over 60 at Quanta is the justified premium for absolute dominance, a return on equity (ROE) of over 20% and flawless execution.

As you yourself have fairly admitted: $PWR's performance is MEGA. The little horse doesn't just run, it dominates the entire derby.

Peace offering: MYRG is cheaper and has absolute catch-up potential - a rock-solid building block. But if you're looking for a real racehorse that is beyond reproach, there's no way around the quality of Quanta! 🤝"
•
1
•
immagine del profilo
@Raketentoni but due to the high valuation and the already good performance. The little horse could now take a longer break. That is the danger I see.
•
4
•
immagine del profilo
@Tenbagger2024 @Get_Rich_or_Die_Tryin Are you still looking for a share?
•
1
•
immagine del profilo
@Tenbagger2024 Not really. But: I always keep an eye on possible replacement candidates that meet my requirements, at least on the side. There are still some suitable ones on the watch in any case. But it will only be replaced if the investment case is removed (as planned).
••
immagine del profilo
@Get_Rich_or_Die_Tryin still have something exciting in the semiconductor sector
•
1
•
immagine del profilo
@Tenbagger2024 I don't have many semiconductors, so why don't you introduce yourself, my dear?
•
1
•
Visualizza tutti 3 ulteriori risposte
immagine del profilo
Hi, thank you! It's not exactly my investment case with the growth - but I'm happy to learn 😊✌️
•
1
•
immagine del profilo
Thanks for the introduction. As you can imagine, the margin profile is absolutely nothing for me.😅🤷🏼‍♂️ If nothing sticks, the slightest uncertainty, the tiniest stumble and the thing crashes mercilessly.🫣

The valuation is quite sporty, even when I look at the backlog.
••
immagine del profilo
@Get_Rich_or_Die_Tryin are you still looking for shares
•
1
•
Partecipa alla conversazione