Hi, everyone! ☕🍁
When the weather outside gets gloomy and we cozy up in the sunroom with a freshly brewed cup of coffee, that’s when our analysis computers really start to heat up.
As many of you know, I’m working with the lovely @Tenbagger-Capital and our @Dividendenopi put our heads together regularly.
Together with other resourceful sleuths here in the community, we’ve made it our mission to uncover new trends and sectors early on.
Why do we active folks go to all this trouble and spend nights poring over annual reports?
It’s simple: We want to feed this forum with real, well-researched facts, rather than just throwing the latest hype buzzwords at you.
Anyone can shout “AI” or “electricity demand” these days—but who really benefits in the end without their portfolio going up in flames?
That’s exactly why we’ve taken a ruthless look at the current boom sector surrounding energy, electrification, and data centers.
We’ve put five companies—all of which, at first glance, look like the perfect future winners—through our rigorous analysis.
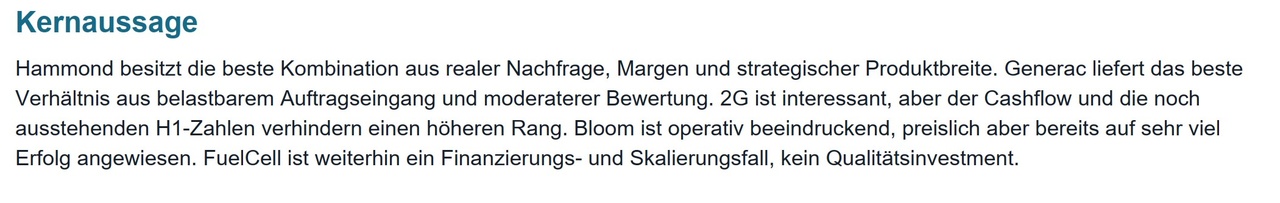
Here’s our showdown of the energy winners—and the result, which shows that revenue growth is by no means everything:
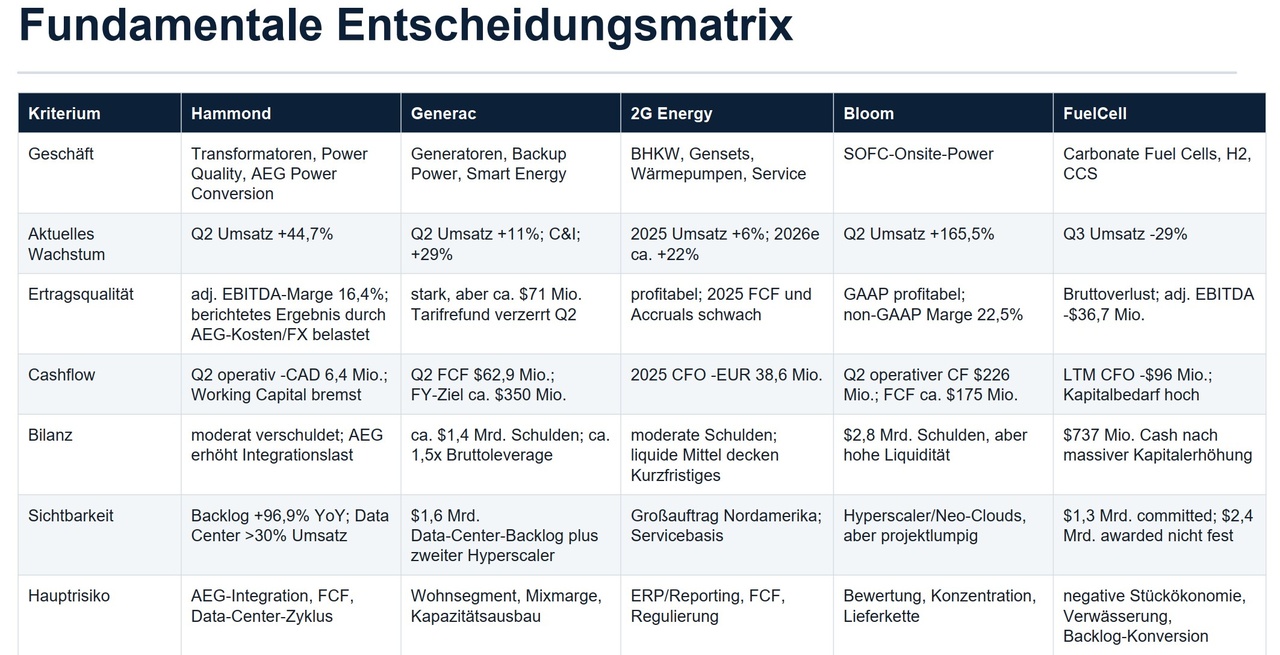
In the end, the ranking turned out as follows:
1. Hammond Power Solutions $HPS.A (+2,35 %)
Hammond delivered the most compelling combination overall. Particularly strong were its high revenue growth, its order backlog that nearly doubled, and its positioning in transformers, power quality, and data centers. At the same time, the company is already profitable and backed by solid results to a much greater extent than some of the more speculative candidates.
However, Hammond is not without its question marks. Operating cash flow has been weak recently, the integration of AEG still needs to run smoothly, and the now-high proportion of the data center business also increases cyclicality. Nevertheless, Hammond was the strongest candidate overall.
2. Generac $GNRC (-0,41 %)
Generac follows closely behind. Particularly positive factors include the rapidly growing commercial and industrial segment, the data center backlog of approximately $1.6 billion, and several hyperscaler contracts.
The key advantage over some other candidates is its valuation. Despite improved growth prospects, Generac is valued significantly more reasonably.
However, one had to look more closely at the most recent quarterly figures: Part of the sharp jump in earnings came from a one-time tariff refund. On a normalized basis, the margin looks somewhat less spectacular. Nevertheless, Generac remains a very interesting candidate due to its valuation, order backlog, and multiple revenue streams.
3. 2G Energy $2GB (-2,37 %)
2G Energy comes in third place. Its business model, centered on decentralized energy supply, gensets, combined heat and power (CHP) plants, service, and, increasingly, heat pumps, is fundamentally attractive. Added to this is a major North American data center contract that could drive significant growth in the coming years.
The main reason for its third-place ranking is cash flow. In 2025, operating cash flow was significantly negative, even though the company was profitable. Furthermore, the ERP transition and delayed reporting are currently complicating the valuation. Therefore, 2G remains an interesting prospect but must first confirm the expected jump in earnings and cash flow.
4. Bloom Energy $BE (-0,83 %)
Bloom is likely the most spectacular company of the five from an operational standpoint. Revenue growth recently exceeded 160%; at the same time, the company achieved quarterly revenue of more than $1 billion for the first time, along with positive operating income and strong operating cash flow.
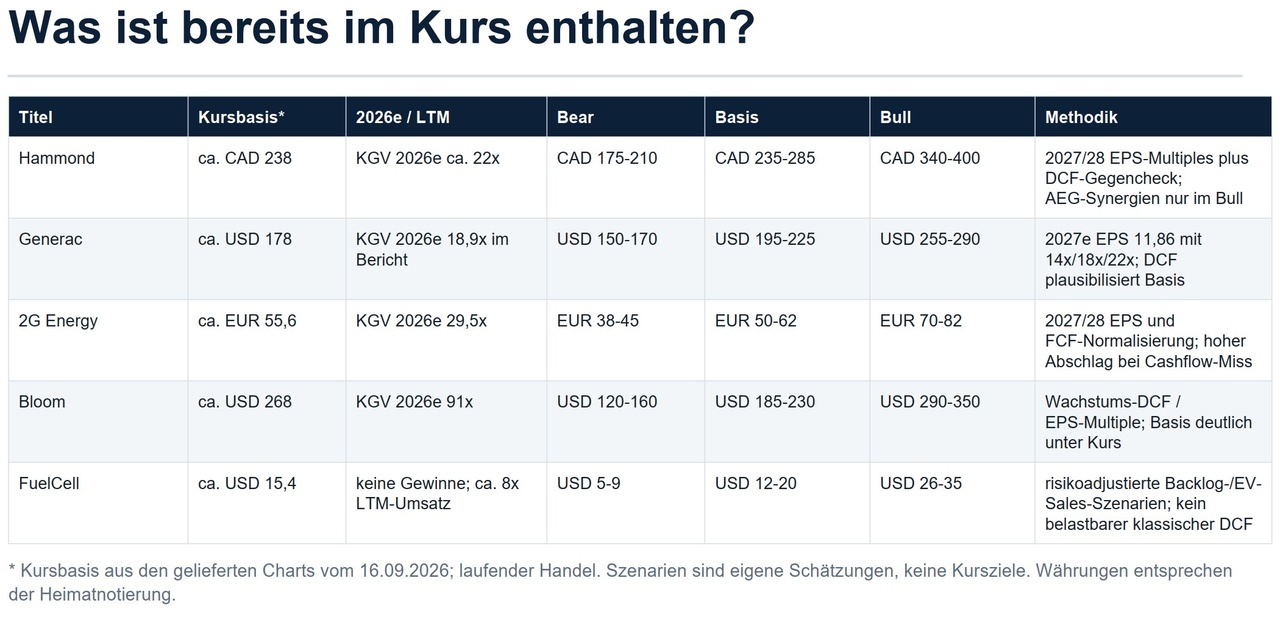
The problem isn’t the business itself, but the valuation. With an expected price-to-earnings ratio of around 91 and a stock that has risen several hundred percent within a year, a great deal of success is already priced in. Added to this are project concentration, supply chain risks, and high expectations for further scaling.
Bloom is therefore fascinating from a technological and operational standpoint, but it has a significantly smaller margin of safety compared to the first three candidates.
5. FuelCell Energy $FCEL (-0,82 %)
FuelCell Energy is clearly bringing up the rear.
The technology is interesting, and the company has relevant partners in Siemens and ExxonMobil. The pipeline and reported backlog also look impressive at first glance.
The problem, however, lies in profitability. Production continues to operate at a loss, capital expenditure is high, and a significant portion of the additional backlog is not yet binding. Added to this is significant dilution resulting from capital increases.
FuelCell must therefore first prove that technological demand can indeed give rise to a sustainably profitable business model.
Our Conclusion from the Comparison
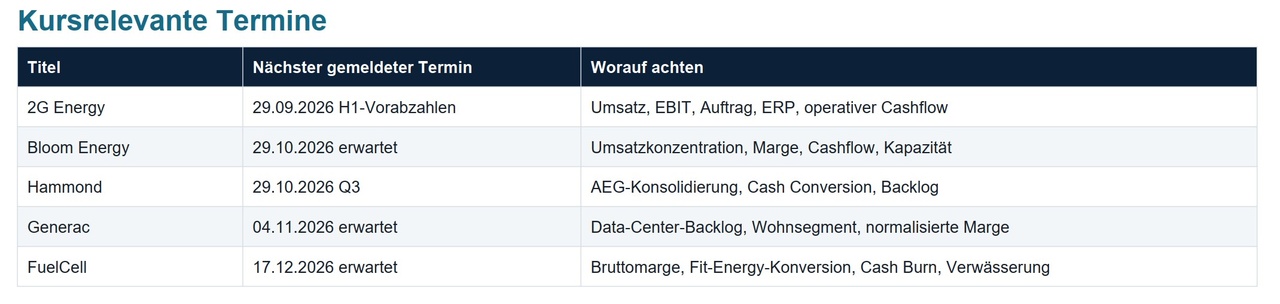
At first glance, all five companies appear to be set to benefit from rising electricity demand, electrification, and the data center boom. However, the comparison shows quite clearly just how different their quality and risk profiles actually are.
Hammond Power Solutions comes out on top in terms of the overall package of growth, profitability, order quality, and long-term electrification demand.
Generac is particularly impressive in terms of the balance between valuation and future order potential and trails only slightly behind.
2G Energy has an interesting industrial growth story, but still needs to prove that the expected growth spurt will translate directly into cash flow.
Bloom Energy currently has the most impressive operational momentum, but at the same time is also the candidate for which the market is already anticipating the most future success.
And as for FuelCell Energy , the story isn’t quite there yet. What’s missing here, above all, are positive unit economics, robust profitability, and lower capital requirements.
So, our final ranking is:
1. Hammond Power Solutions
2. Generac
3. 2G Energy
4. Bloom Energy
5. FuelCell Energy
What I found particularly interesting was that the company with the highest revenue growth rate doesn’t automatically rank first. Once valuation, cash flow, balance sheet, and execution risk are factored in, the picture shifts—in some cases, quite significantly. That’s exactly why the direct comparison of the five companies was quite revealing.