

Good morning, everyone,
It’s just amazing how well collaboration between users can work.
Even though there are unfortunately sometimes only a few comments on my presentations, behind the scenes, the exchange with key users is getting better and better.
Yesterday with Generac $GNRC (-0,2 %) you could clearly see that we had already analyzed exciting stocks ahead of a breakout.
With my last stock pick, Hammond $HPS.A (+2,35 %) it could be the same story,
(not an investment recommendation, just my personal opinion)
But the stock I’d like to introduce to you today was also discussed and analyzed among us beforehand. And sure enough, yesterday brought the good news we’d been waiting for.
Thanks to my friend @Raketentoni reminded me once again of this IPO stock, which I’d initially put on my watchlist because the IPO price was too high—and which I’d naturally lost sight of here.
Since the news triggered a great surge yesterday, I naturally brought @Dividendenopi jumped on board. I appreciate his expertise and foresight more and more.
And so it has been—and continues to be—a wonderful collaboration between the three of us.
“The Crazy Trio”
We look forward to plenty of comments on $INIO (+0,28 %) Innio
👉 The INNIO IPO took place in early June 2026, with the official pricing on June 4, 2026.
INNIO Stock: Major Order for U.S. Data Centers and Rating Upgrade Drive Share Price Surge
⚡ INNIO Stock –
- Date: September 17, 2026
- Key Takeaway: INNIO stock surged by over 12%, triggered by a major contract and a rating upgrade.
🔋 Major order
- INNIO received an order for 450 MW from a U.S. energy provider.
- Application: Containerized Jenbacher J624 gas engines for decentralized power supply to large data centers in North America.
- Delivery period: through 2028 → long-term revenue assurance.
💼 Rating upgrade
- Moody’s raised the company’s rating from B1 to Ba3 , outlook “positive”.
- Reason: conservative financial policy following NASDAQ listing (June 2026) and stable debt-to-equity ratio.
📈 Market Environment
- Positive sentiment on the U.S. stock markets (Nasdaq +1.6%, S&P 500 +1%).
- INNIO is benefiting from the AI boom and the rising energy demand for data centers.
- A combination of a new order, a rating upgrade, and market momentum led to a sharp rise in the stock price.
💡 Conclusion
INNIO is positioning itself as a a leading provider of decentralized energy solutions for AI infrastructure. The report points to sustainable growth potential and improved creditworthiness — a clear boost to investor confidence.
Innio NV is a Germany-based provider of decentralized energy solutions that supplies electricity. The company develops, manufactures, and maintains power systems under the Jenbacher and Waukesha brands. It supplies electricity for applications such as data centers, microgrids, grid stabilization, industrial power supply, and gas compression.
Number of employees: 5,467
As of December 31, 2025, INNIO has a global presence in approximately 100 countries, supported by a resilient, high-margin services business that generates long-term, recurring revenue throughout the entire equipment lifecycle. As demand for electricity accelerates—driven by AI, electrification, and grid constraints—INNIO enables scalable, behind-the-meter power generation with high efficiency, rapid startup capability, strong transient performance, and fuel flexibility, including hydrogen-compatible solutions.
INNIO plans a $300 million expansion of its Wisconsin facility, creating 500 jobs
⚙️ INNIO Expands Wisconsin Facility
- Date: August 19, 2026
- Investment: over $300 million
- New jobs: about 500
🔋 Goals of the expansion
- Expansion of engine assembly capacity in Waukesha, Wisconsinto meet rising U.S. demand.
- Construction of a new engine test facility (≈ 8,000 m²) and renovation of offices and workshops.
- Focus on decentralized energy solutions for data centers, power grids, and industrial facilities.
🏭 Location and Employment
- The campus covers 1.7 million ft², of which 890,000 ft² of production space.
- New jobs are being created in assembly, production, engineering, CNC machining, material handling, and maintenance.
- Waukesha remains the U.S. hub alongside the locations Trenton (NJ) and Waller (TX).
🌍 Company Profile
- INNIO develops and maintains power generation systems under the following brands Jenbacher and Waukesha.
- Headquarters: Munich, Germany
- Number of employees (as of the end of 2025): over 5,000 worldwide
- 💡 Conclusion
- The expansion strengthens INNIO’s U.S. presence and local value creation significantly. It positions the company as a key player in decentralized energy supply in the growing market for data center infrastructure.
INNIO’s First Annual Report: A Test of the Growth Story in the Data Center Market
⭐ INNIO – First Annual Report Following the IPO (Q2 2026)
Date: July 27, 2026 Source: Investing.com
📌 Key Takeaway
INNIO releases its first quarterly report as a publicly traded company . The report is seen as testto see whether the major growth story in the data center market is viable.
📈 Expected Results (Q2 2026)
- Earnings: $0.05 per share
- Revenue: $881.7 million
- Previous Quarter: Loss of $0.01 per share on revenue of $668.6 million → +32% sequential growth, significant operational improvement.
🔋 Strategic positioning
INNIO is benefiting greatly from:
- AI boom
- exploding electricity demand large data centers
- grid bottlenecks, which make decentralized energy generation attractive → Jenbacher & Waukesha engines are considered a readily available alternative to sold-out gas turbines (through 2028).
📦 Order Book & Backlog
- 2025 equipment orders: $3.88 billion (+188% YoY)
- Backlog Q1 2026: $4.8 billion (end of 2024: $1 billion) → Investors want to see whether this massive order backlog translates into revenue and margins .
🏭 Capacity expansion
- Production capacity is set to increase:
- 3.5 GW → 5 GW by the end of the year
- 10 GW by 2030
- Locations: Jenbach, Waukesha, North America (containerization) → Critical: Timelines, investment needs, production bottlenecks.
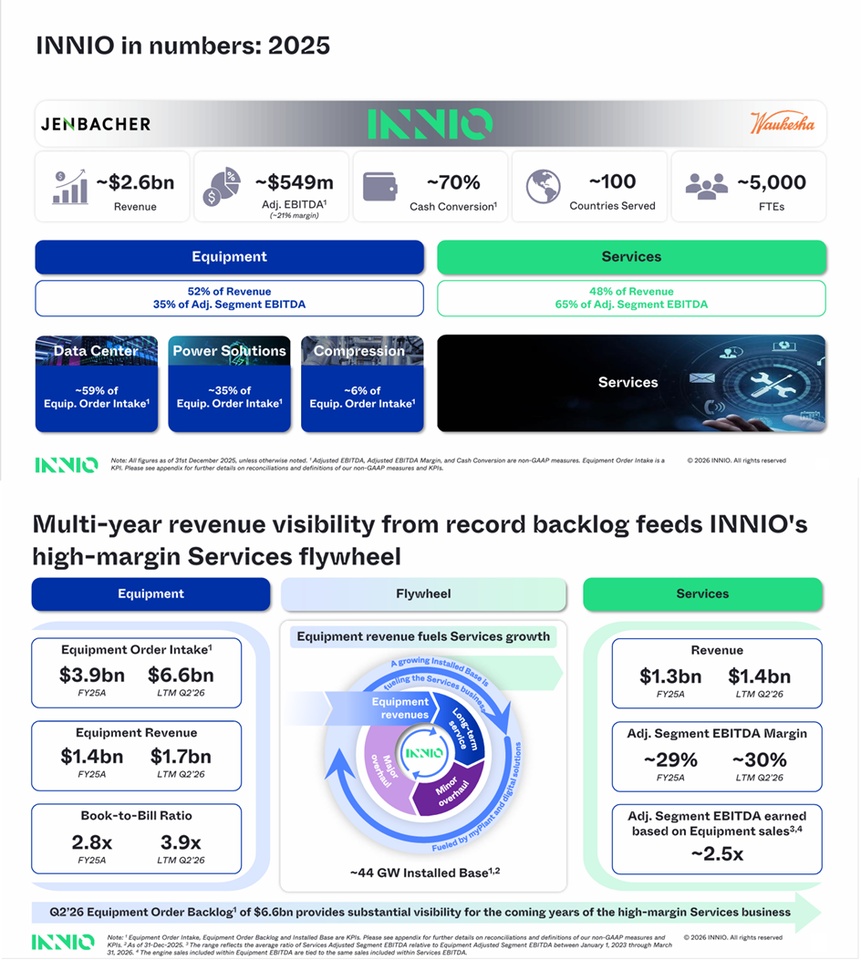
INNIO Q2 2026 Earnings Presentation
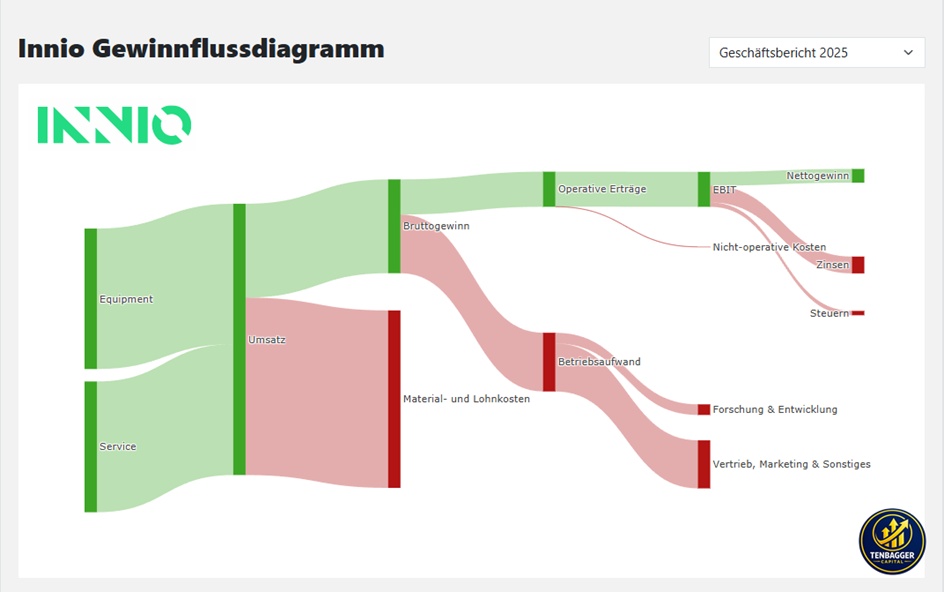
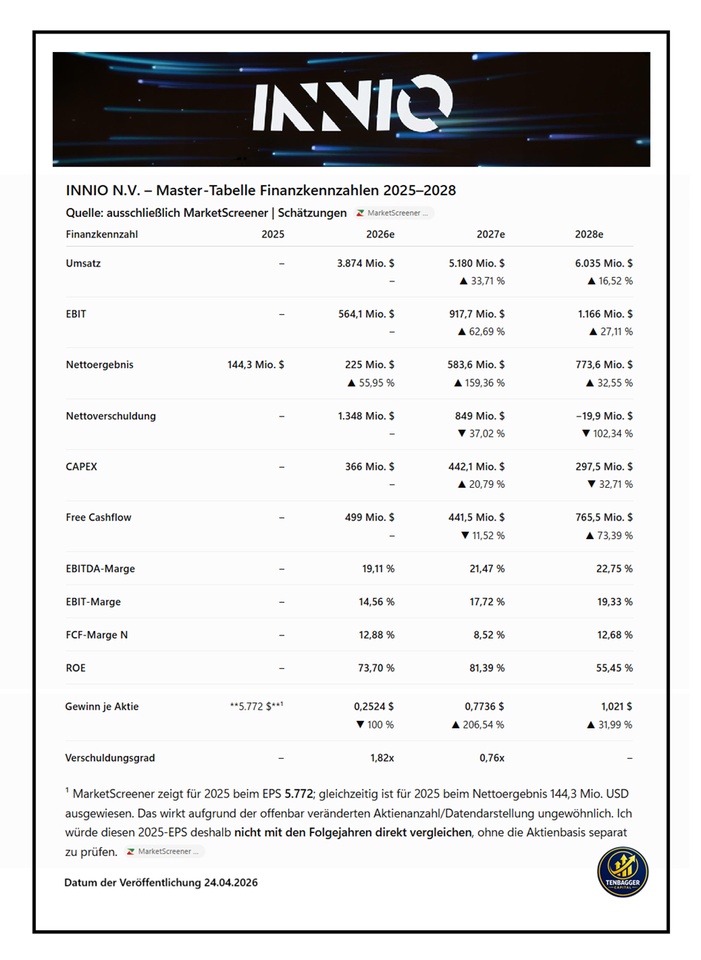
🔎 Development at a Glance
Revenue:
From 2026e to 2028e, revenue is expected to rise from $3.874 billion to $6.035 billion. This represents very dynamic growth, with the growth rate slowing from 33.71% to 16.52% .
Profitability:
The margin trend is particularly striking. The EBIT margin rises from 14.56% (2026) to 19.33% (2028), while the EBITDA margin rises from 19.11% to 22.75% .
Profit:
Net income is expected to rise from $225 million in 2026 to $773.6 million in 2028 . The biggest jump is expected in 2027, with +159.36% .
Debt:
According to the forecast, net debt will decline from $1.348 billion in 2026 to $849 million in 2027 and will even reach −$19.9 million —which would mean that INNIO would, on paper, achieve a net cash position.
Free Cash Flow:
In 2027, there will initially be a decline from $499 million to $441.5 million, before a significant jump to $765.5 million is projected for 2028. At the same time, CAPEX will fall to $297.5 million.
In short: MarketScreener’s estimates paint a scenario for INNIO through 2028 featuring strong revenue growth + significantly rising margins + rapidly growing profits + substantial debt reduction. The key points to watch here are, in particular, the realization of the high profit growth assumptions and the expected jump in FCF for 2028.
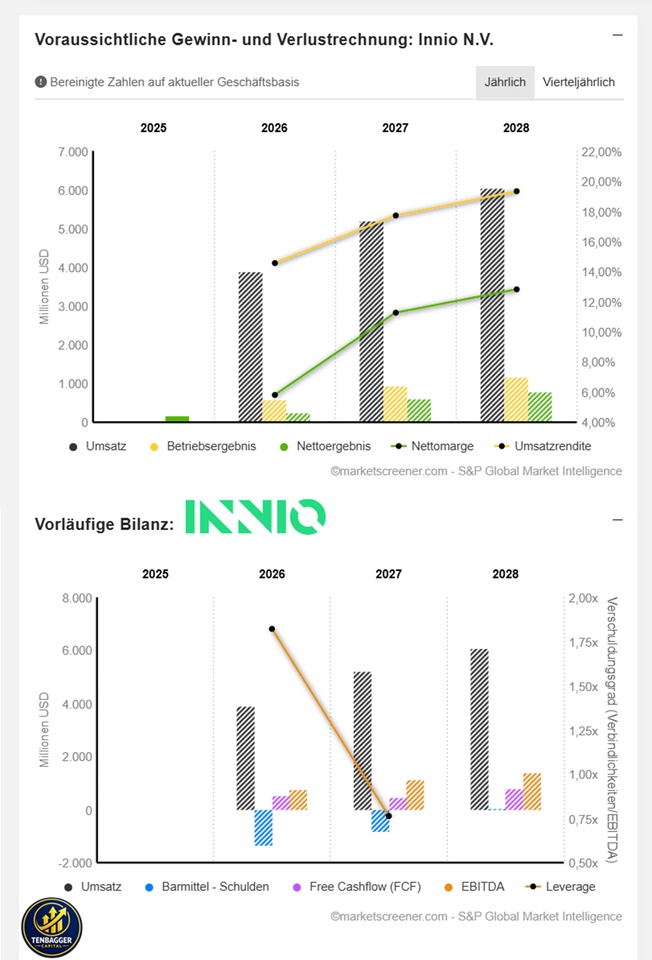
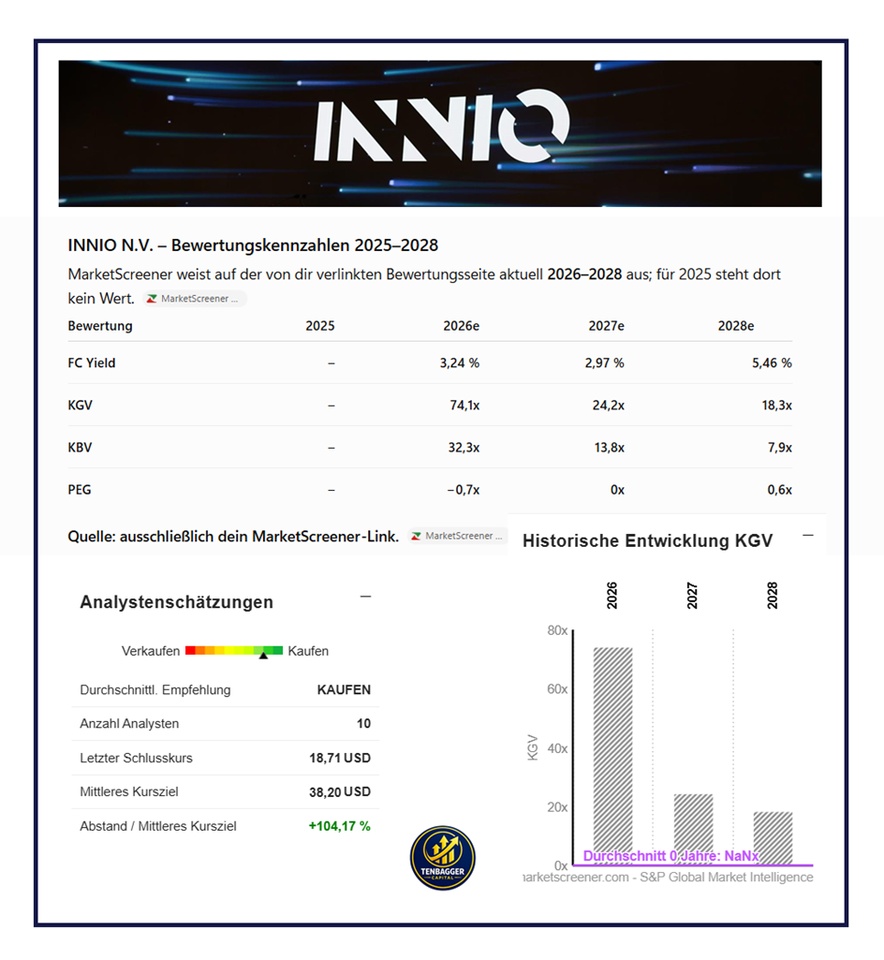
🔎 Performance
- FC Yield: 3.24% → 2.97% → 5.46%
P/E Ratio: 74.1x → 24.2x → 18.3x
P/B ratio: 32.3x → 13.8x → 7.9x
PEG: −0.7x → 0x → 0.6x
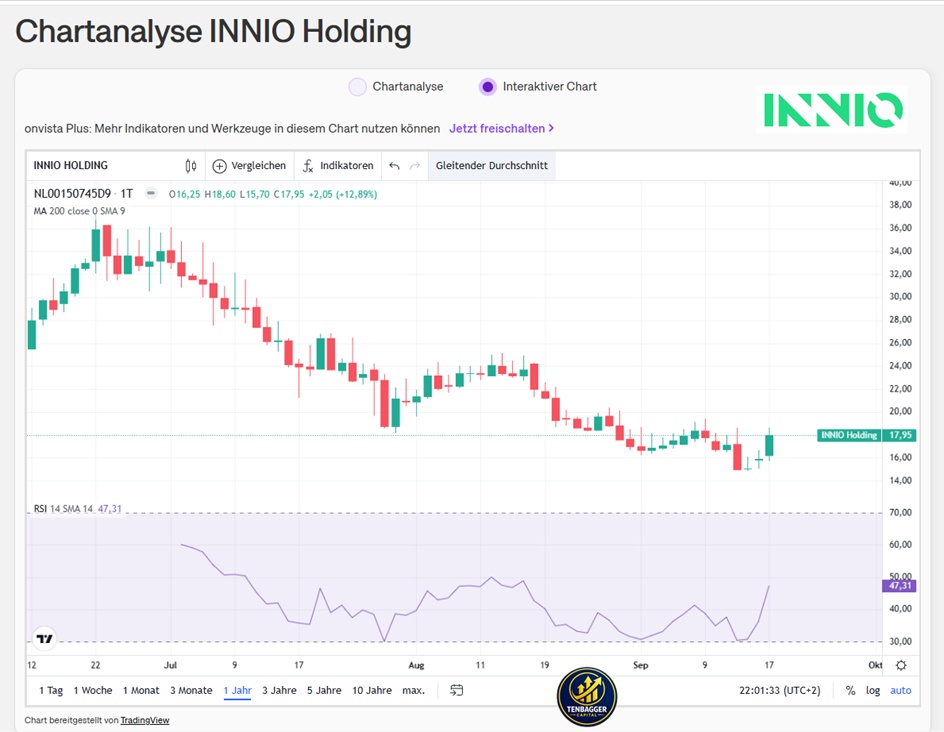
September 18, 2026, 8:55:05 a.m. •
Lang & Schwarz (EUR)
17.90 EUR


