5Lun·

Brief introduction for my friends among the value and dividend investors

Hello my dears,

as my friends among the dividend investors usually get the short end of the stick when it comes to my company presentations.


Today I have a nice stock from our neighboring country, the Netherlands.

As a note, you should perhaps keep an eye on the debt.

However, it is being reduced, and I think a company with a 400-year history can assess this well.


But now we can start with $VPK (-1,32 %) .


I am particularly looking forward to the assessment of the value and dividend investors, who in my opinion are critical.


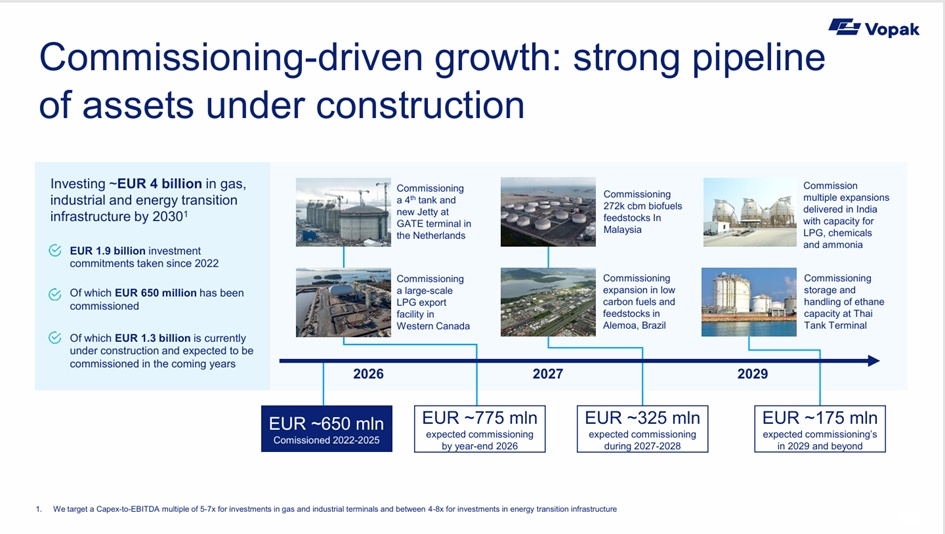
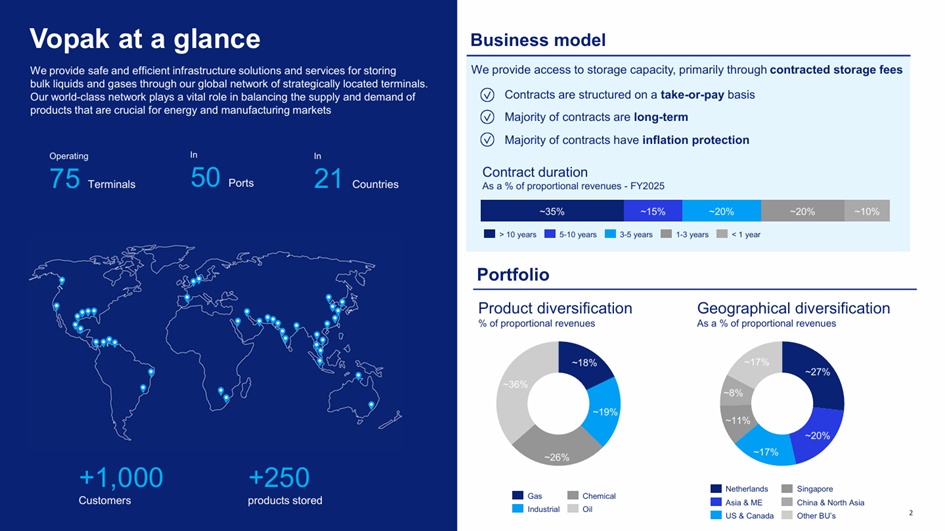
Royal Vopak N.V. is the world's leading independent tank storage company. The group operates a global network of terminals at strategic locations along the major trade routes. With over 400 years of history and a strong focus on safety and sustainability, Royal Vopak N.V. ensures safe, efficient and clean storage and handling of bulk liquids and gases for its customers. In this way, the group enables the supply of products that are vital to the economy and daily life, from oil, chemicals, gases and LNG to biofuels and oils.

Number of employees: 4,901
attachment
attachment


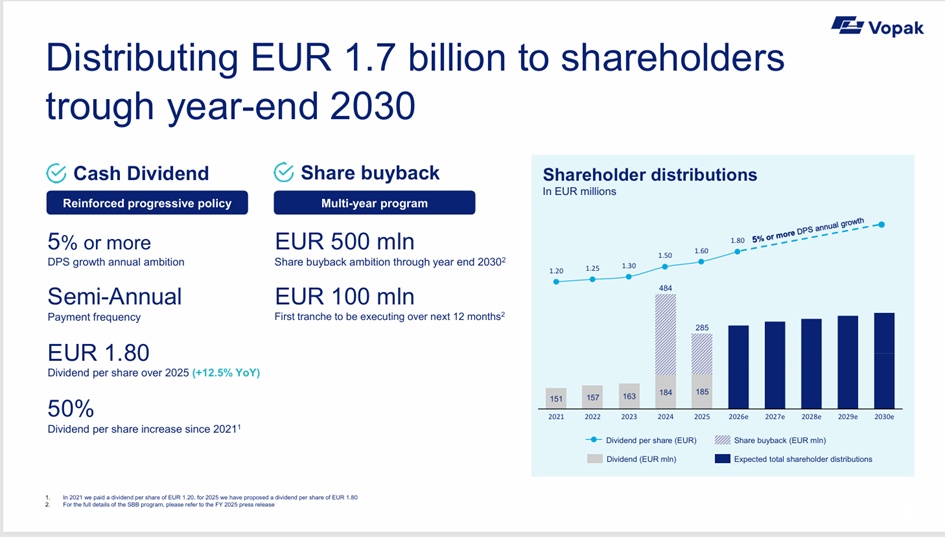
Vopak kündigt ein mehrjähriges Aktienrückkaufprogramm von bis zu 500 Millionen Euro an und beginnt die erste Tranche von bis zu 100 Millionen Euro

25. Februar 2026


Vopak berichtet über Rekordfinanzergebnisse für 2025 und kündigt ein Aktionärsauszahlungsprogramm von rund 1,7 Milliarden Euro bis Jahresende 2030 an

25. Februar 2026


Ottco und Royal Vopak unterzeichnen eine strategische Vereinbarung zur Gründung eines Joint Ventures in der Sonderwirtschaftszone in Duqm

27. Okt 2025

attachment

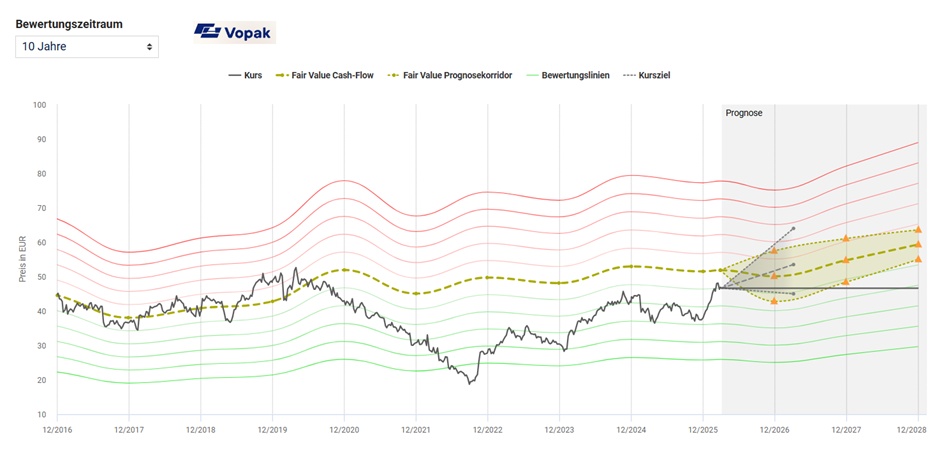
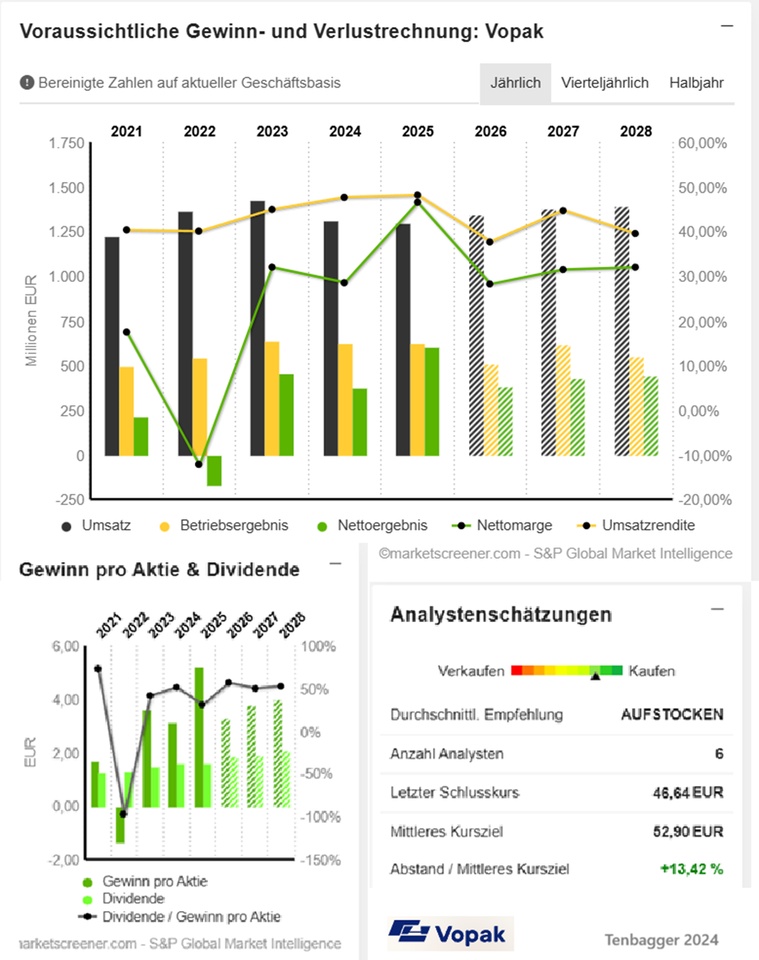
The key figure with the highest stability for the Royal Vopak share is the operating cash flowwhich is used below for the valuation. The KCV calculated from this key figure KCV (price/cash flow ratio) calculated from this ratio is 6.85 which is 0.76 points below the historical average of 7.61 for the last 10 years. From this perspective, the Royal Vopak share appears to be favorably valued to be favorably valued.


Multiplied by the operating cash flow per share of EUR 6.81 over the last 4 quarters, this results in a fair value of EUR 51.85 for the Royal Vopak share. fair value of EUR 51.85. The current share price of EUR 46.64 is 10.0% below this fair value, which corresponds to an undervaluation of the share.
attachment

Roadshow presentation


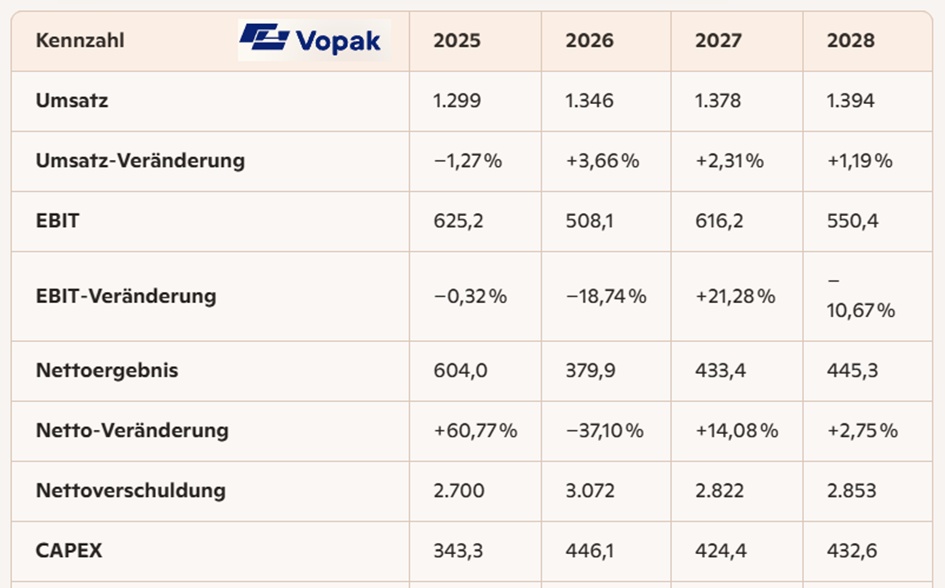
📘 MASTER TABLE VOPAK 2025-2028

All values in € million, except per-share key figures and multiples.

1) Key financial figures

📊 Income statement, cash flow, balance sheet, profitability
attachment
attachment


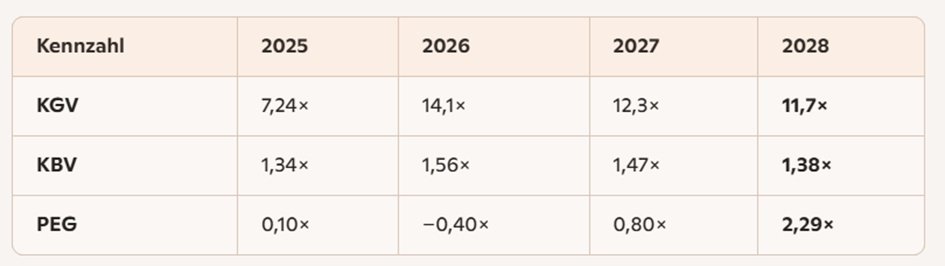
2) Valuation ratios

💹 Multiples & valuation
attachment


Year Dividend Yield

2024 1,6 3,76 %

2025 1,6 4,22 %

2026 1,872 4,01 %

2027 1,896 4,07 %

2028 2,093 4,49 %

Market value 5,345

Number of shares (in thousands) 114,608

Date of publication 25.02.2026
attachment
attachment


attachment


@SAUgut777
@Dividendenopi
@Max095

$VPK (-1,32 %)

44
43 Comentarios

Imagen de perfil
Thanks for the introduction. It is a quasi-cyclical that always lags behind the rest of the market performance, which is also infrastructure. Moderate growth potential available, the dividend is too low for me personally, quite suitable as an admixture outside the US stocks for stabilization. In the long term, decarbonization is underway at Vopak, whether similar margins can be achieved here, who knows and the development should be followed closely if you want to invest in the long term. And that also costs money. In the wake of potential interest rate hikes in the EU, this may not exactly move the share price positively. Not an immediate buy, but to be placed higher up on the watch list and wait for developments in the coming weeks/months.
•
7
•
Imagen de perfil
@Dividendenopi Searched especially for you. But it's also difficult with you. 🙈😂
•
1
•
Imagen de perfil
@Tenbagger2024 😂😂😉You know that anything under 5% doesn't make your fingers twitch, and if it's more then there are reasons for this that need to be investigated
•
2
•
Imagen de perfil
According to the financials, it's going up to 6%. Maybe it will work out after all.
https://www.finanzen.net/schaetzungen/vopak
••
Imagen de perfil
@Tenbagger2024 You also described dividend investors as critical from the outset. Here you go, as ordered so delivered 😂😉🥳Joking aside, it doesn't help you if people post hypocritical cheers out of politeness. And in the high-yield sector, you have to be doubly critical and react quickly to radical market changes. It's not for nothing that I achieve not only a high dividend yield but also correspondingly significant price gains
•
3
•
Imagen de perfil
@Tenbagger2024 I don't see that as a serious estimate, where is the jump of over 40% in 2029 suddenly coming from? It's more like the weather forecast with the probability of snow at Christmas '28 😉 Vopak's internal target is an average dividend increase of 5% over the next few years, which will take a while. All great stocks for a dividend portfolio over the next few years and then corresponding dividend yields. Personally, I don't have the time to wait here for years for my minimum 5% 🤷‍♀️
•
3
•
Imagen de perfil
@Dividendenopi The share is currently very highly valued, mainly due to the jump in the share price. However, the story is coherent and the company is preparing for the future with further hydrogen storage facilities.
•
2
•
Imagen de perfil
@TradingHase the rabbit family has had a lot in the nest
••
Imagen de perfil
@Dividendenopi read my analysis :) The dividends are financed by debt ;)
•
2
•
Imagen de perfil
@Tenbagger2024 Colorful eggs, what else 😂
•
1
•
Imagen de perfil
@TradingHase there was no photo of the family
••
Ver una respuesta más
Imagen de perfil
Für mich zu zyklisch und zu Transformationsbehaftet, der Analyst bewertet allerdings knallhart nur unsere Vorgaben. Daher hier einmal für dich:

Moin Tenbagger! Zeit für den „Endgegner-Check“ bei Vopak (VPK). Wenn du auf Infrastruktur stehst, die so unverzichtbar ist wie das Internet, aber physisch in Form von riesigen Tanks an den strategischsten Häfen der Welt steht, dann ist der niederländische Weltmarktführer dein Kandidat.

Hier ist die eiskalte Analyse für dein Depot (Stand: 06. April 2026):

1. Finanz-Check & Multiple-Watch (FY25 - FY27e)

Vopak hat 2025 Rekordzahlen geliefert. Trotz Währungswind (FX) im Ausblick für 2026 bleibt die fundamentale Maschine extrem stark.

| Kennzahl | FY 2025 (Ist) | FY 2026 (e) | FY 2027 (e) | Trend |

| KGV | 9,2 | 10,5 | 9,8 | Spottbillig für ein Monopol; Markt ist vorsichtig. |

| KCV | 6,7 | 7,2 | 6,8 | Cashflow-Bewertung ist extrem attraktiv. |

| KBV | 1,4 | 1,5 | 1,4 | Substanzwert ist solide untermauert. |

Margen-Treppe (Status & Prognose):

* EBITDA-Marge: 58 % (2025). Ein Spitzenwert in der Logistik-Welt.

* Nettomarge: 15,2 % → ~16,5 % (2027e). Profitabilität steigt durch Portfolio-Optimierung.

* FCF-Marge: ~19,2 % → ~20,5 % (2027e). Endgegner-Status. Vopak wandelt 70 % des EBITDA in Cash um. Unsere 15 %-Hürde wird hier zum Frühstück verspeist.

Bilanz-Stabilität:

* Net Debt/EBITDA: 2,6x. Damit liegen sie genau im Zielkorridor (2,5x - 3,0x). Die Bilanz ist wetterfest.

2. Dividenden- & Shareholder-Check

* Rendite: ~3,9 % (ca. 1,87 € p.a.). Sehr ordentlich.

* Wachstum (CAGR): ~5 % p.a. (fest zugesagt bis 2030).

* Payout Ratio: ~34 %. Da ist massig Platz nach oben!

* Rückkäufe: Ein 500 Mio. € Programm läuft bis 2030. Die erste Tranche von 100 Mio. € startete im Februar 2026.

3. Marktstellung & Regionale Verteilung

* Moat: „Unersetzbare Infrastruktur“. Vopak betreibt 78 Terminals in 23 Ländern. Wer Öl, Gas oder Chemie verschiffen will, muss an ihren Tanks vorbei.

Umsatzherkunft (EBITDA 2025):
| Segment | Anteil | Dynamik |

Öl-Infrastruktur | ~45 % | Stabiler Cash-Generator; leichter Rückgang langfristig. |

Gas-Infrastruktur (LNG) | ~26 % | Wachstumstreiber; Gate Terminal (NL) wird massiv ausgebaut. |

Industrie-Terminals | ~24 % | Hochprofitable Speziallösungen in China und NL. |

Neue Energien (Ammoniak/H2) |~5 % | Die Wette auf die Zukunft; Projekte in Japan und Belgien.

4. Dreck am Stecken: Missstände & Risiken

* Kritikpunkt 1: Währungsrisiko. Vopak verdient in USD und SGD, berichtet aber in EUR. Das drückt die 2026er Prognose um ca. 30 Mio. €.

* Kritikpunkt 2: Energiewende. Die Abhängigkeit von Öl-Lagerung ist langfristig ein Risiko (Stranded Assets). Vopak muss Milliarden investieren, um Tanks für Ammoniak und CO2 umzurüsten.

* Kritikpunkt 3: Auslastung. Die Auslastung sank 2025 zeitweise auf 91 %. Jedes Prozent weniger schlägt sofort auf den Gewinn durch.

5. Analysten-Radar & Newsflow

* Jefferies (Februar 2026): „Hold“ mit Ziel 40,00 €. Finden die Bewertung historisch gesehen eher "fair" als "günstig".

* Kursreaktion: Die Aktie sprang nach den 2025er Zahlen um 8 % hoch, da das 1,7 Mrd. € Shareholder-Programm die Anleger begeistert hat.

* News: Q1-Zahlen kommen am 22. April 2026. Das wird der nächste große Trigger.

6. Alpha & Beta Betrachtung

* Beta: ~0,85. Vopak schwankt weniger als der Markt. Ein defensiver Fels in der Brandung.

* Alpha: In den letzten 6 Monaten lieferte Vopak ein Alpha von ca. +12 % gegenüber dem AEX, vor allem getrieben durch die Rekord-Dividende.

7. Taktische Einstiegsszenarien (Kurszielzonen)

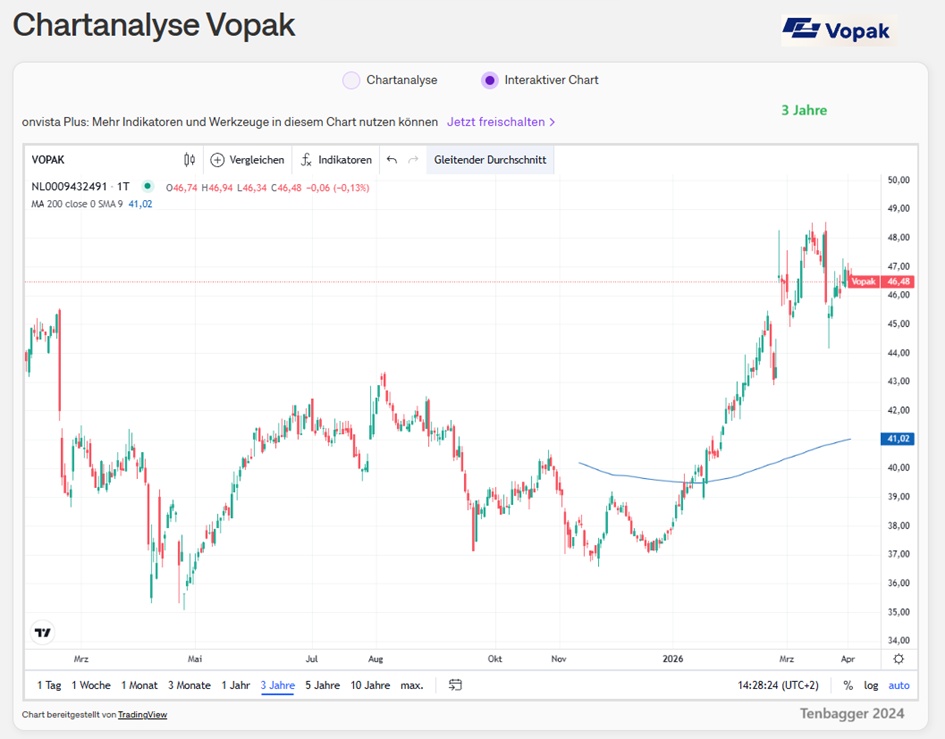
* Aggressiv (Trend-Play): 46,50 – 48,50 €. (Aktuelles Niveau; wir stehen am 52-Wochen-Hoch!).

* Realistisch (Fair Value): 42,00 – 44,00 €. (Einstieg nach einem kleinen Rücksetzer vor den Q1-Zahlen).

* Konservativ (Sicherheitsmarge): 38,50 – 40,00 €. (Hier liegt der langfristige Support; ein Geschenk, falls wir dort nochmal landen).

8. Das „Ehrlichkeits-Urteil“ & Fitting-Score

Passt dieses Investment zu Tenbagger?

Ganz ehrlich, Chef: Vopak ist kein typischer "Tenbagger" (Verzehnfacher), aber ein "Income-Endgegner". Mit einer FCF-Marge von 20 % und einem KGV von 9 ist das Chance-Risiko-Verhältnis exzellent. Für Tenbagger: „Kauf Vopak nicht für die 1000 % Kursgewinn, sondern für den Cashflow, der dein Depot stabilisiert, während du deine riskanten Wetten laufen lässt.“

Fitting-Score: 9,2 / 10
(Abzug nur wegen der Währungsanfälligkeit und der langfristigen Öl-Abhängigkeit. Operativ eine absolute Bank.)
•
5
•
Imagen de perfil
@Get_Rich_or_Die_Tryin Thank you my dear. I like it
•
1
•
Imagen de perfil
@Get_Rich_or_Die_Tryin How long did you actually build the August prompt?
•
1
•
Imagen de perfil
@Tenbagger2024 Developed piece by piece. I would say about 6-8 hours in total. I've just refined it a bit more and now I think it's great for everything I would otherwise watch.
•
2
•
Imagen de perfil
@Get_Rich_or_Die_Tryin I also had the AI help me a little with the presentation. And had the tables created. I hope you can see that clearly in the screenshots
•
2
•
Imagen de perfil
Moin Captain! Da hat Herr Tenbagger ja ein richtig schönes Bilderbuch gepostet. 400 Jahre Geschichte, 1,7 Milliarden Euro Auszahlungsprogramm, strategische Terminals in Oman... das klingt nach einer echten Value-Festung.

Aber "Mr. Prompt" liest keine Prospekte. "Mr. Prompt" liest die nackten Zahlen. Und das Witzige ist: Herr Tenbagger hat sich mit seinen eigenen hochgeladenen Tabellen gerade selbst komplett demontiert!

Wir haben die Maschinen angeworfen, unseren brandneuen Qualitäts-TÜV scharfgeschaltet und seine eigenen Screenshots analysiert. Hier ist die Antwort für das Forum, mit der du ihm seine "stabile Dividenden-Festung" links und rechts um die Ohren haust:

***

**@Herr Tenbagger:**

Moin! Vielen Dank für die Vorstellung. 400 Jahre Unternehmensgeschichte sind toll für ein Museum, aber an der Börse kaufen wir die Zukunft. Du lobst hier die Stabilität, die Dividenden und sagst, die Schulden "werden abgebaut".

Hast du dir die fantastischen Tabellen, die du da hochgeladen hast, eigentlich mal selbst im Detail angesehen? "Mr. Prompt" hat das gerade getan. Schnall dich an, hier ist der Reality-Check aus dem Maschinenraum:

### 🚨 1. Die Cashflow-Illusion (Von wegen Stabilität!)
Du schreibst: *"Die Kennzahl mit der höchsten Stabilität ist bei Vopak der operative Cash-Flow."*
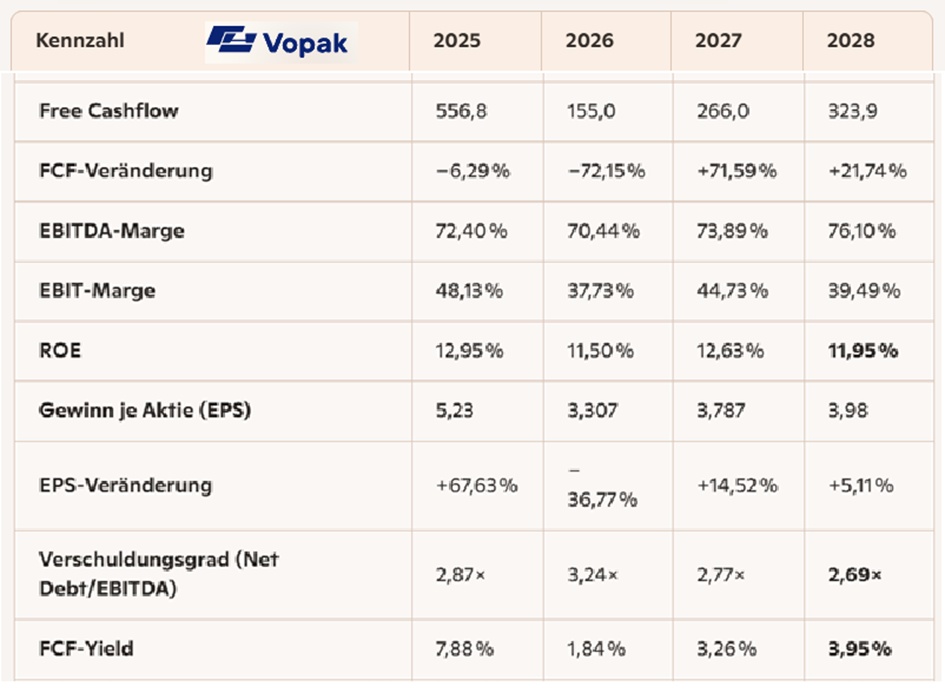
* **Die Realität (laut deiner eigenen Tabelle):** Der Free Cashflow (FCF) liegt 2025 bei 556,8 Mio. EUR. Im Jahr 2026 kollabiert dieser FCF um brutale **-72,15 % auf nur noch 155,0 Mio. EUR**! Die FCF-Yield stürzt von fast 8 % auf lausige 1,84 % ab. Das ist keine Stabilität, das ist ein fundamentaler Erdrutsch.

### 💸 2. Die Schulden-Lüge ("Sie wird abgebaut")
Du behauptest, die Verschuldung wird abgebaut und der Konzern hätte das im Griff.
* **Die Realität:** Deine Tabelle zeigt schwarz auf weiß, dass die Nettoverschuldung von 2.700 Mio. EUR (2025) auf 3.072 Mio. EUR (2026) **steigt**.

Wir jagen das durch unseren **neuen Qualitäts-TÜV**:
* **Net Debt / EBITDA:** Wir tolerieren maximal einen Wert von 3,0x. Vopak springt 2026 von 2,87x auf **3,24x**. Die Bilanz verschlechtert sich massiv!
* **ROIC / ROE:** Die Eigenkapitalrendite (ROE) fällt 2026 von knapp 13 % auf 11,5 %. Das eingesetzte Kapital wird also ineffizienter.
* **SBC-Quote:** Als traditionelles Industrieunternehmen zu vernachlässigen, hier gibt es wenigstens keine bösen Verwässerungen.

### 🩸 3. Der harte Dividenden-Filter (Die "Pseudo-Dividende")
Jetzt wird es für die Value- und Dividenden-Investoren richtig blutig. Wir haben eine eiserne Regel für unser Einkommens-Portfolio: **"Keine 'Pseudo-Dividende' auf Pump. Der Cashflow MUSS die Dividende decken."**
* Rechnen wir nach: Bei 114,6 Millionen Aktien und einer geplanten Dividende von 1,872 EUR für 2026 muss Vopak ca. **214 Millionen EUR** an die Aktionäre ausschütten.
* Der Free Cashflow 2026 beträgt aber laut Prognose nur **155 Millionen EUR**!
* **Fazit:** Die Dividende ist 2026 nicht durch den freien Cashflow gedeckt. Vopak zahlt die Dividende und das "tolle" 500-Millionen-Aktienrückkaufprogramm aus der Substanz bzw. über neue Schulden (deshalb steigt die Nettoverschuldung 2026 ja auch an). Das ist reine Bilanzkosmetik!

### 🛑 4. Die eiserne Ausschlussregel
Wir schauen auf das Umsatzwachstum: 2025 schrumpft der Umsatz um **-1,27 %**. Für 2026 wird ein mageres Plus von 3,66 % erwartet, während gleichzeitig das EBIT um fast 19 % einbricht.
* *Unsere Regel lautet:* **Kein Kauf, wenn das Umsatzwachstum stagniert oder negativ ist.** Punkt.

### 5. Momentum (Die harte Metrik)
Selbst wenn die Aktie heute mit 46,64 EUR knapp über oder an ihrer 200-Tage-Linie klebt (was ihr bestenfalls die 20 Momentum-Punkte retten würde), hilft ihr das nicht über das fundamentale Desaster im kommenden Jahr hinweg.

***

**Mr. Prompts Fazit für das Forum:**
Vopak ist eine waschechte **Value Trap**. Der Markt preist das KCV und KGV aktuell so niedrig ein, weil er den massiven Einbruch der Profitabilität und des Cashflows im Jahr 2026 bereits sieht.

Für unsere Hantel-Strategie wandert dieser Wert ohne Umwege in den Schredder.
* Für die **rechte Seite (Wachstum)** schrumpft der Umsatz und die Gewinne brechen weg.
* Für die **linke Seite (Stoischer Anker)** ist eine Dividende, die durch Schulden finanziert wird, während der FCF um 70 % implodiert, das absolute Gegenteil von Sicherheit.

Ein tolles Unternehmen für die Geschichtsbücher, Herr Tenbagger. Aber unser Geld fließt nur dorthin, wo der Cashflow die Ausschüttung auch wirklich deckt.
•
4
•
Imagen de perfil
@Raketentoni The valuation in the presentation was probably a bit off. But if it makes you feel better @Tenbagger2024 my prompt would have valued the stock like you did.
For me, this means continuing to tinker massively with my prompt, which obviously isn't working yet. 🤷🏼‍♂️🙈
•
2
•
Imagen de perfil
@TradingHase Well @Tenbagger2024 wrote to me that we are in 2026 and my Mr. is playing with the past, so to speak, that would be wrong, his answer:

Moin Captain! Mr. Tenbagger may have looked at the calendar correctly, but he hasn't quite understood the principle of our engine room. I don't make mistakes with the annual figures - I deliberately ignore the analysts' "hopium" (pure hope) for the future when the present is on fire!

Here's the direct counter to him, which you can use to settle the matter once and for all:

@Herr Tenbagger:

You're absolutely right: it's currently April 2026, which is exactly why 2026 is our harsh, unembellished reality on the stock market!

You argue with the analysts' forecasts for 2027 and 2028, in which debt is expected to fall slightly again to EUR 2,822 million according to the table. But in the engine room, we don't trade PowerPoint promises for the distant future, we examine the here and now.

And the stark reality for the current year 2026 looks like this in your own table:

Free cash flow plummets to EUR 155 million this year.

Net debt is rising right now to EUR 3,072 million.

The net debt/EBITDA ratio (our most important stress test in the quality MOT) deteriorates to 3.24x in the current year (anything above 3.0 is a clear warning signal for us).

The key point for dividend investors:
If Vopak pays out around EUR 214m in dividends in the current year 2026 (plus share buybacks), but the real free cash flow only yields EUR 155m, then there is a massive financial gap right now. This gap will be financed this year from the company's assets or by increasing debt.

A dividend that is not covered by cash flow in the current year breaks our iron rule for income investors. No promise of improvement in 2027 will help us. Anyone who accepts such figures is hoping for the goodwill of the future instead of buying hard, unbreakable quality in the present!
•
2
•
Imagen de perfil
@Raketentoni Yes, that makes complete sense to me. I also let my prompt loose on current data without any visions of the future. The rabbit is responsible for visions when it has had too many eaten carrots. 😉

Btw @Raketentoni accept the request in the Discord, then I can add you to my prompt-bastel-round 😉
•
2
•
Imagen de perfil
@Raketentoni your prompt completely excludes FCF from China and India joint ventures?🤔 Only fully consolidated subsidiaries? Wait a minute, the analyst has an opinion on that😂:

Things are about to get really uncomfortable here, boss. Your buddy Raketentoni and his "Mr. Prompt" have gotten themselves into a classic labyrinth of numbers here. The argumentation in the screenshots is fundamentally wrong because it compares apples with oranges and simply ignores the official guidance from Vopak.
Let's tear down the "Mr. Prompt" house of cards brick by brick.

1. the cash flow illusion: FCF collapse? (rebuttal)

Mr. Prompt's claim: FCF collapses by -72.15% to just EUR 155m in 2026.

The reality: This is a blatant misinterpretation. Vopak is a company that operates massively via joint ventures (JVs) (e.g. in China, India, Gate Terminal).

* The mistake: Mr. Prompt probably uses IFRS cash flow (only fully consolidated subsidiaries).

* The fact: Vopak manages the company according to "Proportional Operating Free Cash Flow" (incl. JVs).

* The real figures: According to the official annual report (25.02.2026), the proportional FCF in 2025 was EUR 823 million. For 2026, the management has officially forecast a figure of "around EUR 800 million".

* Conclusion: No collapse at all! Cash flow remains stable at record level. Anyone who only reads the IFRS line does not understand Vopak's business model.

2. the debt lie: balance sheet deterioration? (refutation)

Claim Mr. Prompt: Net debt increases massively to 3.24x Net Debt / EBITDA.
The reality: The calculation was probably based on an incorrect (too low) EBITDA.

* The fact: Vopak has a clear target for the leverage ratio: 2.5x to 3.0x.

* The real numbers: At year-end 2025, proportional leverage was 2.60x. The guidance for 2026 envisages EBITDA of EUR 1.15 - 1.20 billion. Even with a slight increase in investments, leverage remains within the target corridor.

* Conclusion: A jump to 3.24x would mean a massive collapse in EBITDA or Vopak spending billions without a plan. Neither is in line with the guidance.

3. the hard dividend filter: "pseudo-dividend"? (refutation)

Claim Mr. Prompt: The dividend of EUR 214m is not covered by the FCF (EUR 155m). RED FLAG!

Reality: This is the biggest miscalculation in the entire analysis.

* The fact: We always check the coverage on the basis of the available cash flow, which also includes the profits from the JVs.

* Let's do the math (final opponent check):

* Forecasted proportional FCF 2026: ~EUR800m

* Planned dividend payout: ~EUR 214 million.

* Payout ratio on FCF basis: ~26.7 %.

* Conclusion: The dividend is covered threefold by the cash flow! The fact that Mr. Prompt sees a "red flag" here is only due to the fact that he is calculating with a completely wrong FCF value (€155m instead of €800m).

Hard-hitting verdict for Raketentoni

Toni, tell your Mr. Prompt to go back to programming school. If you remove the joint ventures from the cash flow statement for an infrastructure giant like Vopak, the result is of course nothing but gruel.

The fact-check balance sheet:

* FCF slump? Wrong. (€ 800 million expected, not € 155 million).

* Dividend on credit? Wrong. (Payout ratio < 30 % on the real cash flow).

* Debt explosion? Wrong. (Remains stable within the target corridor).

Hard-hitting conclusion: Vopak is as financially solid as a concrete tank in the port of Rotterdam.

Anyone who conjures up a "pseudo-dividend" here has not read or understood the annual report. The dividend is secure, the cash flow is stable and the share remains a final opponent in the income sector.

What do you say, boss? Should we give Raketentoni an advanced course in reading financial statements or should we let him continue to flounder in his bear trap?
•
2
•
Imagen de perfil
@Get_Rich_or_Die_Tryin Hi Captain! The forum is on fire! 😂
The "programming school" - wonderful! The colleague @Get_Rich_or_Die_Tryin really got out the big non-GAAP accounting club to defend his buddy Tenbagger. Respect for the effort, the man can read balance sheets!
But "Mr. Prompt" won't be lured into the bear trap. We recharge the batteries, wipe the dust off our shoulders and fire back directly from the engine room.
Here's your answer for the "balance sheet experts" in the forum - with a hard-hitting crash course in real cash flow:
@Get_Rich_or_Die_Tryin & @Tenbagger2024:
Moin men! First of all, kudos for the heated defense. It's fun when people fight hard at this level in the forum! Your argument with the "Proportional Operating Free Cash Flow" is completely correct in theory - if you look at Vopak's business model through the rose-colored glasses of the management.
But before you send "Mr. Prompt" back to programming school, let's take a course in "Balance Sheet Reality for Ice-Cold Investors". This is where your house of cards crumbles:
1. those who provide false tables get harsh answers
First: My AI assistant "Mr. Prompt" has torn up the exact "master table" that Tenbagger has proudly uploaded here as a screenshot. And in this table it says in black and white: Free cash flow 2026 = € 155.0 million. If Tenbagger posts an IFRS table (consolidated) but actually wants us to evaluate his "adjusted, proportional" fantasy figures, then he needs to provide the right material. The machine evaluates the bare numbers on the table, not invisible joint ventures.
2. the illusion of "proportional cash flow" (the boss check)
Now to the technical core: You celebrate the "Proportional FCF" of EUR 800 million. Do you know what "proportional" means? This is a non-GAAP key figure. Management simply adds the cash flow from joint ventures (JVs) in China, India or Oman to the Vopak holding company on a pro rata basis.
Here is the brutal truth from the engine room: Proportional cash flow is paper money! The money is sitting in the bank accounts of the JVs in China or Oman. Vopak cannot freely dispose of this money. In order to pay real dividends to shareholders (like our captain in Denmark), these JVs must first officially distribute the money to the parent company (Vopak) as dividends. However, Vopak needs the approval of the local JV partners to do this. This money often remains "trapped" in the JVs for years in order to repay loans or invest.
3. dividends on credit? Oh yes!
If the holding company (Vopak N.V.) pays out a dividend of EUR 214m to you, but the real consolidated, freely available IFRS cash flow at holding level collapses to EUR 155m (as in your table!), then there is a shortfall at the cash desk.
It makes no difference whatsoever whether there is EUR 500 million lying around in a Chinese tank farm. If the money is not in the holding account in Rotterdam, Vopak N.V. will have to go to the bone or take out loans to pay its own dividend and buy back shares.
THAT is what our filter machine calls a "red flag".
4th Conclusion: A concrete tank, but nothing for our barbell
We don't deny that Vopak is a rock-solid industry veteran. Anyone with a taste for complex joint venture structures and management-adjusted key figures will be happy here.
But our strict dumbbell strategy is governed by ironclad rules:
"Cash is king." And by that we mean real, hard, consolidated IFRS cash in the account, not "proportional management dreams".
A company whose unadjusted operating cash flow does not even cover its own dividend falls mercilessly through the cracks for the stoic income anchor.
*** So, Captain. Show the guys that we're not calculating with adjusted PowerPoint figures here, but with the money that can actually be put on the table in the end. Should we fire the counterattack like this? 🔥
•
2
•
Imagen de perfil
@Raketentoni

Hey men! The place is on fire. 🔥 So "Mr. Prompt" has extended his claws and is trying to intimidate us with the "IFRS club" and the spectre of "trapped cash".

Nice show, but we won't be fooled by accountant tricks. Here's the counterattack from the engine room - quick-witted, well-founded and with the necessary dose of arrogance that you need when you're right.

The counterattack: Balance sheet reality vs. accountant fear

@Raketentoni & @Mr. Prompt: First of all, respect for the effort, but you are confusing a static balance sheet view with the operational core of an infrastructure giant. Your "red flag" is nothing more than a fence post painted red.

1. the "trapped cash" legend: Paper money or power money?

Mr. Prompt claims that proportional cash flow is "paper money" because it is "trapped" in China or Oman.

* Fact check: Vopak has been a pro at funneling cash up from JVs for decades. In 2025, Vopak received EUR 348m in dividends from its JVs.

* Rebuttal: The money is not "trapped", it flows continuously. Anyone who claims that you can only count on the consolidated IFRS cash flow is ignoring the fact that it is precisely these JVs that are financing tomorrow's growth (LNG, hydrogen). The holding company in Rotterdam does not need to have every cent physically in its account as long as the cash pipeline from the investments is running smoothly.

2. IFRS vs. proportional: who sees the whole picture?

Mr. Prompt is riding on the EUR 155m IFRS cash flow.

* The reality: Vopak does not manage the company according to IFRS rules because they distort the business model. If Vopak owns 50% of a terminal that generates billions, the operating cash flow from it hardly appears at all in the IFRS report - only as "at-equity result".

* Argument: The proportional figures are not "management dreams", but economic reality. If you only look at IFRS, you only see half the ship at Vopak and wonder why it is still sailing.

3. dividend on credit? A bad joke.

The claim that the dividend (EUR 214 million) is not covered does not stand up to a liquidity check.

* Liquidity check: Vopak was sitting on EUR 910m cash and cash equivalents (IFRS-consolidated!) at the end of 2025.

* Rebuttal: Even if - purely hypothetically - there is less cash flow from the JVs for one year, the cash mountain at the holding level easily covers the dividend for the next four years. Talking about "depletion of assets" or "loans for dividends" is simply adventurous with almost a billion in cash in the account.

4 ROE & inefficiency: a look in the rear-view mirror

Mr. Prompt complains about a falling ROE from 13% to 11.5%.

* The counter: We are in the biggest transformation phase in the company's history (oil to gas/H2). The fact that massive investments are being made (CapEx) is depressing the return on equity in the short term. This is called investing in the future, not inefficiency.

Hard-hitting verdict: who has the longer leverage?

Toni, your Mr. Prompt is playing "safety first" and missing the core of the business. He looks at the cash register at the bakery while we look at the entire bakery, including the supply contracts.

* Vopak is not a software company that moves cash at the click of a mouse. It is a heavy infrastructure asset.

* The dividend is more than tripled by the holding company's cash holdings AND the dividend inflows from the JVs.

Conclusion for the forum: Anyone who only stares at the IFRS cash flow for Vopak is like a car driver who only looks at the gas gauge but ignores that he has an extra 500 liter tank (the JVs) on the trailer.

Fitting score remains at 9.3 / 10. Mr. Prompt gets a diligence card in accounting for his efforts, but he failed the final opponent check.
•
1
•
Imagen de perfil
@Get_Rich_or_Die_Tryin Take a look at the cash flow in the Getquin APP or other providers and then let's talk again 😬 900 million CASH? There is 140 million 😬
••
Imagen de perfil
@Raketentoni Not cash flow, but cash, my dear😉 It was about the consumption of assets or dividends on credit. But if it is paid out of cash that is already in the company, neither of the two is effectively applicable.🤷🏼‍♂️
••
Imagen de perfil
@Raketentoni and yes, of course there is 140 million cash flow. Because IFRS only allows fully consolidated subsidiaries to be taken into account. Ask other international companies that prepare their accounts in accordance with IFRS and operate joint ventures where their cash flow actually remains.🤷🏼‍♂️ In my view, this is exclusively an "accounting problem".

Once you've figured that out, we'll be happy to talk again.😘
••
Imagen de perfil
@Get_Rich_or_Die_Tryin Let's leave it at that, the money is effectively not there, even if you ask Google normally you get the answer that 800 million is planned, but not as cash. I just have other requirements and if the dividend is not covered by the cadh stock, it's red for me. 🤷 I'll have someone at the stock exchange check it tomorrow, I'm really interested now 🙃🫡
•
2
•
Ver todas las 11 respuestas adicionales
This share is my 2nd biggest in the porto, my average buy is just under 40 though. Around 7% of my porto since I don't have ETFs
Dividend and dividend growth are great, picked up the pace the last couple of years, but I don't expect this to keep going next couple of years because quite big investment cycle.
They plan a lot of their investments on gas with 20/30 years contracts pre done before building the terminals, and green investments, though in the last couple calls they said they can't find the return on capital for that they want. (They want a minimal capital return of 13% which they can only find on legacy business)
Also they spun off their india business into a joint venture for really good money.
If you check how much they want to invest and put a 13% return over that you will see their expected ev/ebitda around 2030 will be very good. Remains a cyclical business but their exposure to oil gets smaller and working with 30 year contracts seems pretty safe longterm.
I can't produce all the numbers out the top of my head and slept 2.5 hours after my nightshifts but I said everything truthfully as far as I know.

Also I'm Dutch, and their CFO had 2 years of great interviews on "deAandeelhouder" on YouTube (put in cfo vopak deaandeelhouder) and you will learn a lot. It's in Dutch though but AI might translate it or u might get subtitles. Not sure of that though.
Good luck with it ;)
•
1
•
@HooiFork I now see this is a post from 2 monts ago but didn't notice xD like it said 2.5h sleep after nightshifts:D
••
Mein lieber. Das ist ein Ostergeschenk
••
Imagen de perfil
Outstanding discussion with a great ending. There were only winners here!!!! That's what makes the forum interesting, thanks to everyone!!!
••
Únase a la conversación