
The photon is the fundamental building block of our universe. See how it is used for generation, modulation, amplification, steering, and detection in the data center, communications, and industrial markets.
Hello, everyone,
Amazon, Alphabet, Microsoft, and Meta are maintaining their high capital expenditures. This continues to play into the hands of infrastructure stocks.
Marvell’s interest in Lumentum shows just how strong the interest in photonics companies is.
I’m going to hold onto Lumentum for now and wait out the next few trading days.
I had already classified Lumentum under the motto “Tenbagger stays in the portfolio.” I won’t abandon this long-term perspective because of short-term takeover rumors.
Should Marvell actually make a very attractive offer, I would reassess the situation.
My main thought: In my 2036 portfolio, I don’t just want to hold takeout speculations—I want companies that will benefit from the wave of investment in AI infrastructure.
And Lumentum could very well be one of them.
But the company I’m introducing to you today could also fit that description.
It’s a company that’s no stranger to many of you, either.
Despite my investment in Lumentum, I don’t rule out buying into Coherent. This would give me a second foothold in the sector in case Lumentum is acquired.
What do you think of my plan?
Before the earnings report on November 4 or after it.
Coherent could benefit from a Lumentum acquisition.
A deal for Marvell to acquire Lumentum would be positive for Coherent, as both companies operate in the same industry. Both manufacture lasers, optical transceivers, and network components that enable data to be transmitted at extremely high speeds using light signals instead of electrical ones.
The main difference between the two is that Coherent has a broader, vertically integrated portfolio, while Lumentum focuses more on specialized optical components, high-power lasers, and optical switching systems. In fact, Lumentum attempted to acquire Coherent some time ago.
Depending on the premium Marvell pays, there is a good chance that investors will use it to value Coherent. In fact, data shows that Coherent is already a more affordable alternative to Lumentum. It has a price-to-earnings ratio of 25, compared to 40 for Lumentum.
Coherent also benefits from Lumentum in other ways. In a recent statement, Lumentum explained that its products are sold out through 2029. Such a move means that many companies will turn to Coherent for these optical solutions.
Coherent’s Business Is Thriving
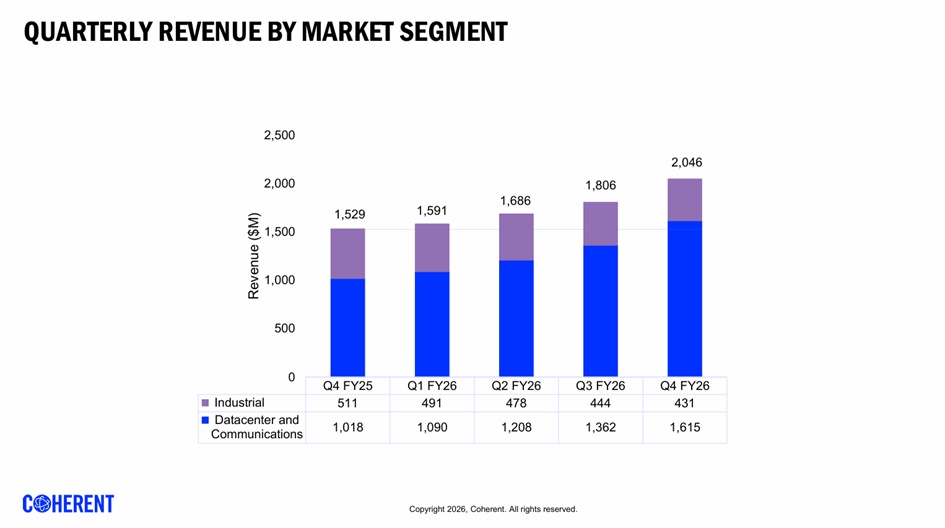
The latest results showed that Coherent’s revenue rose 34% to $2.05 billion in the fourth quarter, with the gross margin increasing to 38.5%. Net income rose to over $241 million.
The company expects revenue growth to continue accelerating this year. First-quarter revenue is projected to rise 45% to $2.3 billion, while earnings per share are expected to be $1.97. For the year, Coherent’s revenue is expected to rise to $10.6 billion, followed by $14.9 billion in the next fiscal year.
The renowned research firm Bernstein has initiated coverage of Coherent stock with an “Outperform” rating and has set an ambitious price target of $350. Outlook: As an indispensable supplier of photonic solutions and optical networks, the company is benefiting significantly from the structural expansion of modern AI infrastructure. Volume Drivers: A massive profit jump of +74% and revenue and earnings figures that significantly exceeded analyst estimates are currently attracting large institutional capital.
Coherent Unveils New PhotonLink Optics Platform for AI Expansion at ECOC 2026!
The photonics company Coherent is showcasing a broad portfolio of optical technology for AI data centers at the ECOC 2026 trade show and is introducing PhotonLink, a new integrated optics platform. The focus is on increased bandwidth, lower power consumption, and meeting growing cooling requirements. New PhotonLink Platform Coherent is presenting numerous new optical technologies and live demonstrations at the European Conference on Optical Communication (ECOC) 2026 in Málaga, Spain.
To me, Coherent is one of the most compelling suppliers of AI infrastructure, precisely because the company does not rely on a single product. Simply put, Coherent provides the optical technology that enables data centers to transmit massive amounts of data via light—and it is precisely this data traffic that is exploding with every new AI cluster. What particularly impresses me is the vertical integration: Coherent covers the entire supply chain, from raw materials to individual components to complete systems.
Management reports a record-high order backlog with visibility extending into the 2028 calendar year. Central to this is the partnership with NVIDIA concluded in March 2026: a $2 billion equity investment as well as a multi-year supply contract for co-packaged optics components through the end of the decade. As a result, cash reserves rose to $3 billion, and the debt-to-EBITDA ratio fell to 0.5 times.
In July, the company was honored on TIME’s “America’s Best Companies 2026” list. Furthermore, Coherent is the top holding in the new Roundhill Photonics & Optics ETF (LYTE). This ETF offers exposure to a concentrated portfolio of global companies in the photonics and optics sectors. LYTE is an actively managed ETF.
Coherent Corp. is one of the world’s leading manufacturers and marketers of photonic products, lasers, and engineered materials. The revenue breakdown by business segment is as follows:
- Manufacture of optical transmitters and modules (58.9%): transceivers, modules, components, optical devices, and semiconductors for data centers and communications applications;
- Manufacture of lasers and optical systems (24.7%);
- Manufacture of engineering materials and optoelectronic components (16.4%): laser optics, thermoelectric components, ceramic composites, VCSELs, EELs, pump lasers, and high-power lasers for material processing and integrated circuits.
Net revenue is distributed geographically as follows: North America (61.4%), Europe (12%), China (11.7%), Japan (6.7%), and other markets (8.2%).
Number of employees: 51,478
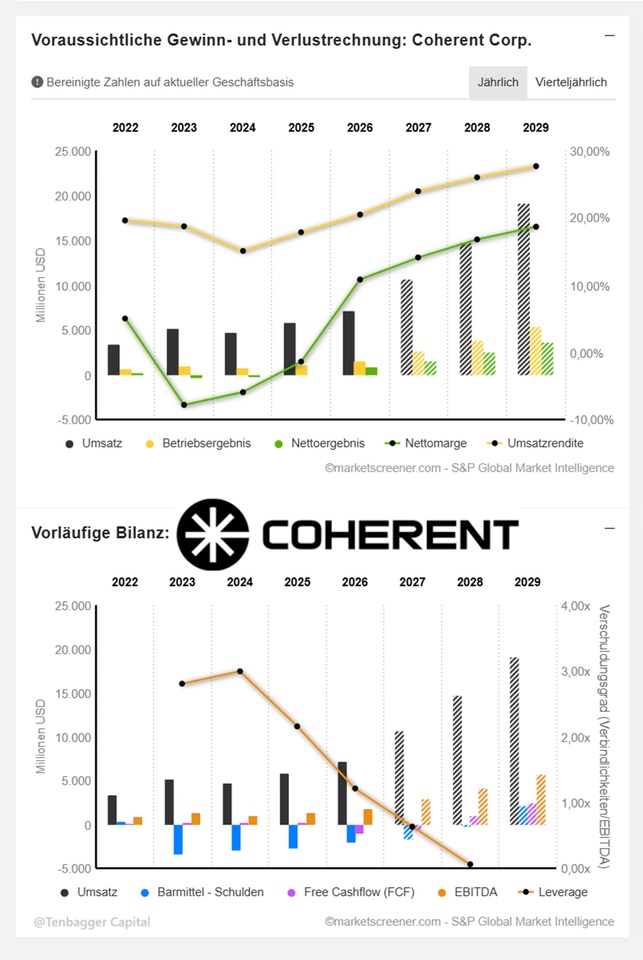
Company: Coherent Corp.
ISIN: US19247G1076
Source: Exclusively MarketScreener – Finanzdaten Coherent
Fiscal year: through June of each year
As of: October 31, 2026
All financial figures in millions of USD, except for earnings per share (USD), percentages, and debt-to-equity ratio. Thousands separated according to German notation.
Date of publication: August 12, 2026
5. My Assessment – Coherent as a Candidate for the 2036 Portfolio
The forecasts indicate a highly interesting trajectory.
Revenue Growth
⭐⭐⭐⭐⭐
EBIT Growth
⭐⭐⭐⭐⭐
Earnings Growth
⭐⭐⭐⭐⭐
Margin Performance
⭐⭐⭐⭐⭐
Cash Flow
⭐⭐⭐⭐
Balance Sheet Performance
⭐⭐⭐⭐⭐
Three particularly interesting points
1. The second growth phase
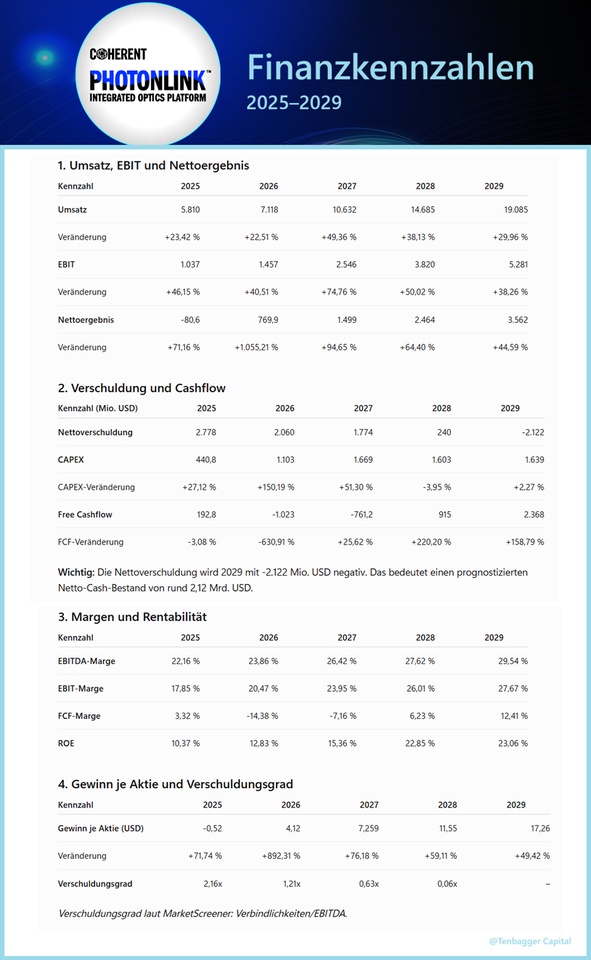
From 2025 to 2029, revenue is expected to rise from $5.81 billion to $19.09 billion. That represents more than a threefold increase.
2. Enormous operating leverage
EBIT is expected to rise from $1.04 billion to $5.28 billion. At the same time, the EBIT margin will improve from 17.85% to 27.67%.
This is a remarkable combination of growth and rising profitability.
3. Cash flow is the decisive test
In 2026 and 2027, high capital expenditures will significantly weigh on free cash flow. In 2028, it is expected to return to a clearly positive level and reach $2.37 billion as early as 2029.
My Conclusion
In my view, Coherent is a highly interesting beneficiary of the AI investment wave.
Particularly exciting is the combination of:
- Optical transceivers and photonics.
- High-power lasers.
- Data center infrastructure.
- Rising data traffic driven by AI.
- Economies of scale and rising margins.
However: The forecasts through 2029 are ambitious. The key factor will be whether Coherent can actually convert this strong growth into sustainable free cash flow.
For the 2036 portfolio, I would therefore definitely continue to monitor Coherent as an interesting AI infrastructure stock.
Note: All figures are taken from the MarketScreener link provided. Figures from 2026 onward are forecasts or estimates, not guaranteed results.
My Assessment for the 2036 Portfolio
Three stocks stand out in particular:
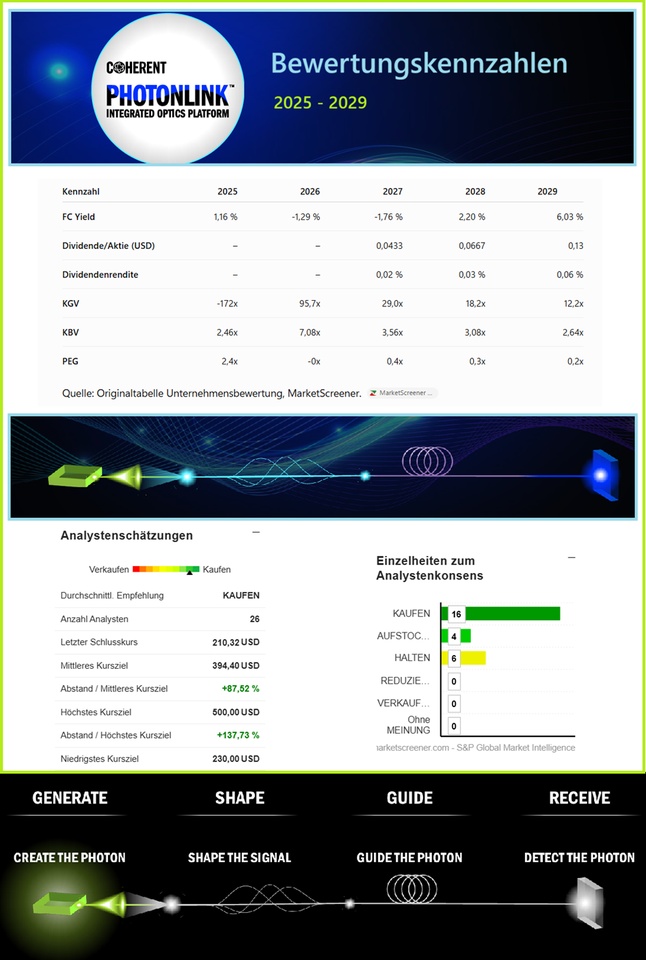
P/E ratio for 2029: 12.2 – significantly lower than the 2026 figure of 95.7.
FC Yield 2029: 6.03% – a substantial improvement over the negative figures in 2026 and 2027.
PEG 2029: 0.2 – very attractive based on the projected earnings growth.
My conclusion: The valuation looks extremely promising for 2028/2029. Coherent could be a major beneficiary of AI investments in optical data transmission and photonics.
Important: The low valuation multiples are forecasts and assume that Coherent will achieve its ambitious earnings targets.
Note: The dividend is stated in USD per share. All other figures are key metrics or multiples and do not require conversion to euros.
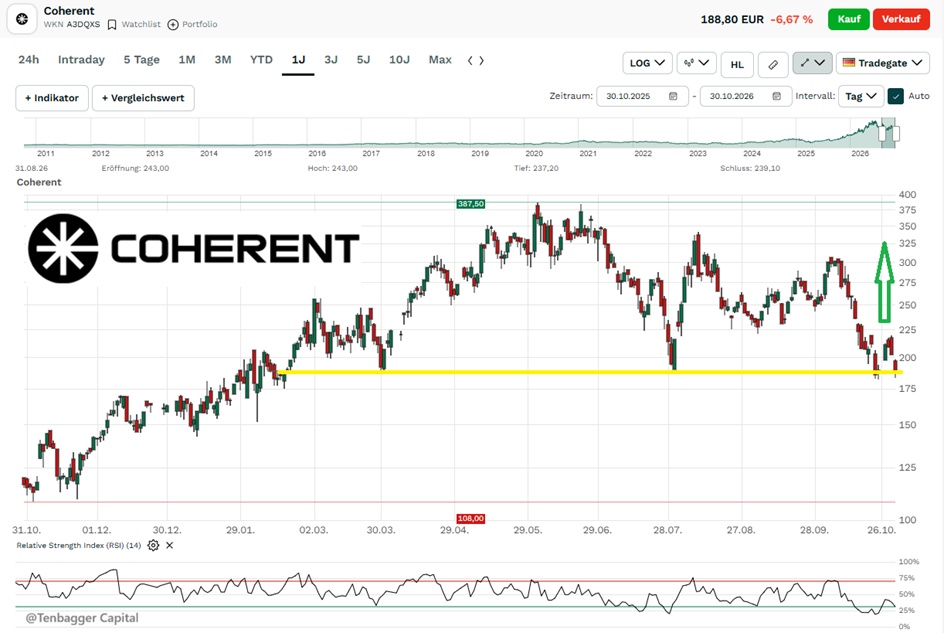
However, there is a risk that technical indicators suggest Coherent shares are on the verge of forming a death cross pattern. This pattern is characterized by the 50-day and 200-day crossover of the exponential moving averages (EMA). If it occurs, it could lead to further declines, potentially down to the psychological level of $200.
The death cross is possible because the AI sector faces significant challenges, as investors fear the bubble will burst. If that happens, the stock could fall further toward the psychological level of $200.
That said, I personally don’t see a bubble.
My friends, the earnings report is coming on November 4. What’s your take—wait, or get in before then?
190.05 EUR -10.85 EUR -5.40%
October 30, 2026
212.60 USD +2.33 USD +1.11%


