10Lun·

the AI bubble is bursting ??? but not with AI Value

Hello my dears,

Even the Tageschau is now talking about an AI bubble.


However, when I look at the valuations and annual performance of some AI companies, there is a world of difference.


As an example, I would like to present $KD (+4,85 %) Kyndryl. Or $AKAM (-5,14 %) Akamai would also be an example.


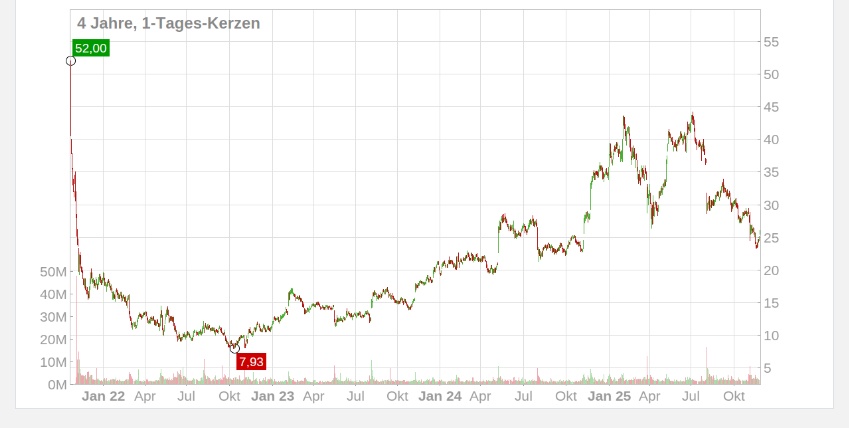
But let's stay with Kyndryl, where I noticed an annual performance of MINUS 26 %.


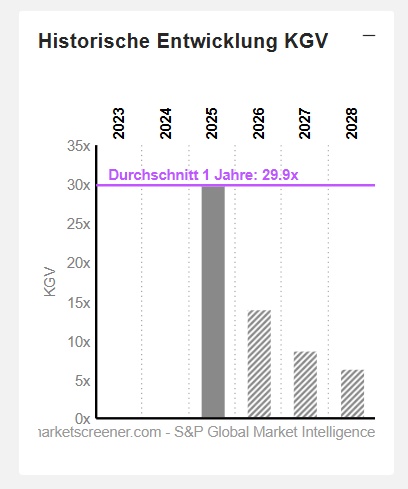
I immediately assumed that it was overvalued. But with a P/E ratio of 16, which has fallen by half and will fall again to 9.44 next year. I cannot determine an overvaluation.


So my next assumption was that it must be due to growth. But with earnings growth.

2025: 71 % 2026: 60.45 % 2027: 37.85 % (according to Onvista)

this assumption cannot be correct either.


That's why I went here and picked out more multiples.

I would now like to get the whole community on board.


Can you find a reason why there is no positive performance here despite the multiples?

Or is now perhaps even a good time to add this very cheap AI stock to your portfolio?


I hope for plenty of comments


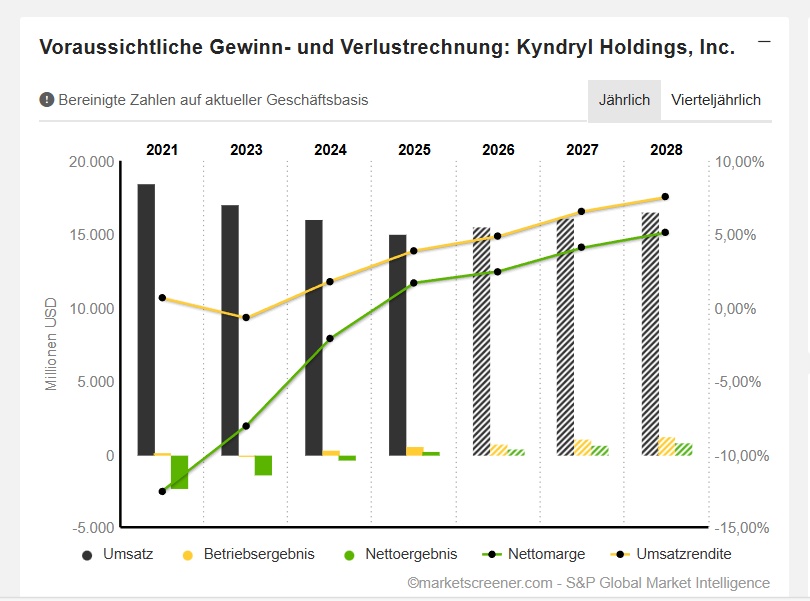
USD in millions

estimates


Year

2026
2027
2028

Turnover 15.554 16.115 16.560

Change in
3,3 %
3,6 % 2,76 %


EBIT 753,7 1.054 1.245

Change in
29,5 %
39,87 %
18,13 %


Net profit 381,3 655,6 844,9

Change in net profit
51,32 %
71,92 %
28,88 %


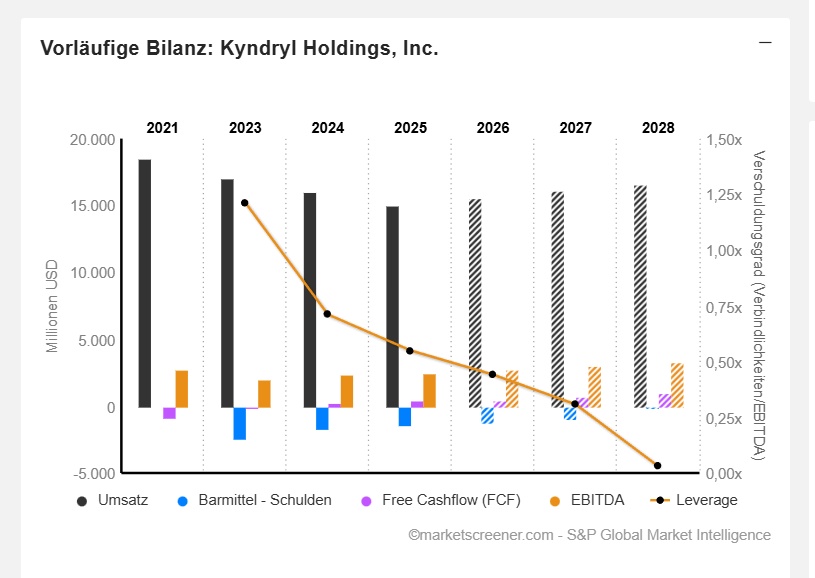
Net debt 1.221 939 103


CAPEX 681,5 680 676


Free cash flow 479 761 1.032

Change in
7,4 %
58,87 %
35,61 %


EBIT margin 4,85 % 6,54 % 7,52 %

ROE 43,81 % 64,82 % 52,56 %


P/E RATIO 14x 8.72x 6.32x


PEG 0.2x 0.1x 0.2x


Profit p share 1,795 2,88 3,97


My dears,

I can't really find a fly in the ointment. @Liebesspieler
@topicswithhead

Sales are only increasing at a single-digit rate and the EBIT margin is also in the single-digit range.

But here I would like to point out that the company has only just become profitable.


What I like is the increase in all key figures and the simultaneous reduction in debt.

Profits are rising significantly faster than sales.


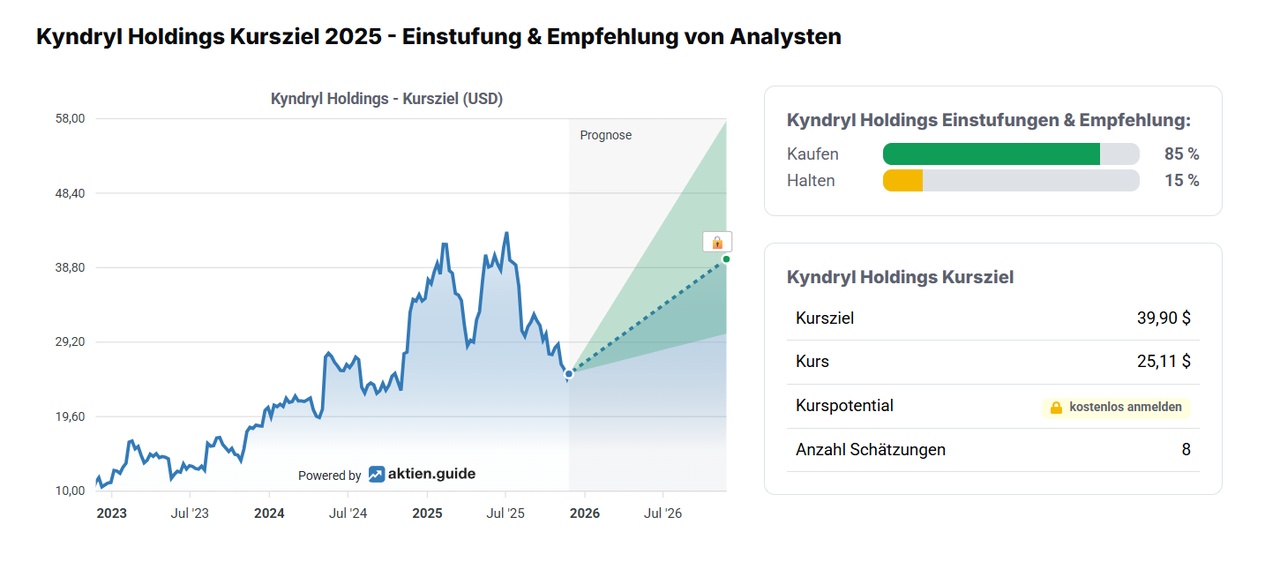
And the analysts recommend buying.


Kyndryl Holdings, Inc. is an IT infrastructure services provider serving enterprise customers in more than 60 countries. The company designs, builds, manages and modernizes complex, mission-critical information systems. The company's segments include the United States, Japan, major markets and strategic markets. The company offers services in areas such as cloud services, core enterprise and zCloud services, applications, data and artificial intelligence (AI), digital workplace services, and network and edge services. Its consulting and implementation services are offered under the name Kyndryl Consult. The company designs and builds multi-cloud environments for its customers and offers managed services for them. It provides end-to-end services for enterprise data, including data transformation, data governance and compliance, and data migration. Its services for the digital workplace include technology infrastructure, mobility and access solutions.

Number of employees: 73,000


Kyndryl in focus as Guggenheim begins purchase evaluation


Kyndryl (KD) was in focus on Wednesday as Guggenheim initiated coverage of the technology company with a buy rating and a $30 price target.

Shares rose modestly in premarket trading.

"Since the spin-off of IBM in 2021, the management of Kyndryl Holdings, Inc. (KD) has been actively reshaping its business through the 'Triple A' program - Alliances, Advanced Delivery, and Accounts - to increase the quality of signings, automate and standardize delivery, and enforce contract discipline, enabling improved profitability and positive free cash flow in a large, slow-growth TAM segment with high barriers to entry and a limited number of scaled competitors," analyst Jonathan Lee wrote in a note to clients. " Although the recent transaction shift has impacted revenue performance, profitability progress is encouraging, especially in a challenging macro environment. As such, we believe KD is among the best positioned companies in the infrastructure outsourcing space to transition to stability in the medium term, which underpins our coverage initiation with a Buy rating and $30 price target."

To follow up further, Lee said that Investor Day 2024, where the company's management outlined its medium-term ambitions, had been helpful. Highlighting its goal to triple cash flow, double pre-tax profits and achieve single-digit revenue growth by fiscal 2028, the company is focused on "building a 'healthier' services company by prioritizing portfolio quality," Lee explained.

"While we are still in the early stages of the company's turnaround, we see positive progress in the company's 'Triple A' initiative, which supports our Buy rating as post-spin deal signings contribute to higher profitability in the near to medium term," Lee added.


Second quarter 2026 earnings presentation

Nov 05, 2025

Microsoft PowerPoint - Final_Fiscal Q2 2026 Earnings Deck_11.5.25.pptx


Kyndryl in focus as Guggenheim starts with Buy rating (KD:NYSE) | Seeking Alpha


Kyndryl unveils new services to secure enterprise AI


Kyndryl stellt neue Dienste zur Absicherung von Unternehmens-KI vor Von Investing.com


Kyndryl acquires Dutch cloud specialist Solvinity


Kyndryl übernimmt niederländischen Cloud-Spezialisten Solvinity Von Investing.com


Nov 24, 2025

Kyndryl bringt das Agentic-AI-Framework und -Dienste für den Großrechner auf den Markt


Nov. 20, 2025

Kyndryl erweitert die Partnerschaft mit Vodafone Idea Limited, um automatisierte IT-Abläufe und Transformation der Delivery zu liefern


November 19, 2025

Kyndryl kündigt Agentic AI Digital Trust an, um die Governance von KI-Agenten in großem Maßstab zu unterstützen


Bank of America sees Kyndryl as a top pick - share about to break out of cup with handle formation!

Die Bank of America sieht Kyndryl als Top-Pick — Aktie vor Ausbruch aus Tasse mit Henkel-Formation!


Kyndryl was created in 2021 through the spin-off of IBM. It focuses on the management and optimization of IT infrastructures, aiming to support companies in their digital transformation and increase the efficiency of their IT operations.


The company's strategy includes building customer relationships that include cloud-based content, leveraging hyperscaler certifications and transforming service delivery through automation and technology integration. By focusing on areas such as cloud, application data and AI, security and edge, Kyndryl continues to evolve its business mix to capitalize on growth opportunities. Several strategic partnerships were announced this month with Commvault and Databricks, among others. Bank of America named Kyndryl one of its top small cap stocks for the second half of the year on June 17.


The stock has been consolidating in a tight range since the Q4 numbers in early May and could now be poised to break out of a cup and handle formation. (KD)
attachment
attachment


attachment


attachment


attachment


attachment


attachment
15
34 Comentarios

Imagen de perfil
Thanks for tagging me :)
I'm not a fan of the place: Kyndryl is ultimately IBM's spin-off - and that's what shapes its profile to this day. Much of it looks like the outsourced low-margin part of the old IBM service business: complex legacy contracts, low scalability and manageable growth momentum. The ongoing transformation towards cloud, security and hyperscalers is the right thing to do, but its structural leverage remains limited as long as the legacy business dominates. For sustainable outperformance, I lack a clear growth core that goes beyond a cyclical re-rating. Accordingly, I see Kyndryl more as a turnaround trade than a long-term quality investment.
•
7
•
Imagen de perfil
@Liebesspieler
Yes, I read that once too, that IBM is hanging on to them like a stone.
But I think it's good that they are now profitable.
And I don't think the path they've taken is a bad one either. And as you can see from the figures, it is slowly bearing fruit.
Given the valuation and the falling P/E ratio, I don't find you uninteresting
•
1
•
Imagen de perfil
@Tenbagger2024 I see the point - profitability is progress, and the management has indeed made some legacy contracts cleaner. For me, however, the decisive factor remains how much of this is structural and how much is more an effect of cost discipline and catch-up effects. As a spin-off from IBM, Kyndryl still carries a lot of low-margin legacy business with it, and that is precisely what limits the real upside in my view. On the valuation side, you can play the case, especially if the P/E ratio continues to fall - but the current trend is not yet sufficient for a lasting quality profile.
•
1
•
Imagen de perfil
@Liebesspieler
Perhaps something for our traders
@Multibagger @Dividendenopi @TomTurboInvest
•
2
•
Imagen de perfil
@Tenbagger2024 I'm out. $IBM is for me one of, if not the top pick in quantum computing, but such service shops, no thanks!
•
1
•
Imagen de perfil
@Liebesspieler @Tenbagger2024 The company reminds me of the times when the former Siemens $SIE IT subsidiary SBS was outsourced to $ATO. The figures speak a similar (bad) language.
••
Imagen de perfil
@Tenbagger2024 I'll have to take a closer look 😀
PS: Since you like chart formations more and more - I'm out of $MMK today - "W" as in back on the aVWAP 🤣
••
Imagen de perfil
@TomTurboInvest
And then get back in at the bottom?
•
1
•
Imagen de perfil
@Tenbagger2024 yes - just like recently 😅

PS: just had a quick look at $KD, only skimmed it on my phone, BUT technically very tempting!
Bullish in the short term in any case, first target zone around 27.8$, but definitely sees potential up to 34$ or 37$ in the short/medium term

I'm not a "fundamentalist" but also strong according to Quantamental🧐
•
2
•
Imagen de perfil
@Tenbagger2024 Nope, thanks anyway. I'm not deep enough in the subject when it comes to papers that are so specific to me. I'm slowly working my way into the field, but it wouldn't be enough for more than a copy trade. And the enthusiasm here is limited
•
2
•
Imagen de perfil
@Tenbagger2024 I got in today at the start of trading with a small $KD position, the bridge day after Thanksgiving is not ideal in terms of liquidity, but the threshold at 25.7$ was tempting. Maybe we'll head north next week 😅
•
1
•
Ver todas las 3 respuestas adicionales
Imagen de perfil
Idk part of it will be the USD loss. The other is probably mistrust. Regardless, many stocks are massively down, in many areas the new industry leaders are up, and I would simply make the assumption that they are operating in markets where there are economies of scale plus the belief that consulting is becoming increasingly irrelevant. Cloud, network edging, cybersecurity, data and Ai are mainly areas where you earn more with size but also get better. Only consulting is actually excluded from this.
•
1
•
Imagen de perfil
@topicswithhead
Thank you for your assessment.
Perhaps it really is investor uncertainty
••
Imagen de perfil
@Tenbagger2024 you also have to pay attention to which currency you are looking at. Euro to USD is down just under 10%, although you probably know that
•
1
•
Imagen de perfil
@topicswithhead
But that doesn't just affect Kyndryl
••
Imagen de perfil
@Tenbagger2024 I know. Just all stocks that trade in USD. There are quite a few
•
1
•
Imagen de perfil
@topicswithhead
You've always made mega company presentations here.
My dear, why don't you make any more?
••
Imagen de perfil
@Tenbagger2024 do one almost every week but don't post anything . I find too little really interesting. I also don't have enough time to prepare them by calculating, formatting and searching for pictures. Lastly, I looked at $SOLSV the Honeywell spin off and made a mini buy so that there is more in it than the spinoff. Otherwise I'm currently looking at $COIN, $SHL and co. If you want a report like that I can send you the prompt. Download Gemini, take the pro model and activate deep research
••
Imagen de perfil
@topicswithhead otherwise you can chart and match them free of charge at Fical.ai
••
Imagen de perfil
@Tenbagger2024 The prompt is the new one. Don't know yet if I'm happy with it. Just insert your date and company: Role & Context:
You are a Senior Equity Research Analyst at a leading investment bank. Your target audience is sophisticated private investors who are not just looking for surface knowledge, but want to understand the mechanisms behind the company. Your tone is professional, objective, critically scrutinizing and analytically precise.

Task:
Create a comprehensive "deep dive" analysis of [Solstice]. Use all of your available knowledge and web searches to include recent annual reports (10-k/10-q), earnings call transcripts and expert opinions through [11/20/2025].

Structure of the analysis:

1. executive summary & investment thesis

A concise summary (max. 5 sentences): What makes the company attractive? What is the main problem?

The "elevator pitch": Why should you buy (or avoid) this stock now?

2. company profile & strategic positioning

Business model in detail: Explain the "flywheel effect" (if any). How exactly is revenue generated?

USP & Economic Moat (moat): Does the company have lasting competitive advantages (e.g. network effects, high switching costs, strong brand, cost advantages)? Evaluate the strength of the moat (Wide, Narrow, None).

Strategy: What is the focus? (Organic growth vs. M&A, dividends vs. reinvestment).

3. market, competition & TAM

Market dynamics: Is the underlying market growing structurally or cyclically?

Competitive comparison: Create a short comparison table with the 2-3 most important competitors. Compare not only products, but also market shares and technological advantages.

Total Addressable Market (TAM): Realistic assessment of the market potential (differentiate SAM/SOM if possible).

4. management & governance (critical!)

Management team: Who leads the company? (Track record, reputation).

Skin in the Game: Does the management hold significant shares in the company? Are interests aligned with shareholders (insider buying/selling)?

Capital allocation: How does the management handle money? (Share buybacks, dividends, debt repayment or expensive acquisitions?)

5. financial analysis (the numbers behind the story)

Create a table with the following values of the last 3 years + TTM (Trailing Twelve Months):

Turnover & Growth (%)

EBITDA & Margin (%)

Free cash flow (FCF) & FCF margin (%) (very important for the valuation)

Net Debt / EBITDA (leverage ratio)

ROIC (Return on Invested Capital) - indicator for the quality of management

Interpretation: Explain the trends. Why are margins rising or falling? Is the debt sustainable?

6 SWOT analysis (extended)

Strengths & Weaknesses: (Internal)

Opportunities & Risks: (External)

The "elephant in the room": What is the biggest, often overlooked risk (e.g. regulatory, geopolitical, disruption through AI)?

7. valuation & price potential

Key figures: Current P/E ratio (P/E), P/S ratio (P/S) and EV/EBITDA compared to historical average (5 years) and peer group. Is the share historically cheap or expensive?

Analyst consensus: Summary of current ratings and price targets.

Price drivers (catalysts): What events in the next 6-12 months could move the share price?

8 Conclusion: The bull vs. bear scenario

Bull Case (Optimistic): What needs to happen for the stock to double?

Bear Case (Pessimistic): What would be the "worst case scenario" in which the investment thesis fails?

Final verdict: Buy, hold or sell (based on the current risk profile).
Formatting notes:
Use bold type for key factors and numbers.
Use tables for financial data and competitive comparisons.
Write concisely, avoid filler words ("fluff") and use bullet points for better readability.
readability.
Cite sources or uncertainties when data is estimated.
••
Imagen de perfil
@Tenbagger2024 but I think I will make the prompt a little more objective
••
Imagen de perfil
@topicswithhead
Do you have any links for me?
••
Ver todas las 3 respuestas adicionales
Imagen de perfil
Valuation:
What do competitors' margins look like? Perhaps the market does not believe in further strong EBIT growth beyond 2027?
Then you would have a company with an EBIT margin of around 10% that is growing by around 2-5% in sales.


Enter such estimates into a small multiple valuation model and you will quickly know whether the share is really that cheap :)
At first glance (5min) it is not a blatant bargain for me
•
1
•
Imagen de perfil
@Multibagger @TomTurboInvest @Tenbagger2024 Fortunately, I wasn't invested. What happened🥴 -56% in one day, news can't be that bad 😅
•
1
•
Imagen de perfil
@Darkwingduck They have postponed the quarterly financial statements and the CFO would have to go. The regulator is investigating and it is assumed that the balance sheet has been manipulated.
•
1
•
Imagen de perfil
@Multibagger wow, that IS bad😂
•
1
•
Imagen de perfil
Good morning dear @Tenbagger2024, I discovered a stock today so I would like to ask a question, the stock was down because of late financial report published, therefore is very useful in the short term now invested to double? LG Robin
••
Imagen de perfil
@RobHood10 with a P/E ratio of 5.55, the share is becoming ever cheaper, despite further growth. Growth will continue until 2028, but somehow this is still not reflected in the share price. I would therefore perhaps prefer to wait for a clear turnaround.
•
1
•
Únase a la conversación