Miquel y Costas ($MCM (+0,05 %) ) manufactures specialty papers and cellulose for the tobacco, filtration, and technical industries. 80+ years in operation, global clients, micro-cap on the Madrid exchange.
This week's algorithm output:
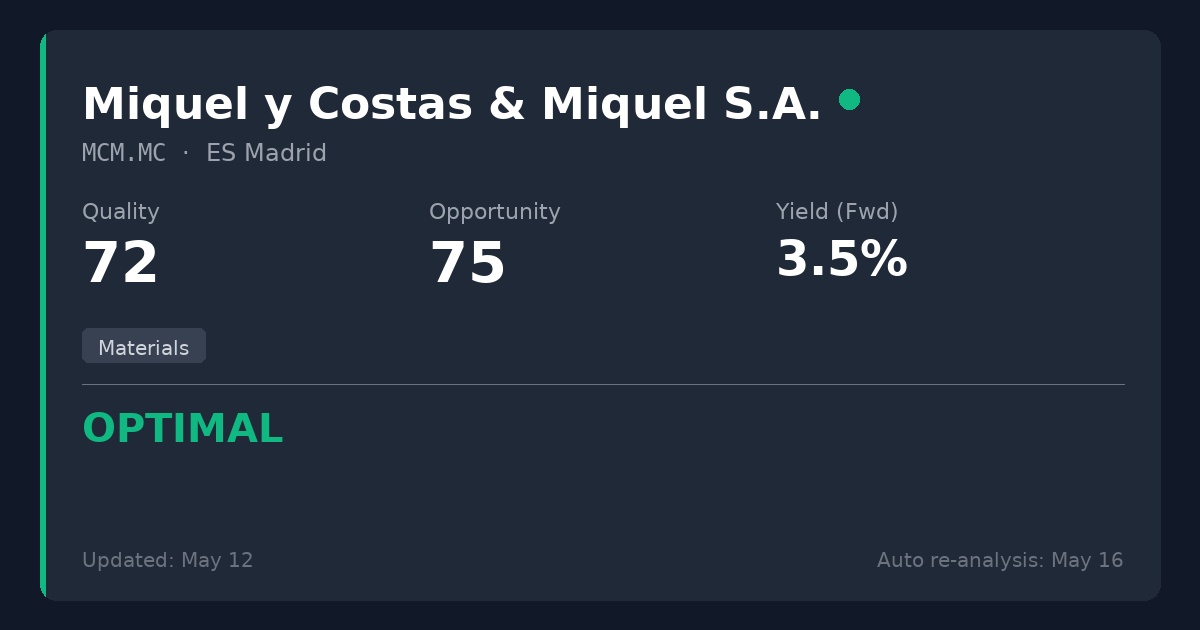
🟢 OPTIMAL
Quality: 72/100
Opportunity: 75/100
Key numbers:
P/E: 11.68x (sweet spot: 8-15x for value investors)
EBITDA margin: 23.3%
Net Debt/EBITDA: -0.90x — net CASH, not net debt
Debt/Equity: 0.12x
Most providers only capture ~€9.5M in bank cash for MCM. They miss €33M in short-term financial investments and €80M in long-term financial investments sitting on the balance sheet. The actual net cash position per the Q1 2026 CNMV filing: +€65.8M. A company that effectively owes nothing.
The dividend:
2025 DPS: €0.487 (~3.5% yield at current €13.90)
Cut 6.9% in 2025 — intentionally, to fund plant expansions
Operating cash flow still covers the dividend (FCF payout: 0.65x during the build phase)
Q1 2026: +10% sales growth. The expansion is working.
Bottom line:
Solid business at an attractive price. 23% margins, net cash balance sheet, P/E 11.7x. The dividend cut was a capital allocation decision, not a distress signal.
Not on our core essential-services watchlist (Materials sector), but this is the kind of "hidden champion" that patient dividend investors should have on their radar.