1Semana·

⚡️🔋 IREN Expanded

And $IREN (-11,51 %) I decided to increase my investment today. It’s very promising in the long run, and the energy shortage is more likely to get worse than better…


And even if you’re investing more than you’re getting back for now, I’m convinced it’ll pay off…
attachment

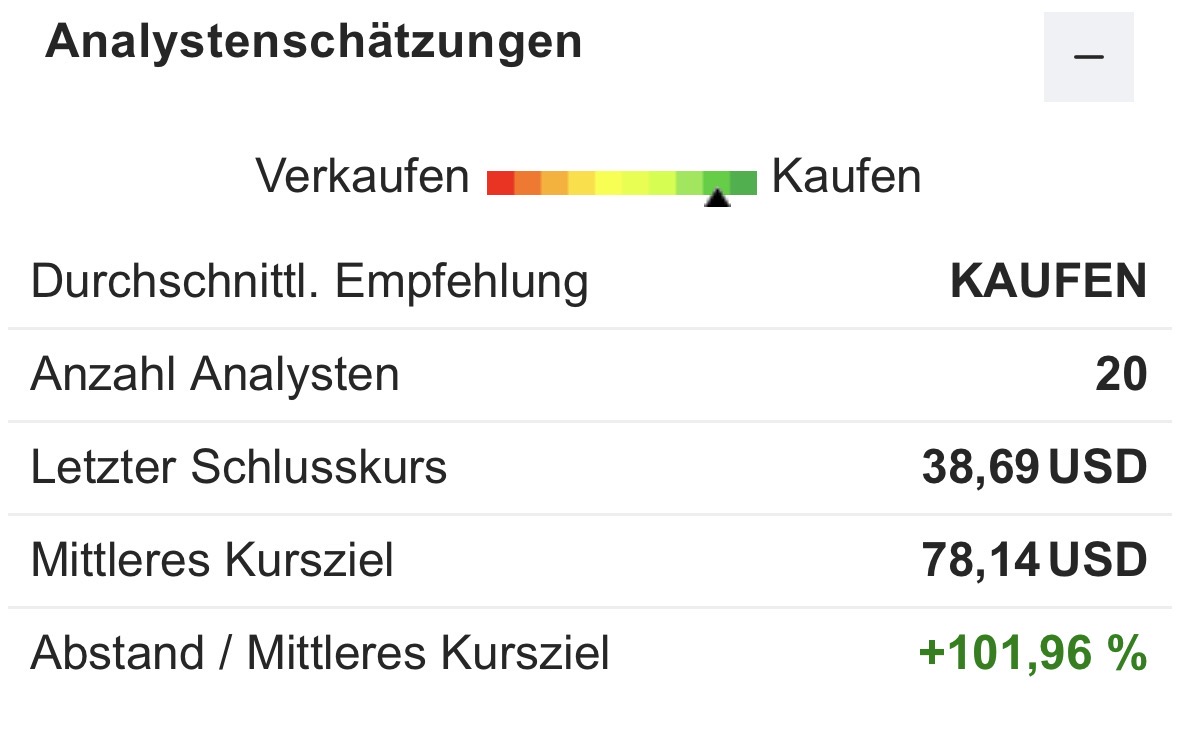
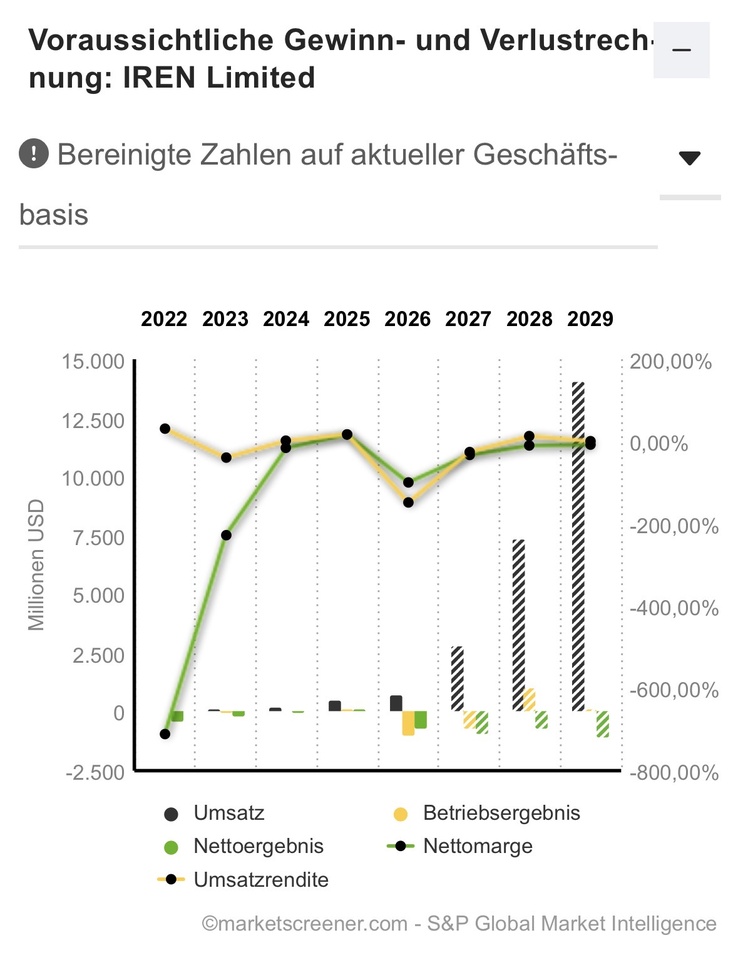
The analysts see it the same way:

attachment

Best regards, Small Investor 😁

08.10
IREN Limited logo
Comprado a 31,61 €
32
16 Comentarios

Imagen de perfil
-Financing costs are currently rising.
-It is unclear how long the CAPEX boom can continue, as hyperscalers are already increasingly reliant on debt—which they are struggling to hide—but investors are becoming increasingly skeptical.
-The public (especially in the U.S.) is turning against the expansion of data centers, and it is only a matter of time before politicians give in to the temptation and use this as a populist issue in election campaigns. Existing facilities may also face regulatory challenges, despite existing permits, etc.
-Prices for renting computing power will continue to fall as supply and efficiency increase, which may make it cheaper to rent new computing power than to continue operating old hardware—leading to a sudden loss in value of the old hardware and eroding the operator’s equity, as they are still paying off the old hardware.
-The analyst estimates you presented are uninformative, as analysts typically simply extrapolate the status quo into the future (regardless of any externalities) and are sometimes subject to significant conflicts of interest (lack of independence due to their own financial stakes). So you have to make your own assessment.

If the AI construct (in its current form) collapses, IREN is the company that will be the first to crash and will never recover from it. The business model is dead without a sustained AI boom. I think AI will change the world, but not in the way we imagine today. That’s understandable, since the topic has only been around for just under four years (in the general public). I doubt that in 10 years, any consumer will still be spending money on text-based AI. Value creation will most likely shift—for example, toward physical applications—but even there, opportunities are scarce (see Noetra in Japan). Regardless, I wouldn’t invest in a pure-play company right now at the absolute cyclical peak. There are quite a few companies profiting from AI as well as numerous “shovel sellers,” but with the key difference that the latter aren’t dependent on this unsustainable CAPEX boom. Whether they’re manufacturers of robotics components, cooling systems, or whatever else—even without AI, these companies have a solid business model.

The risk of total loss with IREN is not insignificant, which is why it’s better to invest your money elsewhere. I’m willing to take on high risks when investing, but only if I believe in the company—which is definitely not the case here. Conclusion: No moat, no special technology, no platform, unstable finances, unstable market, high dependence, regulatory sensitivity, dilution risk, risk of total loss, questionable entry point, etc., etc., etc.
•
17
•
Imagen de perfil
@PikaPika0105 👋 Thanks for pointing that out—I’ll take it seriously and go over all the numbers again. Right now, IREN is showing a slight gain in my portfolio (aside from earlier profit-taking). But I’ll keep the risks you mentioned in mind… Thanks 😁👍
•
2
•
Imagen de perfil
@PikaPika0105 I think it's so interesting to read your perspective and then @Pazzzi 's, haha
•
2
•
Imagen de perfil
@Sebbster Once the hype dies down, things will naturally look bleak for IREN, but there’s not a single sign of that happening right now.
If things continue this way, IREN could skyrocket; if not, it could also go downhill.

High risk—high reward

I think critical perspectives are very important for evaluating one’s own investment decisions!
•
2
•
Imagen de perfil
@Pazzzi Don't you think there are signs that the hype is coming to an end? I already mentioned funding issues and politics. Plus, a large part of the AI industry depends solely on OpenAI and Anthropic. If either of these two—or even just one—runs into trouble, it will trigger a negative chain reaction. In the medium term, substitution issues will also come into play. So it’s not as if everything today is still the same as it was 1–3 years ago.
••
Imagen de perfil
@PikaPika0105 At the moment, I don't see that happening, since rental prices for GPUs—from older models (e.g., H100/H200) to newer ones (GB300)—continue to rise. Demand is therefore likely to continue rising, and stricter regulations, as well as construction delays, are currently still having a positive effect on these rental prices.

I think OpenAI and Anthropic will face a problem in the medium term, as the push toward open models—driven by companies like Nvidia—will undermine the AI token business model. If that happens, the only thing left of the AI business will be the rental of computing power.

Financing is the biggest risk; high interest rates and bond yields are weighing on growth stock valuations and making financing significantly more expensive—which will drive up costs extremely in the long term.

Currently, however, it is (still) a fact that all AI applications that have been deployed are growing exponentially. I’m thinking, for example, of cybersecurity, which is becoming increasingly easy for attackers to exploit through swarms of agents and, at the same time, must be defended against using swarms of agents. Another example is the use of automated AI agents, the adoption of which has exploded this year and will continue to do so (exact figures would need to be researched).

Another sign is the earnings of memory manufacturers, which continue to break all growth records (most recently, for example, Samsung).

The huge AI stock hype has already undergone quite a reality check due to the recent sharp price declines (IREN, for example, down 50% since June). And I now see a realistic, risk-adjusted valuation.

Especially with IREN, which hasn’t yet negotiated any major contracts for next year and where GPU prices have continued to rise, I see a strong chance that the stock will be revalued. IREN is also very well positioned for this thesis—which is (still) on track—in terms of its construction experience and expertise.

No one can predict whether or when this growth will slow down, but I don’t see any signs of that yet.

Should it happen, however, everyone should be aware that the downside risk for IREN is also significant.
•
2
•
Imagen de perfil
There’s a lot of unnecessary hate directed at the stock because it isn’t performing well and its growth phase is being unfairly called into question.

At the same time, demand continues to grow, and GPU rental prices keep rising.

We’re talking about a company that’s worth ~15 billion and will generate 15 billion in ARR next year.

High bond yields mean more expensive financing and lower stock valuations, which is weighing on the share price.
However, if tensions ease again—perhaps due to a potential de-escalation in the Iran conflict—the stock could gain another 50% in two weeks.

Short-term macroeconomic news isn’t a cause for concern regarding the stock.

In five years, we easily see this becoming a $100 billion company.
•
9
•
Imagen de perfil
1Semana
I know you're really into your small but select portfolio of stocks… but maybe a little bit of diversification wouldn't be a bad idea either!?
🤔
•
6
•
Imagen de perfil
@GHF 💯 I'll let you know soon—I actually started a savings plan on the NASDAQ 🤫
•
1
•
Imagen de perfil
I think we could go even deeper there.
••
Imagen de perfil
@Darkwingduck What do you think?
••
Imagen de perfil
@Klein-Anleger If the zone breaks down, we could test the $27–$28 level again.
•
2
•
Imagen de perfil
@Klein-Anleger Of course, Iren😅
•
1
•
Imagen de perfil
1Semana
@Klein-Anleger Well, see, it's starting to come together 😉
•
1
•
This stock is total crap. It's just hype, and soon no one will be talking about it anymore.
•
1
•
Imagen de perfil
@Divident_e Whoa, that must have really hit someone hard 😘😂
•
1
•
Únase a la conversación