The black gold on the defensive dumbbell side and the wonder why no one has ever mentioned this stock before
We often chase the hottest SaaS trends or the most explosive turnaround stories here in the forum. But a robust portfolio needs a foundation that generates cold cash flow, regardless of what the tech world is doing. Today I present to you a real hidden champion from the Texas oil dust: Riley Exploration Permian $REPX (+7,02 %) . This is not a high-growth tech play, but a merciless cash machine for absolute dividend hunters.
1. what the company does
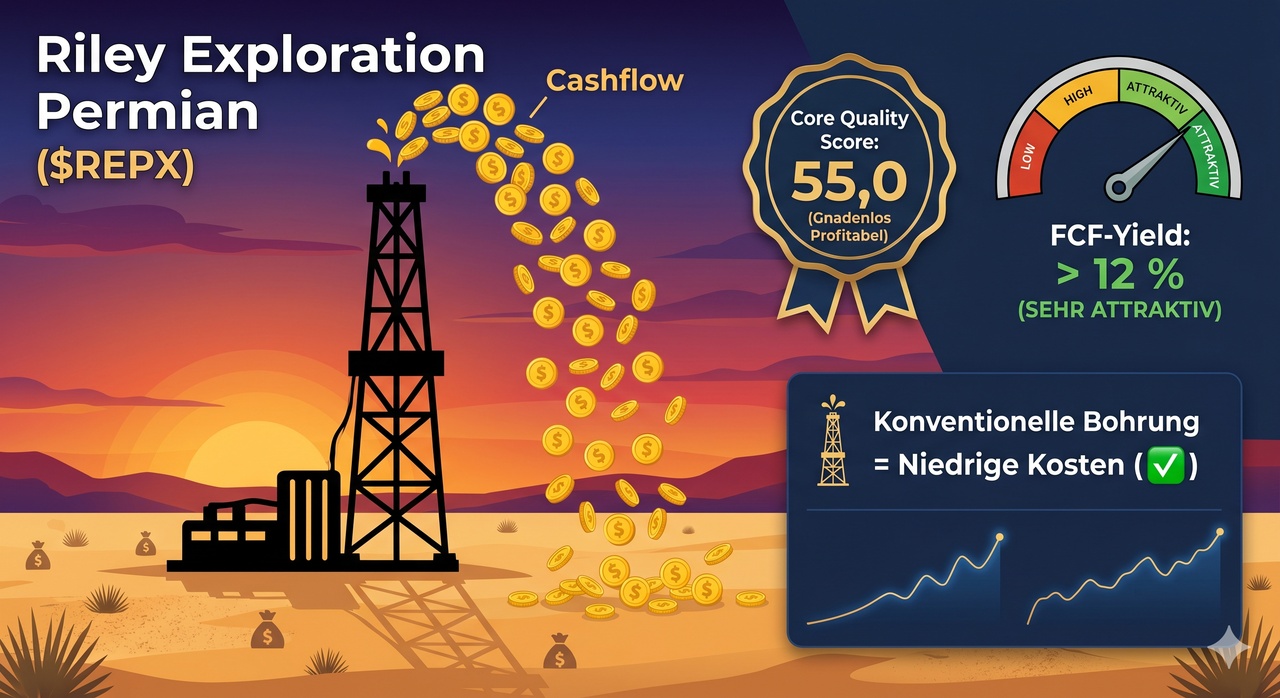
Riley Exploration Permian (REPX) is an independent oil and natural gas exploration and production (E&P) company. Their focus area? The legendary Permian Basin in Texas and New Mexico. The highlight: they are not just blindly chasing expensive shale oil, but are concentrating on conventional drilling in the San Andres Formation. This means shallower wells, lower costs and a highly profitable business model.
2. the moat (the monopoly of the niche)
There is rarely a true technological moat in the oil business; the price is dictated globally. REPX's "moat" lies in their extremely focused niche: they own prime, contiguous properties in the San Andres formation. Their conventional wells have a significantly lower decline rate than typical fracking wells of their competitors. This means they have to inject less capital to keep production stable.
3. the bare facts & key figures (Baselines 2026)
- WKN / ISIN: A2QQZ8 / US76665T1025
- Current share price: ~ 31 EUR
- Market capitalization: ~ EUR 580 million (An agile small-cap)
- P/E ratio (Price-Earnings Ratio): ~ 6.5 (Typical for the oil sector, ice cold value territory)
- Dividend yield:
~ 6.5% to 8.0% (incl. special dividends) - Balance sheet: Solidly financed. They use debt strategically for acquisitions, but generate enough cash to pay off debt quickly.
4. why is the share where it is? (The reality check)
REPX is a small cap in the oil sector. This means that the share price depends on the global WTI oil price. When oil is booming, REPX prints money like a central bank. When the oil price corrects, the share is often punished more severely than the big majors such as Exxon or Chevron. The share is currently extremely fairly valued, as the market is always skeptical about the long-term oil price.
5. chart analysis of the last few months
We do not see a parabolic tech chart here, but a volatile but intact upward movement that correlates strongly with the oil price. The share often oscillates in clear zones and repeatedly offers setbacks, which smart income investors use to add this high dividend yield to their portfolio.
6. the formula check (quality & cash flow)
Let's get out the AOK X-rays. We filter for hard numbers:
- The Core Quality Formula:
- Score = Sales Growth + Operating Margin
- REPX delivers solid production growth (approx. 10-15% organic sales growth at stable prices). The operating margin in this sector is brutal and at REPX is often north of the 40 %.
- Earnings: $15.0 + 40.0 = Score: 55.0! > 25 = very good.
- Note: The margin depends on the raw material, but operationally this is a masterpiece.
- The Cashflow Quality Formula:
- Free cash flow = Operating cash flow - CapEx
- This is where the model shines. Due to conventional drilling, the CapEx requirement is moderate. The FCF yield (free cash flow yield) at REPX is massively above our hurdle rate of 8 %. We are talking here about > 12 % FCF yield.
- Result: A true cash flow giant. The dividend is not paid out of the substance, but is covered by hard cash flow. Our dividend filter (at least 3.5 %, cash flow-covered) is passed with flying colors. No exclusion criteria (red flags) in sight.
7. future prospects & catalysts
Growth at REPX comes from smart "bolt-on" acquisitions (purchases of neighboring properties) and the constant optimization of production. One catalyst is infrastructure: they are investing in their own water and electricity networks on their fields, which will further reduce future extraction costs.
8 Competition & market environment
The Permian Basin is the shark tank of the oil industry. Competitors such as Permian Resources and Diamondback Energy are giants. REPX is the small, extremely agile niche player. They are not trying to beat the big players, but are sucking their particular field dry with maximum efficiency.
9 Special Entry Zones (The "Bargain Hunter's List")
If you want to get this cash flow engine into your portfolio, you need to act with limits:
- Zone 1 (the income entry): ~ EUR 28.50 to EUR 27.00. Here you catch an absolutely crisis-proof dividend that is underpinned by the operating cash flow.
- Zone 2 (The oil crisis low): < EUR 25.00. If the share price falls here (usually driven by a macro oil price shock), the smart value investor buys with both hands.
10. profit margins & scalability
REPX's lifting costs (the cost to bring a barrel of oil to the surface) are among the lowest in the region. Even when the oil price falls, REPX remains profitable long before its expensive shale oil competitors start to sweat.
11. voices from the engine room (CEO & Management)
CEO Warren Hinds and his team speak a language that we dumbbell investors love: "shareholder return". The management does not focus on mindless growth at any price, but on margin security, debt repayment and the reliable return of cash to shareholders.
12. the votes of the analysts (consensus & price targets)
The analyst consensus for this small-cap is strong. Most of them rate REPX as "Buy" to "Strong Buy". The average 12-month price target is often in the range of over 35.00 EURwhich, in addition to the fat dividend, offers solid upside potential for the share price.
Closing & Conclusion: Riley Exploration Permian $REPX (+7,02 %)
This is not a stock for the speculative growth side. REPX is the ice cold anchor for the "Side A" of our dumbbell strategy. You're buying a niche Texas player that delivers a free cash flow yield of over 12%, pays a fat covered dividend and is protected by extremely low production costs. If you can withstand the volatility of the oil price and like honest, hard cash flow, you are looking at a fundamental hidden champion.
Brief explanation of the 2021 jump in the chart:
Here's the ice-cold breakdown of what was going on:
1. the reverse merger (the takeover through the back door) Riley Exploration Permian ($REPX) was not even listed independently on the stock exchange at the beginning of 2021. They went public on Wall Street at the end of February 2021 through a so-called "reverse merger". Instead, they merged with a small, already listed company called Tengasco, Inc. (old ticker: TGC) merged. After the deal, the construct was renamed Riley Exploration Permian and the ticker changed to REPX.
2. the 1-for-12 reverse stock split (the chart illusion) Exactly at the time of this merger, a massive 1-for-12 reverse stock split took place. This means that 12 old Tengasco shares became one new REPX share. This step catapults the nominal share price visually extremely upwards in order to list the new company at a respectable price level.
@Dividendenopi
@Tenbagger2024
@Multibagger
@Get_Rich_or_Die_Tryin
@TradingHase
@SAUgut777 and all others