

Hello my dears,
Over the next few days, I will be presenting a few values on the subject of energy. And today we will start with a giant from Brazil.
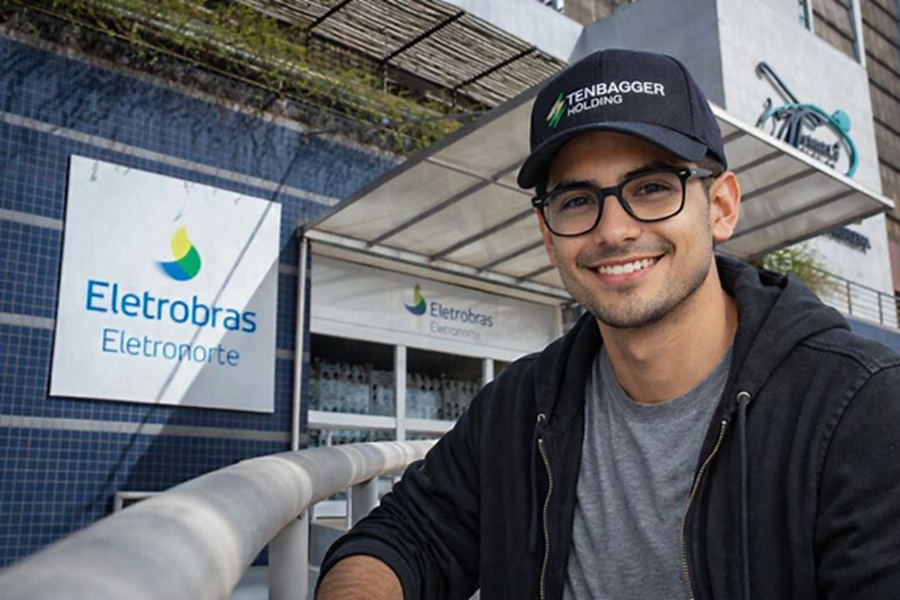
As Juan speaks perfect Portuguese, he was allowed to visit the company.
Due to the number of 🔌 utilities (suppliers) companies, today's presentation is kept very short.
Please leave your opinions in the comments. 🙏
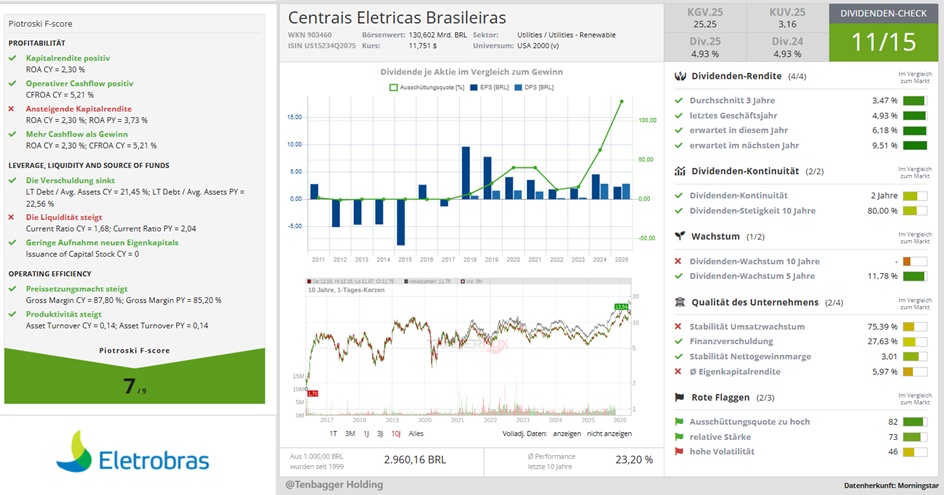
Centrais Eletricas Brasileiras (Eletrobras) specializes in the production, transport and sale of electrical energy. Net sales (including intragroup sales) are broken down by activity as follows:
- Generation of electricity (50.5%);
- Transmission of electricity (25.4%): At the end of 2017, the company owned a network of 63,833 km of transmission lines;
- Distribution of electricity (24.1%).
The electricity is distributed via a network of intermediaries and distributors.
Number of employees: 7,168
Distribution of turnover by business area:
2025 (BRL)
Generation 24.94 billion
Transmission 17.49 billion
Other Activities 464 million
Eliminations -1.61 bn.
Brief Juan summary (AXIA Energia 2025-2028)
Juan pushes up his glasses, looks at the figures and nods: "Full turnaround story. 2025 is the trough, from 2026 everything picks up strongly - EBIT, profit, ROE, FCF. Margins jump upwards, cash flow in 2028 is really strong. The only downer: debt continues to rise. But operationally a clear upward trend."
Market value 176,642
Number of shares (in thousands) 2,855,263
Date of publication 26.02.2026
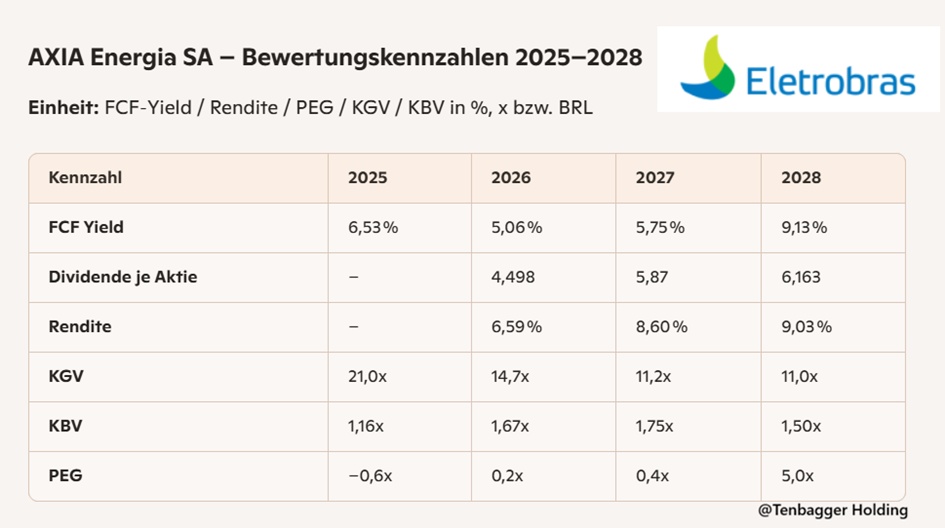
Short Juan summary (valuation 2025-2028)
Juan leans back, taps his tablet twice and grins: "Valuation remains attractive. P/E ratio falls through cleanly, FCF yield rises sharply in 2028. Dividend grows every year, yield will be really juicy. PEG shows: 2026-2027 top valuation, 2028 will be more expensive. Overall: favorably valued with clear cash power."
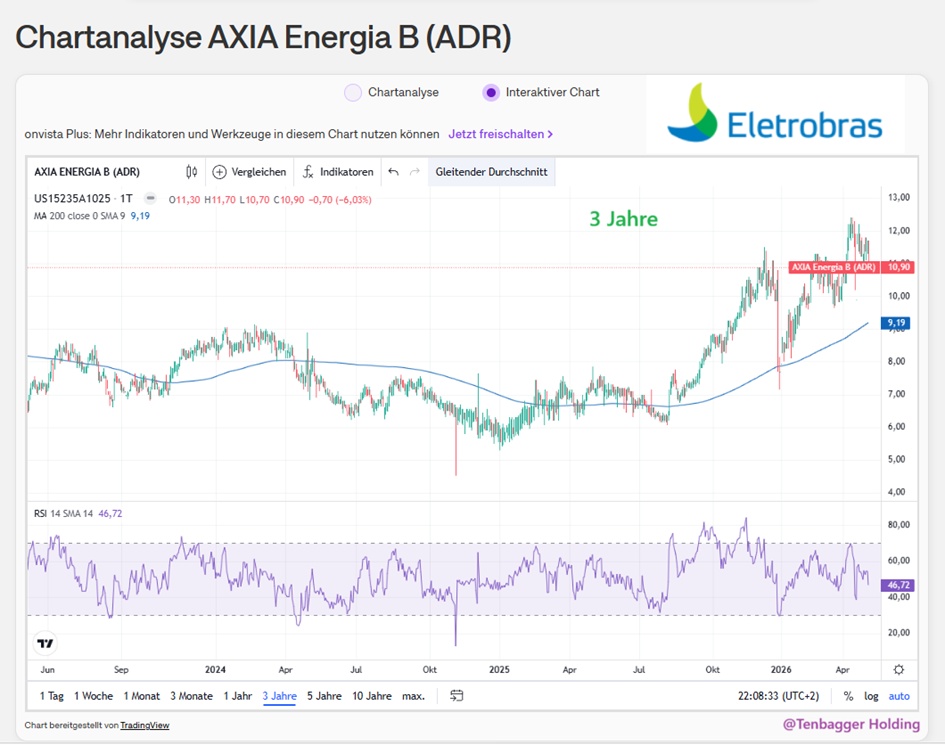
Performance:
1 week +4.64 %
1 month +10.12 %
6 months +15.57 %
1 year +67.15 %
3 years +82.90
PRICE: €9.90 (08.05.2026 at 9:45 a.m.)