6Mon·

Why I invested in CECO right now

Good morning, my dears,


Yesterday I joined CECO $CECO (+1.9%) yesterday.


That's why I wanted to explain my motives to you again today.


CECO has been on my watch for a long time because I think their business model has a lot of potential.


I have already given you a company presentation on CECO.


Why am I investing right now, even though the entire market is going a bit crazy. And there is uncertainty at CECO because of the merger.


CECO Environmental announces strategic merger with Thermon Group, creating a global industry leader in providing mission-critical environmental and thermal solutions

February 24, 2026


The company's share price has fallen by almost 30% since the merger was announced. Although very good figures were presented.


Because it is perhaps human to immediately see the risks and be skeptical.

(Perhaps it is evolutionary and could be due to fear of losses)


⚠️ Risks

  • Dilution: CECO issues shares, diluting existing shareholders (CECO holds 62.5% after merger).
  • Financing risks: The transaction contains a cash component → potentially higher debt.
  • Integration risk: Two companies with different cultures and systems must be merged.


But I clearly see the advantages outweighing the risks. And that's why I have now used the share price slide to enter the market.

"NO RISK, NO FUN"


🔹 Key messages from the CECO - Thermon merger

🧩 Strategic significance

  • CECO and Thermon merge to create a global industry leader for environmental, process heating and thermal solutions.
  • Transaction value: approx. USD 2.2 billion (shares + cash).
  • The combined company will continue to operate under the name CECO Environmental.


🚀 Industrial & technological advantages

  • Adds Thermon's strong position in process heating, heat tracing and temperature management to CECO's environmental and emissions solutions
  • Strengthens presence in long-term growth trends such as energy transition, decarbonization, infrastructure, industrial transformation
  • Offers customers a broader range of mission-critical solutions (air quality, emissions control, water treatment, thermal management)


💰 Financial effects

  • Expected cost synergies: ~ USD 40 million annually within 36 months.
  • Greater diversification through increased share of aftermarket and short-cycle business.
  • Expected double-digit sustainable growth through broader market presence.


👥 Corporate structure & management

  • CEO remains Todd Gleason (CECO).
  • New board includes two Thermon directors.
  • Ownership distribution after closing: CECO 62.5 %, Thermon 37.5 %.

📈 Offer for Thermon shareholders

Three choices per share (with allocation mechanisms):

  • USD 10 cash + 0.6840 CECO shares (default if no election is made).
  • 63.89 USD cash.
  • 0.8110 CECO shares.
  • Implied value of the standard option: USD 63.13 per share (26.8% premium).


📅 Timetable

  • Transaction expected to close mid-2026, subject to regulatory and shareholder approvals


👍 Positive

  • Massive portfolio expansion: Thermon strengthens CECO in process heating, temperature management and heat tracing - all areas with structural growth (energy transition, decarbonization, infrastructure)
  • Greater diversification: more aftermarket sales → more stable cash flows.
  • Economies of scale: USD 40 million synergies improve margins and cash flow.
  • Stronger market position: CECO becomes a global provider of environmental and thermal solutions - an attractive, growing segment.
  • 🎯 Conclusion for CECO shareholders
  • Potentially very value-enhancing in the long term - but integration and debt must be managed properly.


🟧 Overall strategic impact

🌍 Industry position

  • The new CECO will become a leading provider of environmental, emissions and thermal solutions.
  • Strong exposure to energy transition, infrastructure, decarbonization, industrialization - all long-term growth drivers.

💵 Financial impact

  • Synergies + broader customer base + aftermarket share → more stable, higher margins.
  • Potential for double-digit growth, as CECO itself emphasizes


As a short-term GAMECHANGER is that both companies serve the oil and gas industry.


Thermon also serves the semiconductor industry.


My dears,

I would therefore like to briefly introduce you to the Thermon Group in the next part.


I would like to ask you to write your opinion on my new investment in the comments.


Do you share my view that the opportunities and synergies of the merger are greater than the risk?


Two champions have come together here.


$THR

World market leader in industrial process heating


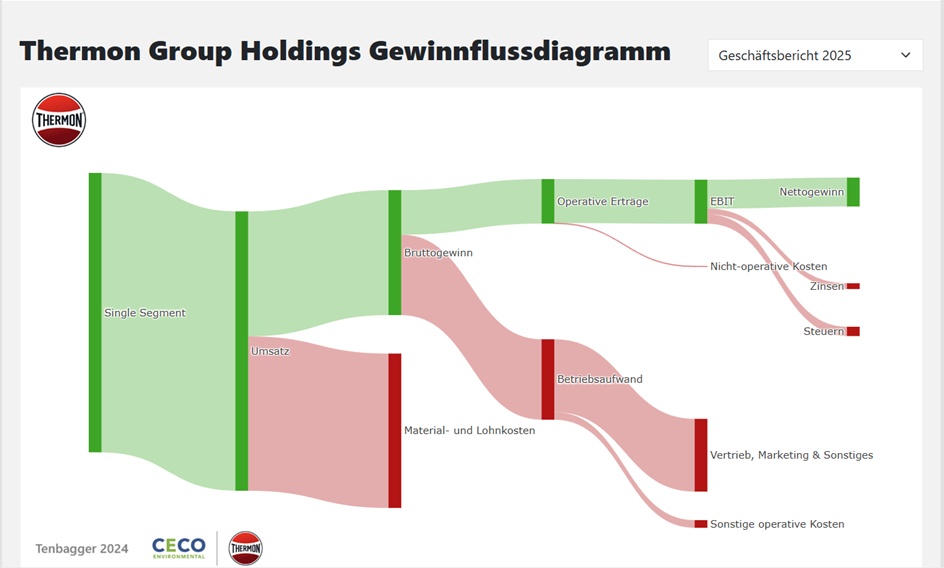
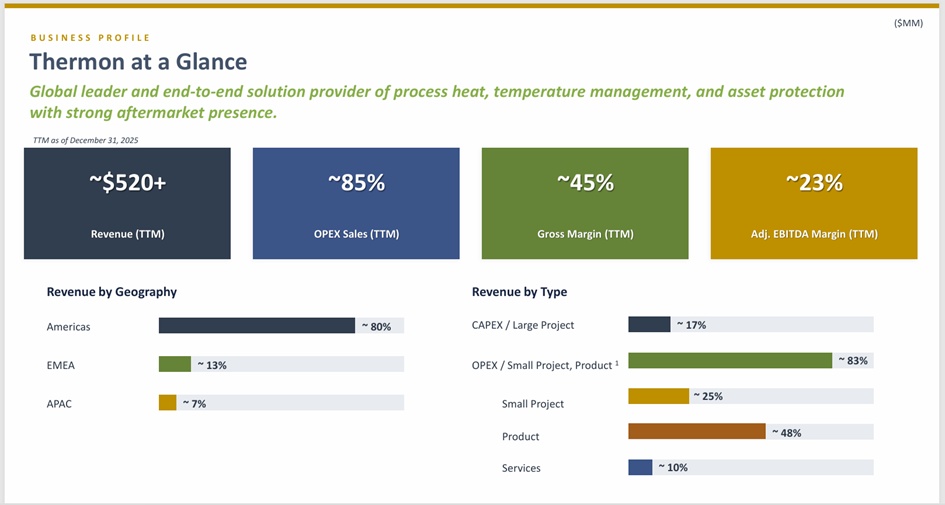
Thermon Group Holdings, Inc. offers solutions for industrial process heating. The company specializes in providing complete solutions for flow assurance, process heating, temperature maintenance, freeze protection and environmental monitoring. The company's advanced industrial heating and filtration solutions span several categories, such as environmental heating (under the Ruffneck, Norsemen and Catadyne brand names), process heating (under the Caloritech brand name), filtration (under the 3L Filters brand name), rail and transit (under the Hellfire, Velocity, ArcticSense and other brand names) and boilers (under the Vapor Power, Precision Boilers and Caloritech brand names). The company offers a comprehensive range of products including heaters, electrode and gas boilers, heating cables, industrial heating blankets and related products, temporary power solutions and tube bundles. It also offers services that include engineering, installation and maintenance services, as well as software that includes design optimization and wireless and network control systems.

Number of employees: 1,568


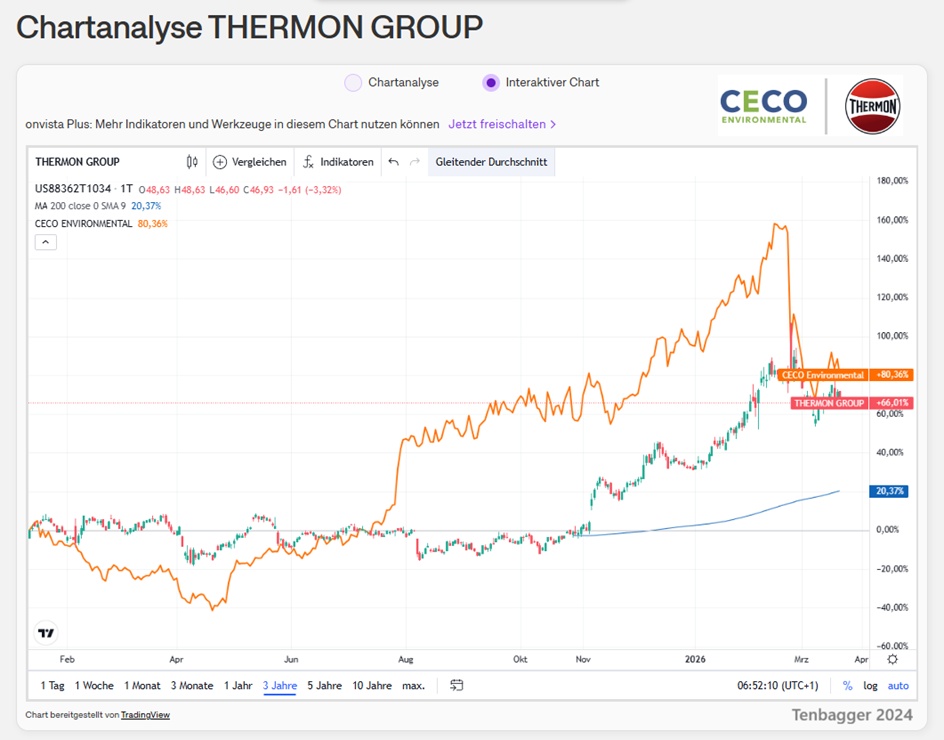
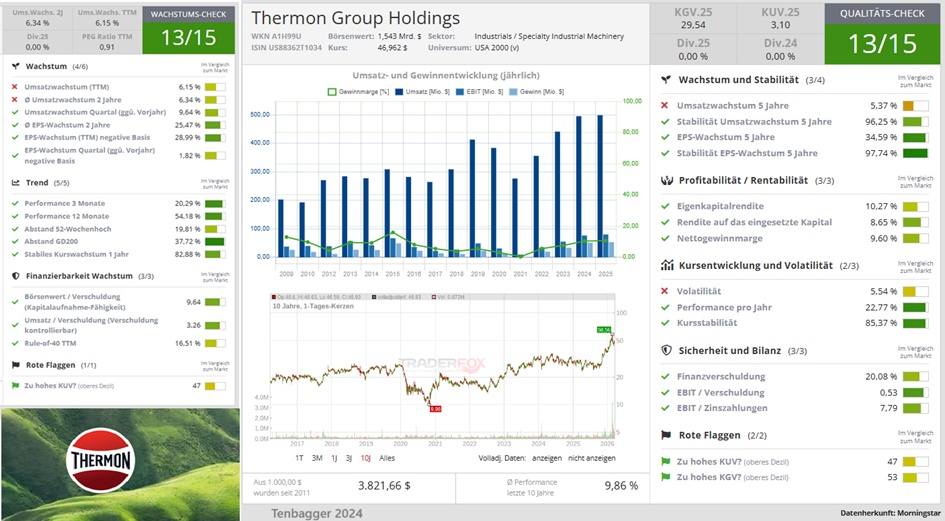
CECO Environmental + Thermon Group — Strategic Combination
attachment
attachment
attachment


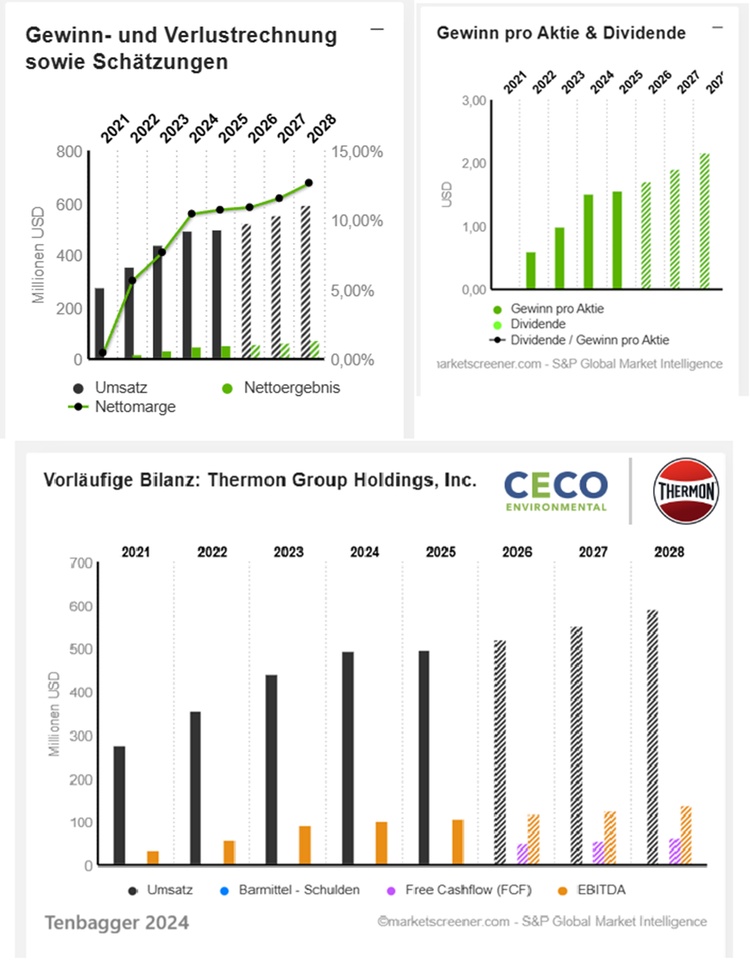
USD in millions

Estimates

Year Turnover Change

2025 498,2 0,72 %

2026 523,3 5,03 %

2027 554,4 5,95 %

2028 591,2 6,64 %


Year EBIT Change

2025 79,76 5,82 %

2026 82,78 3,8 %

2027 94,71 14,4 %

2028 107,7 13,68 %


Year Net result Change

2025 53,52 3,74 %

2026 57,11 6,72 %

2027 64,24 12,49 %

2028 74,76 16,36 %


Net debt not available

Year Free cash flow Change

2026 52,1

2027 56,1 7,68 %

2028 64,6 15,15 %


Year EBITDA margin EBIT margin

2025 21,92 % 16,01 %

2026 22,57 % 15,82 %

2027 22,71 % 17,08 %

2028 23,68 % 18,21 %


Year Earnings per share Change

2025 1,57 3,97 %

2026 1,718 9,43 %

2027 1,914 11,41 %

2028 2,17 13,38 %


Year P/E ratio PEG

2025 17.7x 4.45x

2026 27.3x 2.9x

2027 24.5x 2.1x

2028 21.6x 1.6x

Market value 1,542

Number of shares (in thousands) 32,848

Date of publication 22.05.2025
attachment
attachment


$THR
$CECO (+1.9%)

@Raketentoni

@Get_Rich_or_Die_Tryin

@Klein-Anleger

@Max095

22
31 Comments

profile image
At the current price range, CECO looks rather expensive to fairly valued at most, depending on whether the forecast double-digit growth (sales and earnings) is actually achieved by 2028.

The share is interesting for long-term growth investors, but entry requires a willingness to take risks and confidence in the continuation of the growth story.
•
4
•
profile image
Hello Tenbagger,
exciting update on CECO Environmental (CECO) and the Thermon merger!

On paper and in view of the hoped-for synergies, the story really sounds like a big hit. However, we ran the current figures (as at March 2026) through the grid to see what's really in the balance sheet, apart from the rosy fantasies about the future and the lack of dividends.

And here is the unvarnished reason why we are definitely staying on the sidelines at the moment:

Good things first:
The qualitative growth

The first look at the growth could almost make you weak. CECO has achieved extremely strong sales growth of around 39% (to over USD 774 million) for the full year 2025. The operating margin is currently hovering around the 7% mark. If you add the two together, we end up with a score of 46. A value of well over 25 is a clear sign of very good, qualitative growth. The sales engine is therefore humming along.

The absolute knockout blow:

The missing cash machine

But now comes the hard reality check:
We are looking for real cash machines and not pure sales wonders that end up with hardly any free capital.

CECO is currently valued at a market capitalization of just under USD 1.9 billion. However, the free cash flow (operating cash flow less CapEx) for the full year 2025 was a measly USD 9.6 million.
This results in an FCF yield of a tiny ~0.5%.

For a stock to be considered an attractive investment at all, the FCF yield must crack the 5 % mark; it only becomes really attractive from 8 %. A value of 0.5 % with an optically expensive P/E ratio of around 40 simply means that the company generates far too little hard cash flow in relation to its valuation.

Conclusion:

The acquisition of Thermon also adds further integration risks and potentially new debt to a balance sheet that already generates very little real free cash. As long as the FCF yield does not climb into healthy spheres, CECO will fall through the filter. There is simply too much "story" and too little real cash substance priced in at the moment.
•
3
•
profile image
@Raketentoni It should perhaps also be emphasized that both companies are debt-free. Both are profitable and could theoretically continue to operate as they are and be merged slowly.
••
profile image
@Raketentoni but perhaps I am more optimistic than my friend Prompt
••
profile image
@Raketentoni Mr. Prompt seems to be a typical German. And only moved to Scandinavia. Otherwise I don't understand his pessimism
••
profile image
@Raketentoni
Hello Tenbagger,
haha, touché! Greetings from chilly Denmark! 🇩🇰 I have to agree with you: As far as Scandinavian calmness is concerned, I've actually acclimatized quite well up here. But when it comes to my hard-earned euros, the typical German bean counter immediately comes through again. I simply have zero tolerance for rose-tinted spectacles 😉
But let's stick to the bare facts, because there are two dangerous assumptions hidden in your post that are often paid for dearly on the stock market:
1. "Both companies are debt-free" - This is factually incorrect.
Please take another close look at the balance sheets. CECO Environmental is not debt-free. At the end of 2025/beginning of 2026 alone, it had over USD 210 million in debt on its books.
But the real problem is yet to come: how do you think CECO will pay the enormous cash portion for the Thermon merger (up to USD 330 million in cash)? They have just secured fresh credit for this (including a USD 200 million term loan and substantial backstop facilities of hundreds of millions). Debt will therefore skyrocket once again after the merger. There is absolutely no question of "debt-free" in this deal.
2. "Both generate profits" - book profits are not real cash flow!
This is the absolute core of my strategy: I am not interested in net accounting profits. Book profits can be wonderfully embellished with write-downs and balance sheet cosmetics. I am only interested in the hard reality: free cash flow (operating cash flow minus CapEx).
And here I stick to my "pessimism" - which I prefer to call healthy realism. If CECO Environmental is worth almost USD 2 billion on the stock market, but generates so little real free cash flow for the full year that we end up with an FCF yield of a tiny ~0.5%, then this is not a cash machine. A book profit is of no use to me if at the end of the day there is no real, free cash left in the coffers to grow on our own or to pay off the new debt.
Optimism is a great quality on the stock market - if the foundations are right. But with an FCF yield of 0.5% plus a mountain of new debt for a takeover, my strictest exclusion criteria apply. This is not pessimism, but pure capital protection. "Principle of hope" is simply not a reliable investment strategy.
Let's take another look at the balance sheet in a year or two - maybe they really will have turned the synergies into hard cash flow by then. Until then, I'll enjoy the sidelines and my Smørrebrød. 🥪
•
3
•
profile image
@Tenbagger2024 Both companies are currently de facto debt-free. The combined company will not be.

Due to the predominant credit financing (as Thermon is virtually the same size as Ceco), debt/EBITDA rises from around 1 to over 7!

That is a brutal level of debt in this size class. What's more, it remains more or less an industrial cyclical. In addition, there is the dilution (which may be needed even more in the future if the aggressive tactics of Ceco's management do not work). Everything stands and falls with the realization of the announced synergies of ~ USD 40m in the first 36 months.

As Ceco's sales are strongly project-driven, I do see risks here. The slightest project delay will have a direct impact on debt servicing. There will be virtually no free cash left.

And: I consider such a high level of new debt at the current interest rate level and with the expectation of "higher for longer" due to the crises and macro factors to be quite critical.

Everything here depends on a flawless integration and execution of the existing orders of both, then combined, companies.

Here you are buying trust in the management and the execution of the fursion rather than fundamentals in the current situation.

For me it would be nothing. It's really more of a "top or flop" brand at the moment from my point of view. In any case, you should follow the first few quarters after the merger very closely. As soon as it becomes apparent that synergies, combined sales with customers etc. are not materializing, it is better to pull the ripcord.

If it goes well: you've done everything right.😉

I'll keep my fingers crossed for you in any case, but I'd be completely out of it myself.
•
2
•
profile image
@Tenbagger2024 But they don't want to merge them slowly. Instead, they want to sell the products of both directly to all customers and leverage synergies.
••
profile image
@Get_Rich_or_Die_Tryin Thank you dear, as an individual company I would have invested in both. Because I see both as well positioned, with a growing and broad-based business model. They serve many markets, from the semiconductor industry, oil and gas industry to aerospace. All growth sectors. Why should two companies that were previously successful as individual companies suddenly no longer work as a merged company? Of course, a merger is initially associated with obstacles. A bit like a patchwork family. But as I find that some of the same areas are served, each company can gain new customers. With more locations, even more customers can be served. At the same time, I see cost savings for both in the long term and thus an increase in margins. I don't see Bayer here, which has tied itself to Monsanto. Instead, I see a Chevron and Hess merger. I think both can only win here. But maybe I'm just too optimistic.
•
1
•
profile image
@Get_Rich_or_Die_Tryin A quick merge can only be an advantage
•
1
•
profile image
@Tenbagger2024 As already described: it all depends on the success of the merger. It can either backfire or turn out really well.

In terms of capital, the massive debt is really bad at first. If everything goes smoothly: no problem. Otherwise: a big problem.
••
profile image
@Tenbagger2024 if it works, of course.
••
View all 5 further answers
profile image
I don't understand your trade at the moment. Dilution is virtually the order of the day and our colleagues have promptly fallen from all clouds. Nevertheless, you are taking a big risk.
I'm keeping my fingers crossed that you've made the right decision, my dear. 👍🏼
•
2
•
profile image
@TradingHase I think the 30 % price loss has already priced in a lot. I think those who got in at the top are worse off. Look at the dilution at Iris, nobody seems to have any problems with that.
••
profile image
@TradingHase I have not yet found an analyst opinion that says sell. So far only 7 that recommend buying
••
profile image
@TradingHase Rating Ceco Environmental share
The rating is calculated based on the average rating of 6 analysts for Ceco Environmental. information
Ceco Environmental shares are currently rated by 6 analysts. The average rating is 4.50 points, the target price is 78.83 USD. Of these, 100 % recommend Buy, 0 % Hold and 0 % Sell. Overall, the analysts' assessment is predominantly positive
••
profile image
@Tenbagger2024 but you also know just as well that analysts are opportunists and "fall over" in rows when things don't go their way for a few weeks. Personally, I don't really follow them if only a few firms cover the stock.
•
1
•
profile image
@Dividendenopi I didn't base my purchase on the analysts either. I just threw it out there because of all the criticism, nothing more. The purchase was my own decision, without taking ratings into account. But apparently I seem to be the only one here who is not so pessimistic about the purchase.
•
1
•
profile image
@Tenbagger2024 then that's the way it is for you and you certainly don't have to "apologize" or even justify a decision with this argument. Everyone here has their own way of thinking and you are certainly not buying to please others.
•
1
•
profile image
@Dividendenopi I could list you enough shares where dilution has taken place. Or companies that will not become profitable in the next few years. But which continue to rise in performance. But when a company that is almost 100 years old merges, dilutes and takes on debt. Then suddenly everyone here is skeptical. And sees the company as being on the brink of collapse. Even though the business model is right, the company is in growth sectors, with recurring sales, double-digit EBIT margins and the order books are full. All I can say is, but the main thing is to invest in altcoins and rocket stations. And still adore Elon.
••
profile image
@Dividendenopi or are stuck in some weird quantum things. Where nobody knows whether they will ever be profitable. And then cry out loudly here about dilution. My best man, I'm just getting upset
•
1
•
profile image
@Tenbagger2024 everyone is rightly skeptical. Because both were previously marginally indebted. And they are not producing cash on a continuous basis. Or the growth is groundbreaking.

You can get upset. But ignoring facts is not healthy in my view either.
••
profile image
@Get_Rich_or_Die_Tryin Well, if double-digit profit growth is nothing. I must really be missing something
•
1
•
View all 2 further answers
My dear. Keep it up
••
Join the conversation