

Good morning my dears,
A few months ago I introduced you to EZCORP $EZPW (-0.58%) here.
( Company presentation: https://getqu.in/3uE47L/ ).
The share continued to perform well after the presentation. That is why there is another company from this sector today.
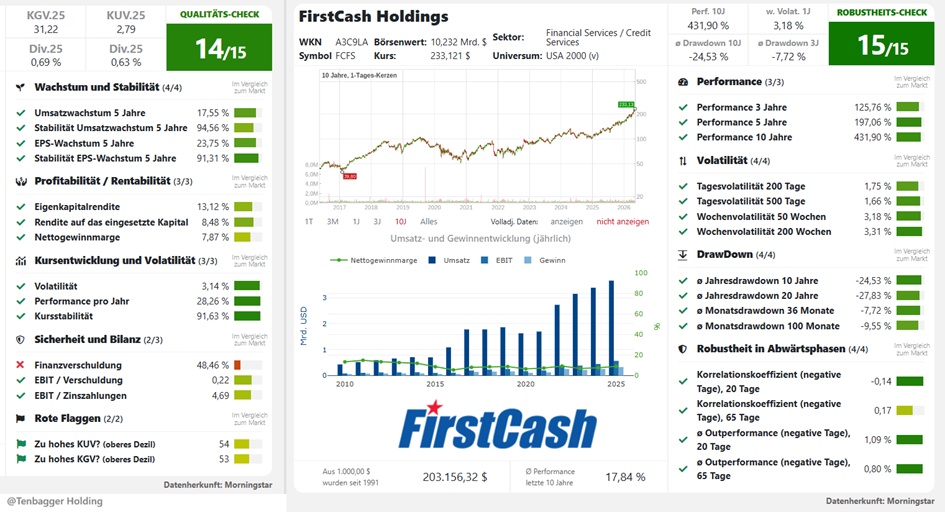
Like EZCORP, it is a robust share for me, as the 15 out of 15 points in the Traderfox Robustness Check show. Achieving 15 points here is a rarity.
That's why FirstCash $FCFS (+0.12%) could perhaps be a CORE share for you.
As the global market leader in the pawnbroking business, the company is benefiting from economic uncertainty as demand for small loans and cheap second-hand goods increases in times of high inflation and restrictive banking policies. Through aggressive expansion into underserved markets in Latin America and the integration of digital point-of-sale financing (AFF), FirstCash is continuously tapping into new, high-margin customer groups. FirstCash offers a virtually risk-free credit model, while high operating margins are rare in the retail sector.
FirstCash Holdings, Inc. is an international operator of pawnshops with more than 3,000 locations that buy and sell a wide range of jewelry, electronics, tools, appliances, sporting goods, musical instruments and other merchandise, and make small, non-recourse pawn loans secured by pledged movable property. Through its wholly owned subsidiary American First Finance (AFF), the company also offers installment plan and financing solutions for consumer goods and services. The company operates in four segments: Pawnbroking in the United States (U.S. Pawn); Pawnbroking in Latin America (LatAm Pawn); Pawnbroking in the United Kingdom (U.K. Pawn); and Retail Point of Sale Payment Solutions (American First Finance or AFF). The company is also a provider of point-of-sale payment solutions for retailers of consumer goods and services. The point-of-sale retail payment solutions business is comprised solely of AFF's operations, which focus on installment plan products and the provision of other payment options for retail finance.
Number of employees: 20,000
FirstCash reports record first quarter results; Revenue up 26%, leading to 30% earnings per share growth; Pawn receivables growth accelerates; 2026 revenue guidance raised
April 23, 2026 06:00 ET | Source: FirstCash, Inc.
FirstCash berichtet über Rekordergebnisse des ersten Quartals;
IR — Investor Relations_May 2026_vFINAL
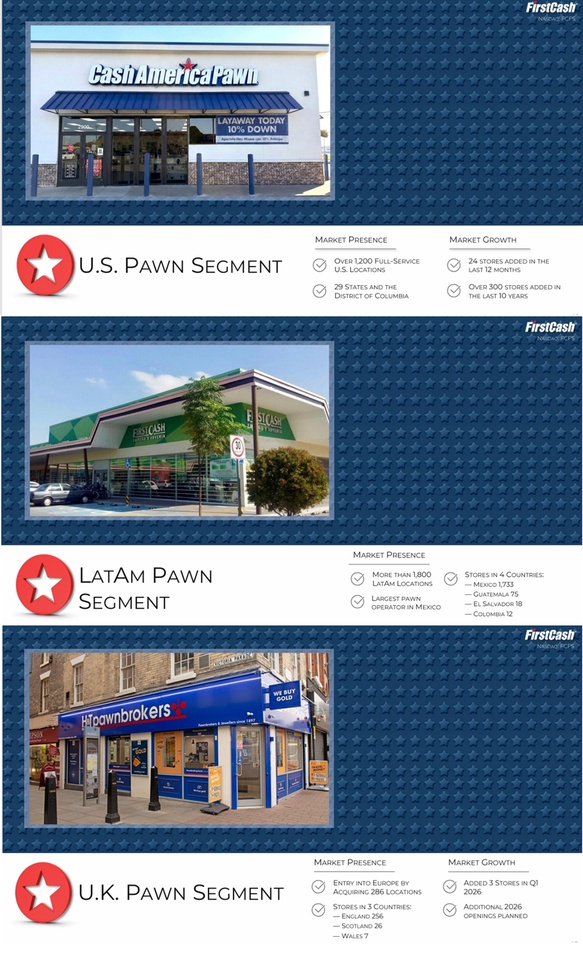
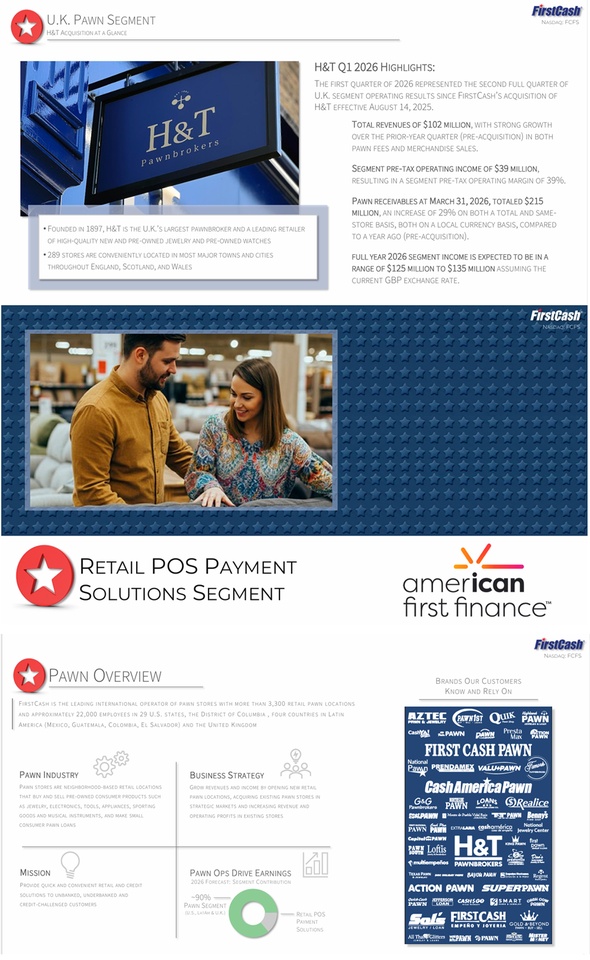
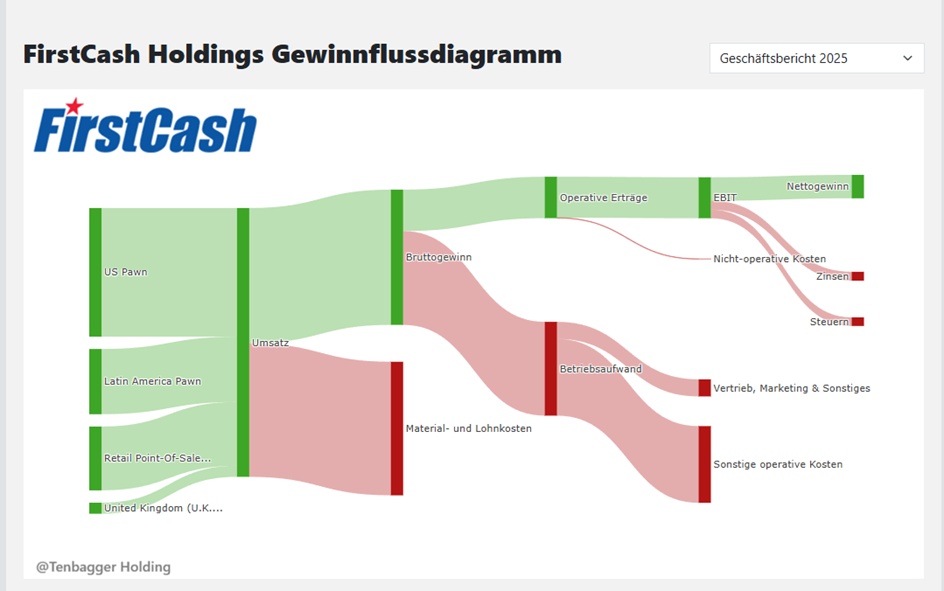
Revenue distribution by division:
2025 (USD)
U.S. Pawn 1.75 bn.
Latin America Pawn 890 million
U.K. Pawn 151 million
Retail POS Payment Solutions 870 million
Intersegment Eliminations -2.74 million
Geographical distribution of sales:
2024 (USD)
Other Latin America 47.46 million
U.S. 2.58 billion
Mexico 764 million
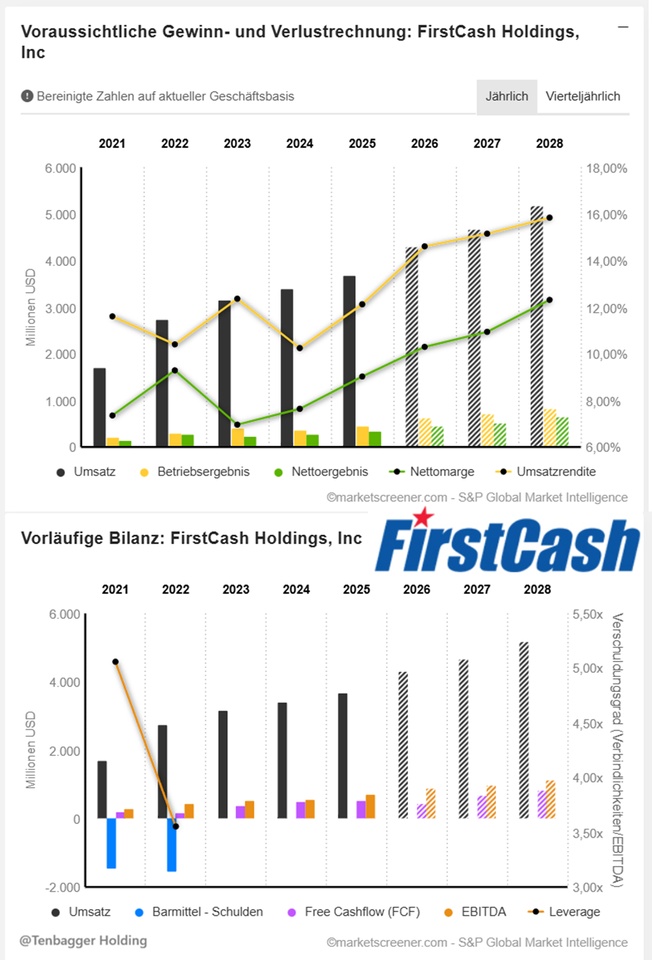
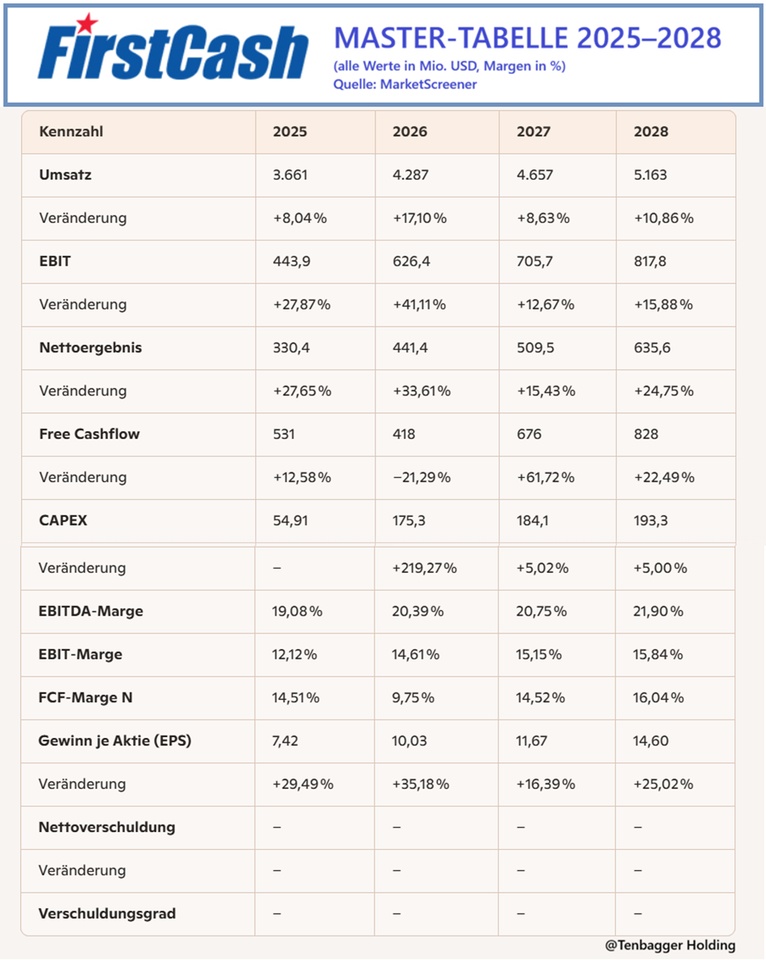
💬 Juan summary of the key financial figures (2025-2028)
"FCFS delivers a really clean set of figures. Sales are growing at a stable double-digit rate, but the real star is the margin expansionEBIT margin rises from 12% to almost 16%, which is impressive for a deposit/retail hybrid model.
Net profit is following suit and EPS is growing at double-digit rates every year - even +25% in 2028. Free cash flow fluctuates, but the trend is clearly pointing upwards and will end 2028 at a strong level.
Net debt is zero, operationally the model appears robust and cash-strong. Overall: Solid growth story with steady improvement in profitability.
No hype - simply a clean-running cash generator."
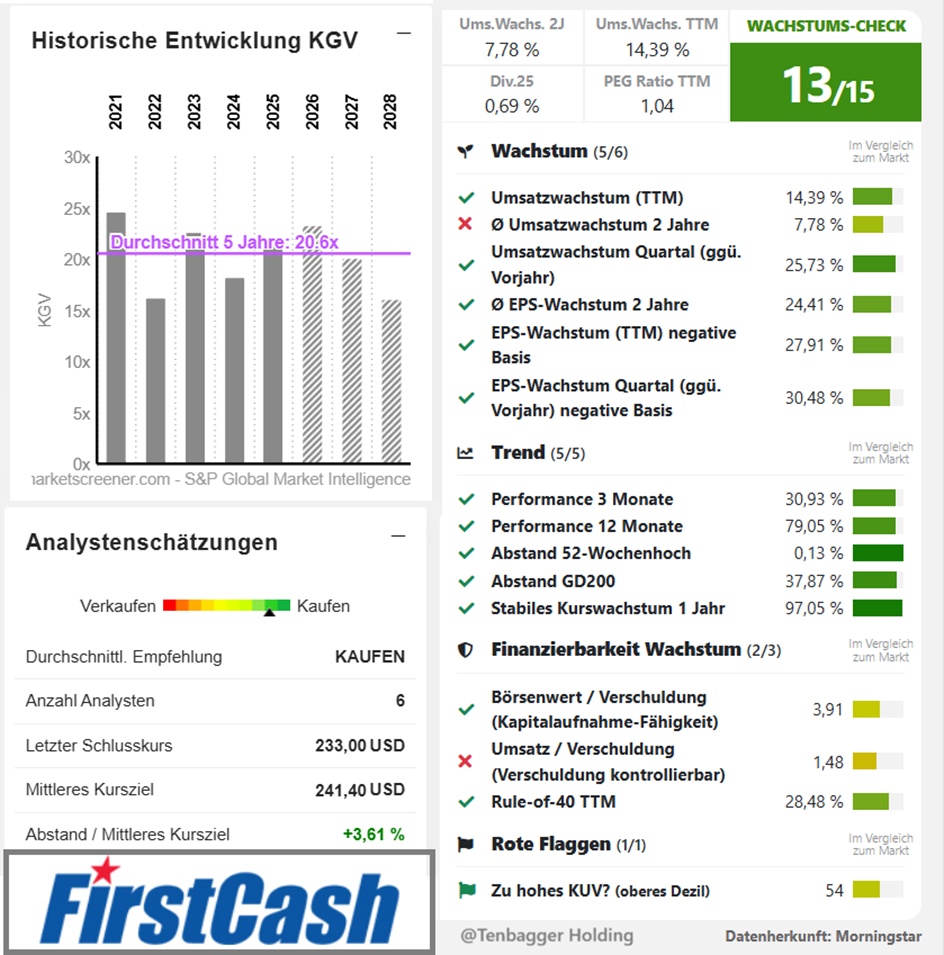
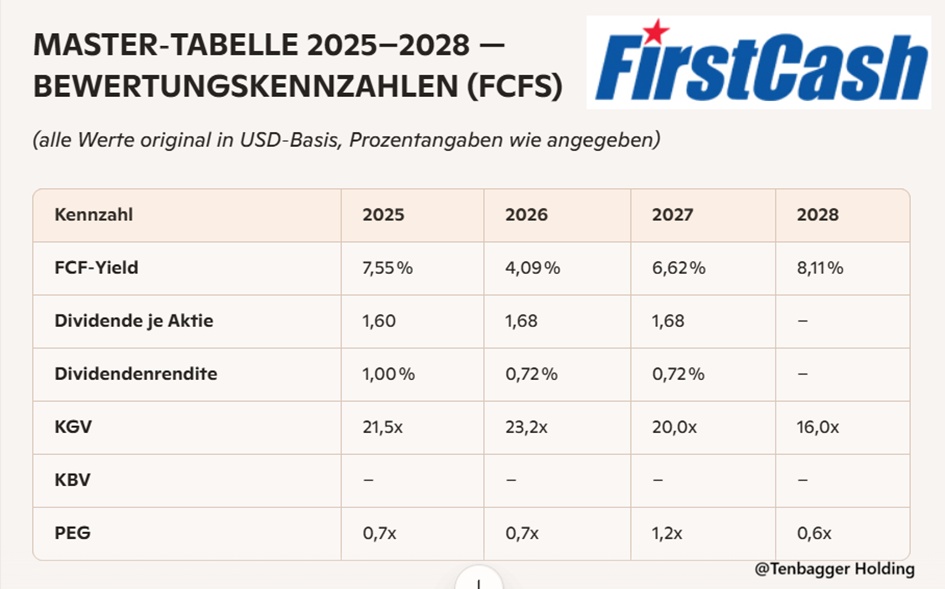
Market value 10,214
Number of shares (in thousands) 43,837
Date of publication 05,02,2026
Short summary (Juan style)
"Valuation remains relaxed: P/E ratio falling towards 16xPEG is mostly hovering in the undervalued rangeand the FCF yield rises to over 8%. Dividend is nice, but not the driver. Overall: solid value base with cash flow punch."
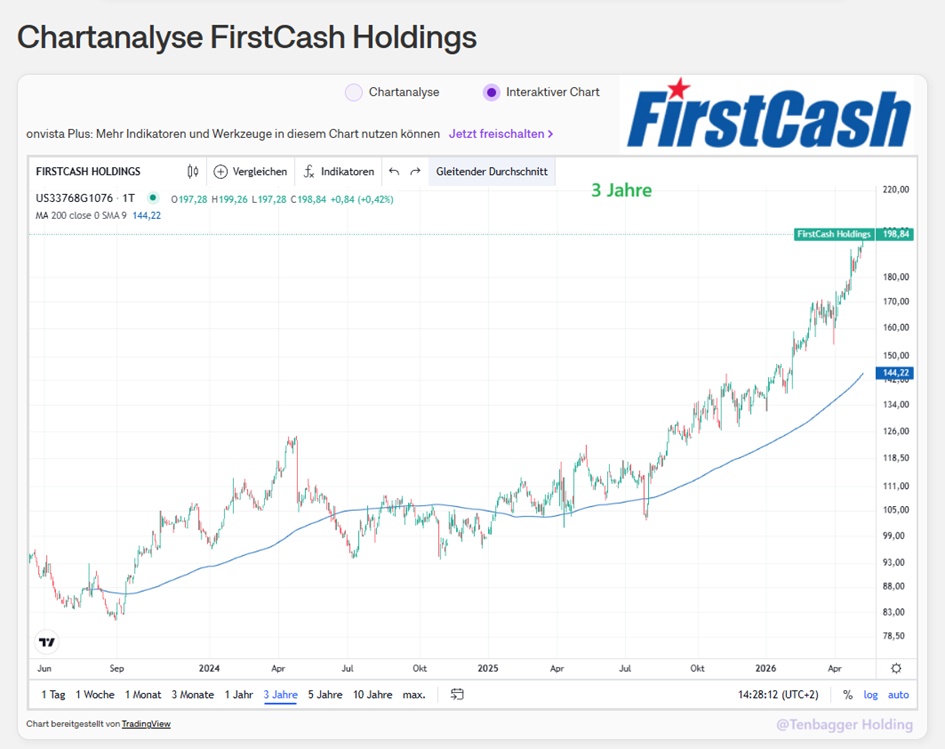
Share price: €196.50 13.05.2026 at 9:22 a.m.


