
Plug Power, the U.S. hydrogen and fuel cell specialist, has become a penny stock on the stock market: The stock closed at $1.50 (+3.4%) on the Nasdaq on November 9, 2026, and is thus trading about 65% below its 52-week high of $4.33 from June 2026. Ironically, the company is now reporting its best quarterly results in years. In the third quarter of 2026, revenue rose 13% to $200.6 million, slightly exceeding analysts’ expectations. The gross margin improved from −68% in the prior year to around −3%, cash outflow fell to a record low of $28 million, and for the first time in a long while, Plug Power did not have to raise fresh capital from shareholders. However, the reported net income of $99.8 million is merely a paper gain resulting from the revaluation of convertible bonds and warrants; on an operating basis, the company continues to post a loss of $75.3 million. Management confirms the forecast of 15% to 16% revenue growth for 2026 and aims to achieve positive EBITDAS for the first time in the fourth quarter. Analysts’ average estimate is around $3.39, though the range extends from $1.20 to $7.00. From a technical analysis perspective, the $1.77 level will determine whether the fundamental turnaround also leads to a trend reversal on the chart.
Key Points
- Q3 2026: Revenue of $200.6 million (+13%), gross margin of approximately −3% after −68% in the prior year
- Operating loss of $75.3 million, down from $348.8 million; net income of $99.8 million driven solely by paper gains
- Cash outflow of $28 million (record low), no new capital raised during the quarter
- Forecast confirmed: 15 to 16% revenue growth in 2026, positive EBITDAS in the fourth quarter
- Analysts: Average price target around $3.39 (19 analysts, consensus “Hold”), range $1.20 to $7.00
- Chart levels: Trigger at $1.77, targets at $2.54 and $4.63, support at $1.11, previous year’s low at $0.689
What are Plug Power’s current key metrics?
Plug Power stock closed at $1.50 (+3.4%) on the Nasdaq on November 9, 2026, trading just above its 52-week low of $1.30.
In euros, the stock costs around 1.35 EUR. With approximately 1.40 billion shares outstanding, Plug Power has a market capitalization of about 2.1 billion USD. The company does not pay a dividend; instead, the number of shares has multiplied in recent years due to capital increases.
What news is currently driving Plug Power’s stock?
Plug Power stock is currently being driven primarily by the Q3 results released on November 9, 2026: revenue above expectations, a nearly break-even gross margin, and cash outflow at a record low.
Prior to that, the stock had slipped to a 52-week low in October after Morgan Stanley and Susquehanna lowered their price targets. The next event, the Plug Symposium on November 19, 2026, will see management present its plans for the coming years. My analysis of Siemens Energy Aktie —where the market ultimately rewarded the turnaround spectacularly.
What does Plug Power’s management have to say about the Q3 results?
CEO Jose Luis Crespo sees the Q3 results as evidence of continued progress toward a stronger and more profitable Plug Power: higher revenue, better margins, and significantly lower cash outflow thanks to disciplined management.
The focus remains on optimizing the cost structure, fulfilling commitments to customers, and building sustainable growth. The cost-cutting and restructuring program “Project Quantum Leap” reduced operating costs in the third quarter by about 69% to $69.9 million.
What went well: In the forklift business, Plug Power delivered 1,136 fuel cell powertrains (GenDrive)—110% more than in the previous year—and the service margin was approximately 31%. In hydrogen sales, the gross margin improved from approximately −79% to approximately −52%, and revenue rose by 6% to $38.1 million. New orders were secured for electrolysers, including 280 MW from Arcadia eFuels for a project in Denmark and 50 MW from Orica for the Hunter Valley Hydrogen Hub in Australia.
The catch: The net profit of $99.8 million is not a true profit. It stems from non-cash accounting gains of approximately $192 million, as convertible bonds and warrants are valued lower following the stock price decline. On an operating basis, Plug Power posted a further loss of $75.3 million, with diluted earnings per share at $0.00. Free cash flow has shrunk from $368.5 million to $134.1 million since the beginning of the year.
Outlook: Plug Power confirms revenue growth of 15 to 16% for 2026. Based on $710 million in 2025, this corresponds to approximately $816 million to $824 million, leaving roughly $274 million to $281 million for the fourth quarter. EBITDAS is expected to be positive for the first time in the fourth quarter, while cash outflow is expected to remain roughly at the third-quarter level. Management plans to provide further details at the Plug Symposium on November 19, 2026.
What does Plug Power do—and how does the company make its money?
Plug Power is a U.S. company based in New York State that generates revenue from fuel cell powertrains for forklifts, hydrogen supply, and, increasingly, electrolysers for the production of green hydrogen.
Founded in 1997, the company employs approximately 2,300 people and, according to its own figures, has delivered more than 76,000 fuel cell systems and 280 hydrogen refueling stations. Plug Power is considered the world’s largest consumer of liquid hydrogen.
Fuel Cells for Logistics: Its core business consists of GenDrive powertrains for forklifts in large warehouses, such as those at Amazon and Walmart. Instead of batteries, the forklifts refuel with hydrogen in just a few minutes. In addition, the company offers maintenance contracts and leasing models (Power Purchase Agreements) that allow customers to use the systems without purchasing them.
Hydrogen Supply: Plug Power produces and delivers the hydrogen for its customers itself, currently at a capacity of about 40 metric tons per day. This business was a money-loser for a long time because the hydrogen was purchased at a higher price than it was sold for. In the third quarter, it generated $38.1 million in revenue with a margin of approximately −52%.
Electrolyzers (GenEco): The beacon of hope. Electrolyzers use electricity to split water into hydrogen and oxygen. According to Aktienfinder, this segment generated approximately $198 million in revenue over the past twelve months through June 30, 2026, making it the largest segment. Projects are underway with, among others, Galp in Portugal (100 MW), Iberdrola and bp in Spain (25 MW), and Arcadia eFuels in Denmark (280 MW).
Here’s how Plug Power makes money: Revenue comes primarily from the sale of equipment, services, and hydrogen. The problem: For a long time, manufacturing and delivery costs exceeded what customers paid. My analysis of a Nel ASA Aktie —there, hydrogen euphoria has long since given way to brutal disillusionment.
Fundamental Analysis: What Is the Plug Power Stock Worth After the Margin Turnaround?
Fundamentally, Plug Power stock cannot be valued using traditional metrics, as the company has been posting losses since its founding—therefore, margins, cash outflow, and liquidity are the key factors.
There is no P/E ratio. In terms of the price-to-sales ratio, Plug Power stands at about 2.7, based on a market capitalization of approximately $2.1 billion and revenue of about $768 million over the past twelve months. According to Aktienfinder, a reliable fair value cannot be calculated due to the lack of profit. The cash flow statement therefore provides a better picture of the company’s financial health than any valuation metric.
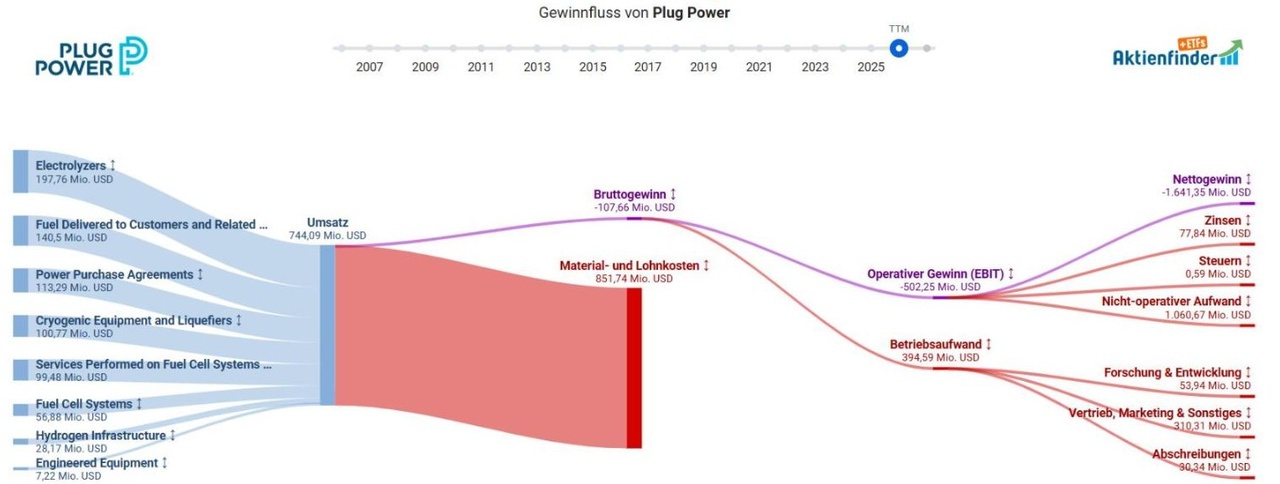
Cash Flow Statement: The chart tracks every dollar of revenue from the past twelve months through June 30, 2026, from left to right. According to Aktienfinder, approximately $744 million in revenue was generated, with the largest portions coming from electrolyzers ($198 million), hydrogen deliveries ($141 million), leasing models ($113 million), and cryogenic technology ($101 million). The cash flow reverses right from the start: material and labor costs of approximately $852 million exceed revenue, resulting in a negative gross profit of about −$108 million. This is followed by operating expenses of approximately $395 million, resulting in an operating loss of about $502 million. Depreciation of assets, interest, and other extraordinary expenses totaling over $1 billion round out the losses. The bottom line was a loss of approximately $1.64 billion. In short: Through mid-2026, Plug Power has lost money on every product it sold.
Revenue Trends: This is exactly where the third quarter comes in. Revenue rose 13% to $200.6 million, driven primarily by equipment sales ($105.7 million), services ($29.0 million, +47%), rental models ($27.7 million), and hydrogen ($38.1 million). After nine months, revenue is up by about 12% to $542.4 million. At the same time, cost of sales fell from $297.2 million to $206.0 million, causing the gross margin to jump from −68% to around −3%. For the full year 2025, revenue totaled $710 million (+13%). For the forecast of 15 to 16% growth for 2026 to be met, the fourth quarter must be the strongest in the company’s history, with revenue of approximately $274 to $281 million, which is about a quarter more than the 225.2 million USD recorded in the same quarter of the previous year.
Liquidity and Dilution: As of the end of September, Plug Power had $134.1 million in freely available funds and an additional $468.9 million tied up as collateral for projects and leasing models. This is offset by convertible bonds with a book value of $470.7 million and financing obligations of $194.7 million. With a cash outflow of approximately $28 million per quarter, the cash cushion is mathematically sufficient for a few quarters; however, a drop back to previous levels of over $100 million would be dangerous. For shareholders, financing has been costly so far: The number of shares outstanding now stands at around 1.40 billion, and in February 2026, the authorized share capital was doubled to 3.0 billion shares. The October 2025 warrants alone entitle holders to purchase 185.4 million shares, and there are also convertible bonds totaling $375 million maturing in 2033.
Comparison with the competition: In the hydrogen and fuel cell sector, the gap is enormous. Bloom Energy increased its revenue by 138% to $1.24 billion in the third quarter of 2026, is profitable on an operating basis with a gross margin of 33.8%, and is valued at approximately $57 billion—a multiple of its revenue. My analysis of Bloom Energy Aktie. Nel ASA reported a 63% decline in revenue to NOK 112 million for the third quarter, but new orders of NOK 253 million (+339%). Like Plug Power, Ballard Power trades below $2; ITM Power recently raised its revenue forecast. By comparison, Plug Power is cheaply valued with a price-to-sales ratio of about 2.7—but only because the company isn’t making a profit yet.
Plug Power Stock Price Targets and 2026 Forecast
Analysts see an average price target of around $3.39 for Plug Power stock; however, from a technical analysis perspective, the stock must first sustainably break above the $1.77 mark to initiate a trend reversal.
The range of price targets is extreme: Morgan Stanley sees only $1.20, while H.C. Wainwright, on the other hand, sees $7.00. Just how wildly a speculative growth stock can swing back and forth between euphoria and a crash is also illustrated by my analysis of D-Wave Quantum Aktie.
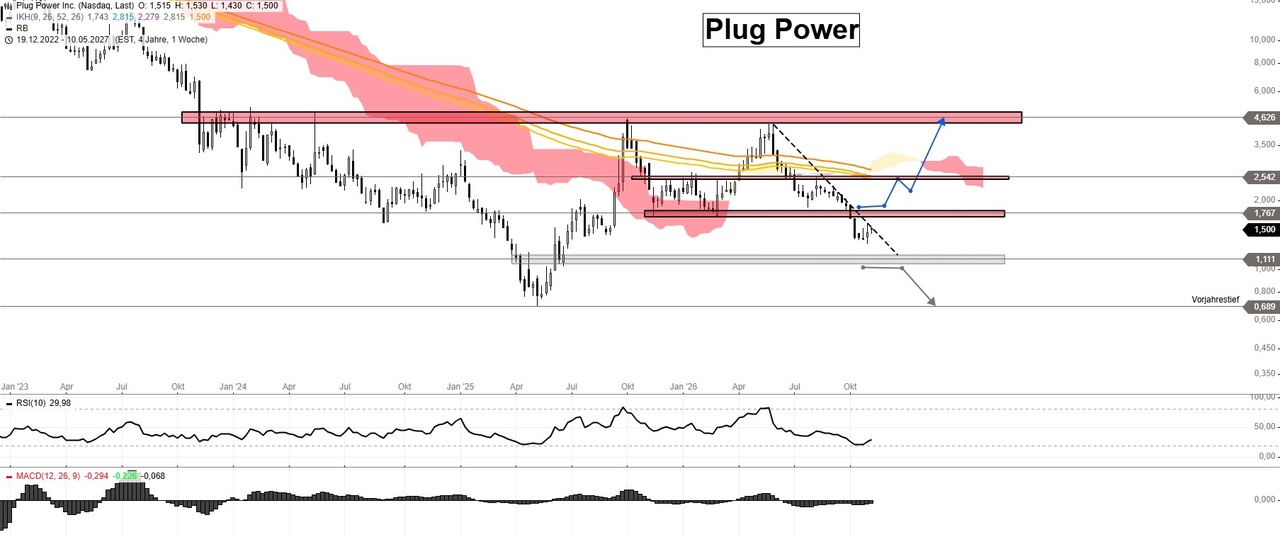
Key price levels:
- 52-week high: $4.33 (June 2026)
- Current price: $1.50 (Nasdaq close on Nov. 9, 2026, +3.4%), approximately €1.35
- First resistance and trigger level: $1.77 (red zone, last breached in October 2026)
- Second resistance: $2.54 (red zone, moving average range)
- Third resistance: $4.63 (red resistance zone, highs from 2024 and 2025)
- Critical support level: 1.11 USD (gray support)
- Target in the event of a break: Previous year’s low at $0.689 (May 2025)
Analyst price targets:
- Average price target: approx. $3.39 (19 analysts, consensus: Hold; MarketScreener average: $3.387, stockanalysis average: $3.39)
- H.C. Wainwright: Buy, $7.00 (September 29, 2026)
- Clear Street: Buy, $3.50 (April 28, 2026)
- Susquehanna: Neutral, $1.75 (October 14, 2026, previously $2.50)
- Morgan Stanley: Underweight, $1.20 (October 14, 2026, previously $1.65)
Chart Analysis:
Is there a trend reversal on the charts as well? Plug Power’s weekly chart shows a stock that has been in free fall for years. After plummeting to the previous year’s low of $0.689 in May 2025, a wild rally followed, taking the stock up to the red resistance zone at $4.63, where it failed to break through in October 2025 and again in June 2026. Since then, the stock has plummeted again along a falling downtrend line, and in October, the price also broke through the $1.77 zone. The stock is currently trading at $1.50 below the Ichimoku cloud and well below the moving averages in the range of approximately $2.30 to $2.80. The RSI(10) stands at 29.98, close to the oversold zone, while the MACD is slightly negative. Sellers are in control, but their pressure is noticeably easing.
A sustained upward move to $2.54 and then beyond to $4.63 is certainly conceivable. However, to achieve this, the stock must first sustainably break above $1.77. Only then would the downtrend line be broken, clearing the path toward $2.54. According to my chart, a pullback is likely to occur there before the stock, if successful, dares to make the big leap to the red resistance zone at $4.63. That would represent more than a tripling from the current price.
As long as the stock remains above $1.11, it shows slightly bullish tendencies. Below $1.11, however, the stock is likely to head back toward last year’s low of $0.689. At that point, at the latest, the stock would also fall back below the $1 mark, which is important for the Nasdaq. For me, only a procyclical long position is an option—that is, only once the market confirms the turnaround with a rise above $1.77. Overall, both the business and the stock itself are highly speculative and not for the faint of heart.
Opportunities and Risks of Plug Power Stock
Opportunities:
- ✅ Gross margin improved from −68% to around −3%; cash outflow at a record low of $28 million
- ✅ Positive EBITDAS targeted for the fourth quarter of 2026
- ✅ Forklift drive systems up 110%, service margin around 31%
- ✅ Electrolyzer orders (Arcadia 280 MW, Orica 50 MW), pipeline of approximately $8 billion
- ✅ Price-to-sales ratio of only about 2.7; RSI near oversold territory
- ✅ A rise above $1.77 opens the way to $2.54 and $4.63
Risks:
- ⚠️ Operating loss of $75.3 million; net income consists solely of book profit
- ⚠️ Free cash flow has shrunk to $134.1 million
- ⚠️ Significant dilution: 1.40 billion shares; authorization doubled to 3.0 billion
- ⚠️ Share price only 50% above the Nasdaq minimum of $1
- ⚠️ Forecast requires a record quarter with revenue of approximately $274 million to $281 million
- ⚠️ A break below $1.11 opens the way down to $0.689
Conclusion: Plug Power Stock—Turnaround Achieved or Penny Stock Trap?
Plug Power delivered its best operating performance in years in the third quarter of 2026, but the turnaround isn’t complete yet: Only a sustained rise above $1.77 would confirm it on the chart as well.
The progress is impressive. The gross margin jumped from −68% to around −3%, cash outflow hit a record low of $28 million, and for the first time in a long while, the quarter did not require fresh capital from shareholders. If the company achieves the announced positive EBITDAS in the fourth quarter, it would be a true milestone for a company that has been posting losses for nearly 30 years.
On the other hand, we must take an honest look at the risks: Net income is merely a book profit; Plug Power continues to burn cash on an operational basis; free cash flow has shrunk to $134.1 million; and every new round of financing further dilutes shareholders. The stock price of $1.50 is now only 50% above the Nasdaq minimum threshold of $1. From a technical analysis perspective, a sustained upward move to $2.54 and beyond to $4.63 would be entirely conceivable if the $1.77 level is sustainably breached. As long as the stock trades above $1.11, it shows slightly bullish tendencies. Below that level, there is a risk of a drop back to last year’s low of $0.689. For me, only a procyclical long position is worth considering. Plug Power stock is and remains highly speculative and not for the faint of heart.
Anyone looking for a calmer alternative with a reliable dividend after so much excitement should take a look at my analysis of Deutsche Telekom Aktie —there, consistency counts more than hope.
Sources
- Plug Power Press Release: Third Quarter 2026 Results (November 9, 2026, SEC Form 8-K)
- Plug Power Press Release: Business Progress, Q3 Date, and Plug Symposium (October 15, 2026, SEC Form 8-K)
- Plug Power Invitation to the 2026 Special Shareholders’ Meeting (SEC DEF 14A)
- Plug Power Investor Relations: Press Releases and Financial Reports
- Nasdaq Closing Price for Plug Power (PLUG) on November 9, 2026: $1.50 (+3.45%), previous day $1.45, 52-week range: $1.30 / $4.33, previous year’s low: $0.69 (Alpha Vantage weekly prices and FMP profile, reconciled); Euro price from Tradegate (Nov. 9, 2026) and Aktienfinder (Nov. 10, 2026)
- MT Newswires via MarketScreener: Plug Power Q3 Revenue Rises (November 9, 2026), FactSet consensus $198.4 million; StockStory via Yahoo Finance: Consensus $198.2 million, post-earnings price (November 9, 2026)
- Analysts: MarketScreener (average $3.387, 19 analysts) and stockanalysis.com (average $3.39); MarketBeat and Investing.com: Morgan Stanley, Susquehanna (October 14, 2026), H.C. Wainwright (September 29, 2026), Clear Street (April 28, 2026)
- MarketBeat: Plug Power Shareholders Approve Share Increase to 3B (February 15, 2026)
- Mercom: Plug Power Q4 2025 Revenue (March 6, 2026)
- Bloom Energy Press Release: Q3 2026 Results (October 22, 2026); Nel ASA: Third-Quarter 2026 Results (October 15, 2026); ITM Power: FY26 Revenue Guidance Raised (RNS); FMP Profiles: Bloom Energy and Ballard Power
- Google Trends, Google Ads Keyword Planner (Germany), as of November 10, 2026
- Stock3: Weekly chart for Plug Power Inc. (Nasdaq, USD), as of November 10, 2026
- Aktienfinder: Income Statement (last twelve months through June 30, 2026) for Plug Power, as of November 10, 2026
This is not investment advice—all information is provided solely for financial education purposes.
What are your current thoughts on $PLUG (-1.75%)?

