Hello my dears,
While the championship starts today, there are still a few qualifying matches going on in the background.
For this reason, Juan has also arrived back in the USA today.
And would like to introduce you to a possible participant.
I already told you about the company 9 months ago.
(to be found in the forum)
Please write us in the comments if you
Astronics $ATRO (+0.47%) would like to see them play in the championship.
The small-cap company Astronics Corporation is a provider of leading-edge technologies to the global aerospace, defense and electronics industries. The company's products and services include advanced power generation, distribution and motion systems, lighting and security systems, avionics products, systems and certification, aerostructures and automated test systems. The company operates in two segments: Aerospace and Test Systems. The Aerospace segment develops and manufactures products for the global aerospace industry. Its product lines include lighting and safety systems, electrical power generation, distribution and seat motion systems, aerostructures, avionics products, system certification and other products. The Test Systems segment designs, develops, manufactures and services automated test systems that support the aerospace, defense, communications and mass transit industries, as well as training and simulation equipment for commercial and military applications.
Number of employees: 2,700
Major customers include large aircraft manufacturers such as Boeing and Airbus, airlines and the military.
Favorable conditions in defense and commercial aerospace support growth. Rising global defense budgets are sustaining demand for military aircraft programs, while the continued expansion of air travel is encouraging airlines to invest in cabin upgrades such as in-seat power and flight connectivity - areas that align with Astronics' core competencies. These trends provide a solid foundation for further expansion.
The company benefits from long product lifecycles, high switching costs and established customer relationships, creating sustainable competitive advantages and recurring revenue opportunities. As aerospace market conditions improve, these strengths support multi-year growth and margin recovery potential.
Management is focused on increasing margins through cost discipline, supply chain stabilization and prudent capital allocation. Increasing production volumes should support operating leverage, margin expansion and stronger free cash flow. The aerospace segment, which generates the majority of sales, is growing steadily and a solid backlog increases sales visibility. Astronics' projected 2026 revenue range of $950 million to $990 million reflects continued defense spending and ongoing airline modernization activities.
However, supply chain constraints - including raw material shortages, higher operating costs, labor constraints and rising US tariffs - may put pressure on production schedules and delay deliveries, which could impact near-term performance.
Despite these risks, Astronics' return on invested capital (ROIC) of 15.8% is well above the industry average of 3.3%. This underlines the company's strong capital efficiency and effective use of resources compared to its competitors.
Astronics is poised to grow through its niche focus, proprietary technologies and presence in secular growth trends in the aerospace sector.
Serving global customers
Astronics provides solutions to leading companies worldwide, including:
- Airbus,
- American Airlines
- Bell Helicopters
- Boeing
- Carson, Helicopters,
- Cirrus Aircraft
- Collins, Aerospace
- Comlux
- Dassault Aviation
- Delta Air Lines
- Embraer
- General Dynamics
- Gogo
- Gulfstream
- Intelsat
- L3Harris
- Leonardo
- Lilium
- Lockheed Martin
- NYC Transit Authority NASA
- Panasonic Avionics
- Raytheon Technologies
- Safran
- Sikorsky
- Southwest Airlines
- Textron
- Thompson Aero Seats
- United Airlines
- U.S. Army/Navy/Air Force/Marines
- ViaSat
Astronics Corporation Brochure
- Products & Solutions
- Elektrische Antriebssysteme für Flugzeuge
- Individuelles Design & Fertigung
- Notfallsysteme
- IFC-Antennen und Radomsysteme
- Hardware des Bordunterhaltungssystems
- Instrumentierung
- Innenräume & Strukturen
- Beleuchtungssysteme
- Sitzaktuierungssysteme
- Simulation & Training
- Systemzertifizierung
- Test & Messung
- VIP IFEC & CMS-Systeme
- Subsidiaries & Affiliates
- Astronics Advanced Electronic Systems
- Astronics AeroSat
- Astronics Ballard-Technologie
- Astronics Konnektivitätssysteme und Zertifizierung
- Astronics individuelle Steuerungskonzepte
- Astronics DME
- Astronics Luminescent Systems Inc
- Astronics PECO Inc
- Astronics PGA
- Astronics-Testsysteme
Latest News
April 13, 2026 - 4:20 pm EDT
Astronics ausgewählt, um die Zugangstüren zu den Kraftstofftanks für die Boeing 737 MAX zu liefern
Astronics Corporation meldet starkes Ende des vierten Quartals bis 2025
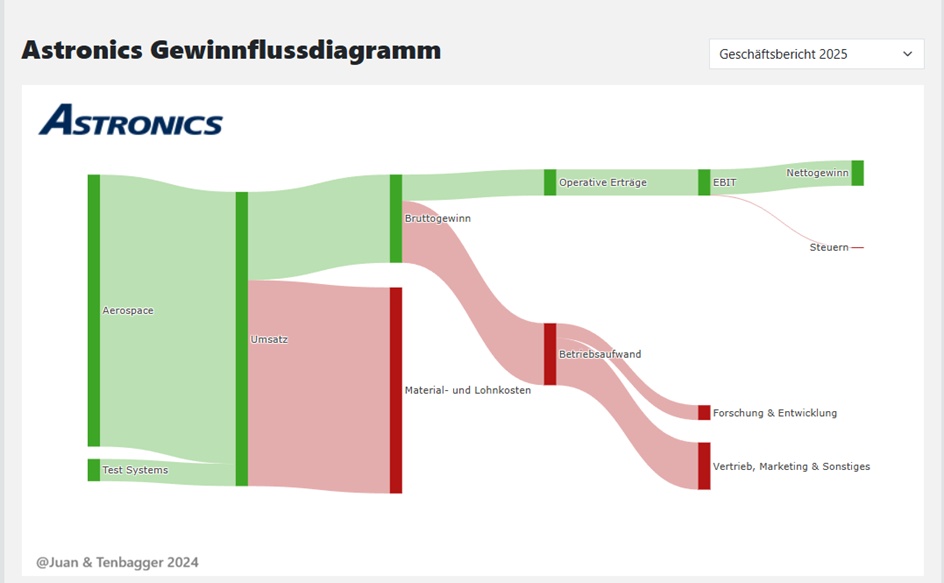
Distribution of turnover by business division:
2025 (USD)
Aerospace 797 million
Test Systems 65.24 million
Geographical distribution of sales:
2025 (USD)
USA 615 million
Europe 153 million
Asia 73.26 million
North America (Excluding USA) 14.64 million
Other 3.62 million
South America 2.12 million
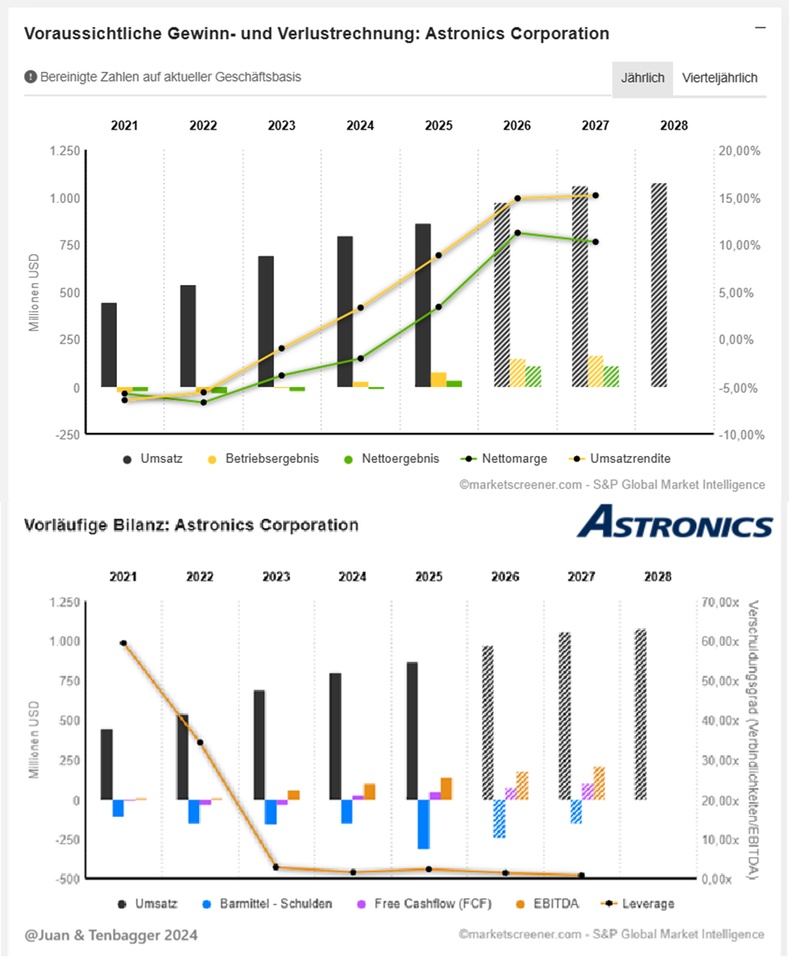
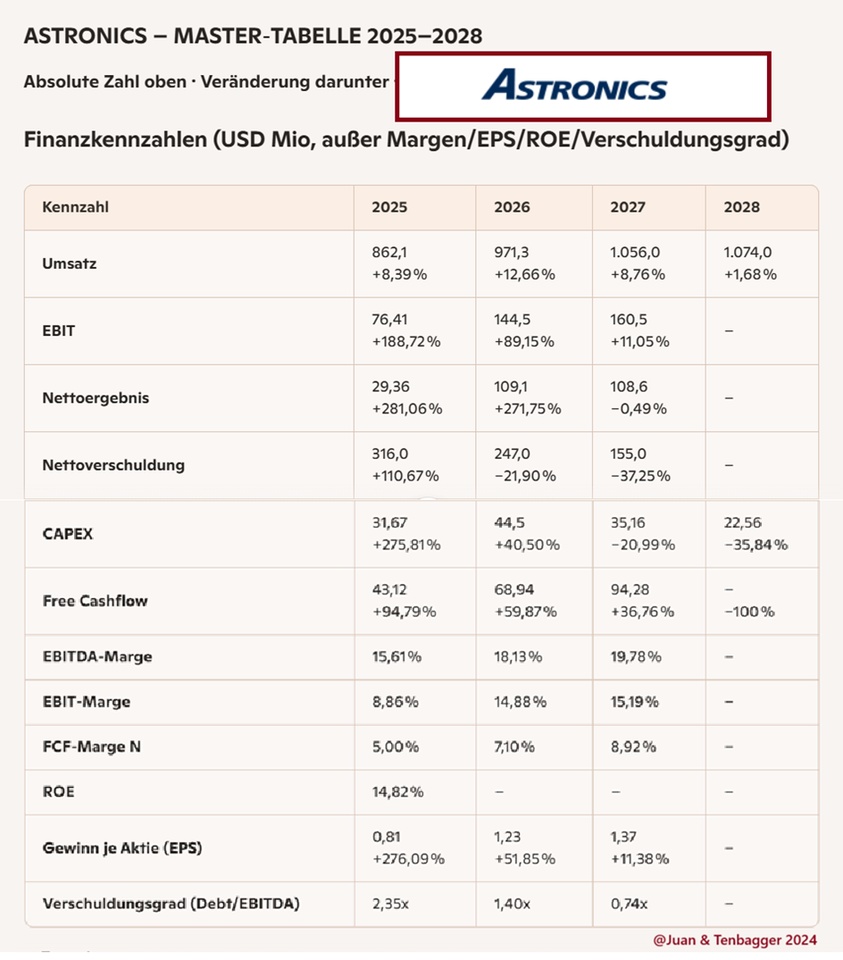
Juan's conclusion on the Astronics key financial figures (2025-2028)
(compact, direct, investor-focused - as you would expect from Juan)
Astronics delivers a classic turnaround profilethat really picks up speed in 2025-2027. Turnover continues to grow steadily, but the real game changer is the margin explosionEBIT jumps from 26 million (2024) to 76 million (2025) and then to 144 million (2026). This is not normal growth - this is operating leverage in its purest form.
Free cash flow turns cleanly positive and rises to over 94 million by 2027. At the same time, net debt falls from 316 million to 155 million - a massive de-leveraging effectwhich significantly reduces the risk in the business model. The gearing ratio is practically halved every year.
The margins show that the business model is working again: EBITDA margin 2025-2027 of 15.6 % → 18.1 % → 19.8 %. This is surprisingly strong for an aviation supplier surprisingly strong. EPS shows triple-digit growth and confirms the operational recovery.
2028 is missing some estimates, but the trend until 2027 is clear: Astronics is in a structural recovery phase with strong cash flow momentum and decreasing risk. For investors, this is a typical setup in which the valuation is often late to catch up.
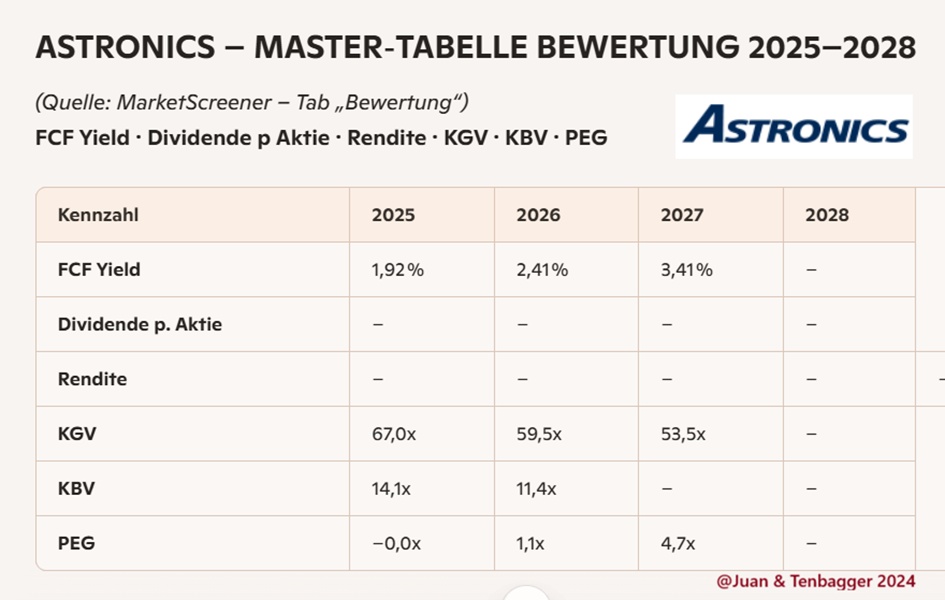
Market value 2,611
Number of shares (in thousands) 35,874
Date of publication 24.02.2026
Juan's conclusion on the valuation ratios (Astronics)
(short, snappy, investor-focused - a perfect match for the valuation table)
From a valuation perspective, Astronics looks like a classic turnaround case that has not yet arrived in the share price. The FCF yield has risen from a meagre 1.9% to a solid 3.4% by 2027 - a clear indication that the cash flow leverage is working while the market is still hesitant.
The P/E ratio remains high (67x → 59x → 53x), but this is typical for companies that have just only just returning to profitability. The valuation prices in the risk of the past, not the dynamics of the future. P/B ratio falls from 14.1x to 11.4x - still expensive, but the trend shows Valuation is normalizing while operating momentum is rising.
PEG 2026 at 1.1x is the only real valuation anchor - 2027 at 4.7x shows that growth is flattening but not collapsing. Dividend? Zero. Yield? Zero. The company is investing every dollar in the turnaround - and you can see that in the figures.
Bottom line: Astronics is not a bargain in terms of valuationbut a classic re-rating candidateif cash flow, margins and de-leveraging continue to deliver. The valuation is lagging behind the operating momentum - and this is where the best opportunities often arise.
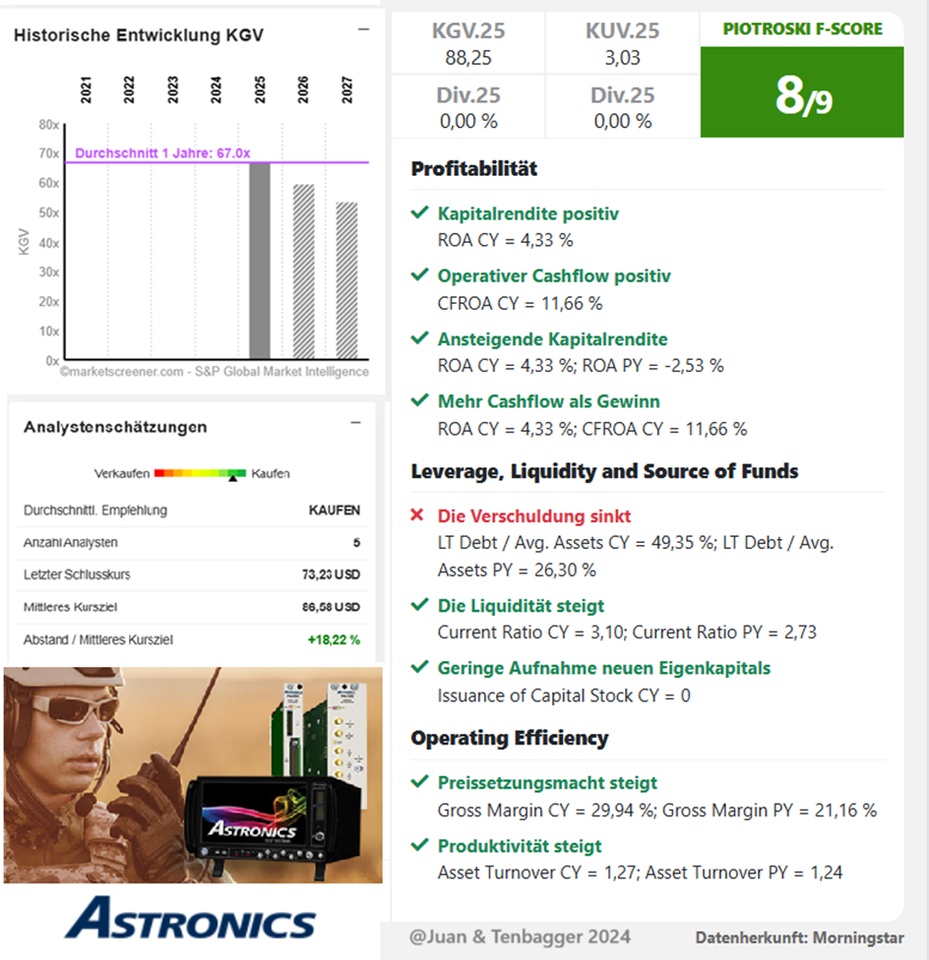
Performance:
1 week -4.86 %
1 month +7.91 %
6 months +45.56 %
1 year +245.42 %
3 years +366.73 %
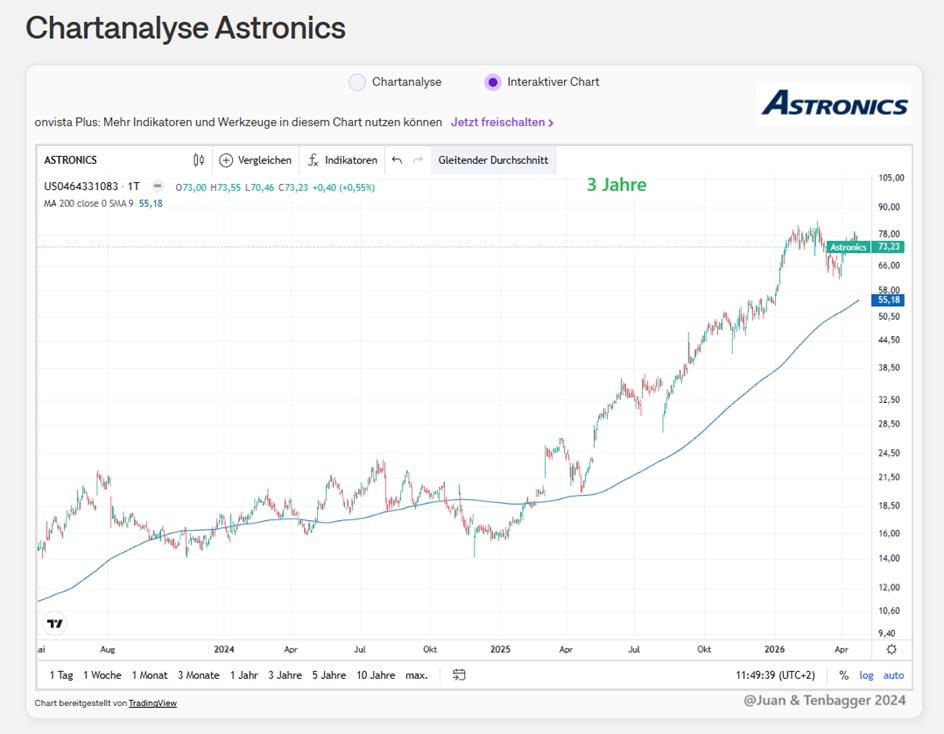
COURSE 62.00€ (27.04.2026 at 13:16)