While the market has been obsessed with high-flying AI hardware, a significant opportunity has emerged in the fintech sector. Shift4 Payments (FOUR) is currently trading at what I consider a "valuation disconnect"—offering high-growth performance at a value-stock multiple.
1. The Core Thesis: Dominance in Complex Environments
Shift4 isn't just another payment processor; it owns the "difficult" verticals. From massive sports stadiums and theme parks to complex hotel ecosystems, FOUR’s software integration (SkyTab) creates a high-moat business. Once a stadium or a Hilton hotel integrates Shift4’s end-to-end stack, the switching costs become prohibitive.
2. The Global Blue Game-Changer
The recent acquisition of Global Blue is the most misunderstood part of the story.
- Global Reach: FOUR has pivoted from a US-centric player to a global powerhouse in 50+ countries.
- Luxury Synergy: They now control the tax-free shopping technology used by international luxury travelers. The cross-selling opportunity here is estimated at over $500B in payment volume.
3. Unrivaled "Earning Power" vs. Price
The numbers tell a story of extreme undervaluation:
- Forward P/E: Trading at ~14.5x 2026 earnings, while growing EPS at a 40% CAGR.
- Free Cash Flow: Management is targeting a $1B FCF exit rate by late 2027.
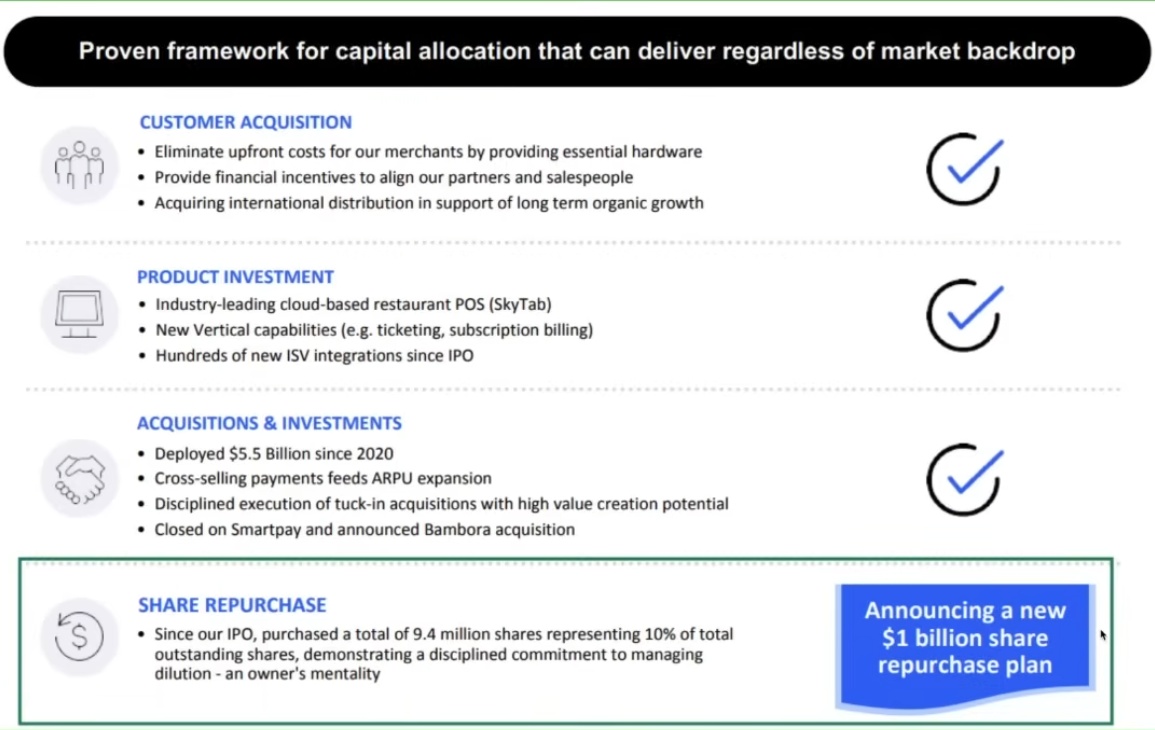
- Shareholder Alignment: The company recently authorized a $1B share buyback, effectively signaling that they believe the stock is significantly "on sale."
4. Why is it cheap right now?
The "Bear Case" rests on short-term noise: integration risks of Global Blue and the CEO's extracurricular activities (NASA). However, the fundamentals show a "core engine" that continues to compound at 30% revenue growth regardless of the headlines.
The Verdict
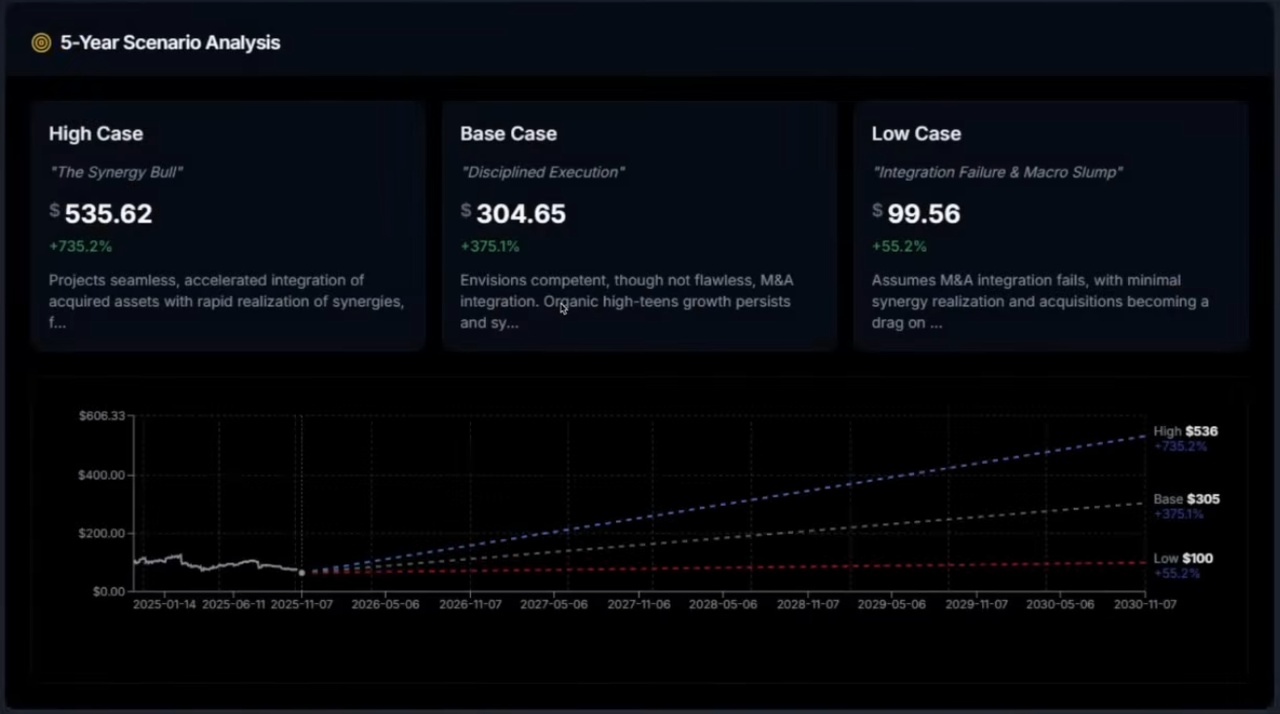
Shift4 is a Spring-Loaded Stock. With the 2026 World Cup (a massive catalyst for their stadium vertical) on the horizon and the realization of Global Blue synergies, the current price in the $60s offers a rare margin of safety for a growth leader.
Disclosure: I am biased. I’ve started building a position because I believe the risk-to-reward ratio here is one of the best in the mid-cap fintech space today.