
Record turnover, profit and cash flow. Takeover bids, million-euro purchases by the founder - but the share price continues to fall. Why?
Takeover bids rejected, insider purchases made
Sometimes the strangest things happen on the stock market. Recently, Shift4 Payments rejected several takeover bids, which according to press reports were at USD 120-130, and today the stock is trading at half that price.
The founder, longtime CEO and largest shareholder recently bought shares for $7.51 million at $81.90 and another $8.75 million at $83.61.
Even he would probably never have dreamed that the share price would subsequently fall much lower.
Looking at the business figures, one inevitably wonders why the share price fell at all. Apart from a slight shortfall in profit in one of the last four quarters, Shift4 Payments has consistently delivered.
Beyond that, the question for an investor is how important achieving consensus estimates is anyway.
What really matters is that the company is on the up - and no one can deny that with Shift4 Payments, even if last Thursday's share price reaction suggests otherwise.
Massive growth and new major customers
At USD 1.47 per share, Q3 earnings exceeded expectations of USD 1.45. With sales of USD 589 million, analysts' estimates of USD 580 million were also exceeded.
For the year as a whole, this corresponds to a 61% increase in sales and a 6% rise in profit. However, the figures are difficult to compare due to the acquisition of Global Blue. Without the acquisition, turnover would have risen by 19 %.
The transaction volume increased by 26% to USD 54.7 billion over the year.
Free cash flow improved by 27% to USD 141 million.
Shift4 Payments recently acquired an average of 1,300 new customers per month, including many restaurants and small and medium-sized businesses (SMBs) as well as major customers.
In the last quarter, for example, the company acquired Hyatt Vacation Club as a customer with more than 20 resorts and secured orders for more than half a dozen stadiums.
Outlook and valuation
The forecast for the current financial year has been confirmed and specified. The value of all transactions processed this year is expected to be USD 207-210 billion, revenue USD 1.98-2.02 billion, EBITDA USD 970-985 million and free cash flow at least USD 485 million.
Shift4 Payments therefore has a forward P/FCF of 12.4 or less. In the last three years, since the company made the leap to profitability, the P/FCF has averaged 20.
In the coming year, free cash flow is also expected to increase by more than 30 % to more than USD 7 per share. In turn, the P/FCF would fall to 9.5 or less.
The company has therefore decided to buy back shares with a volume of USD 1.0 billion. This would currently be enough to cancel more than one sixth of all outstanding shares
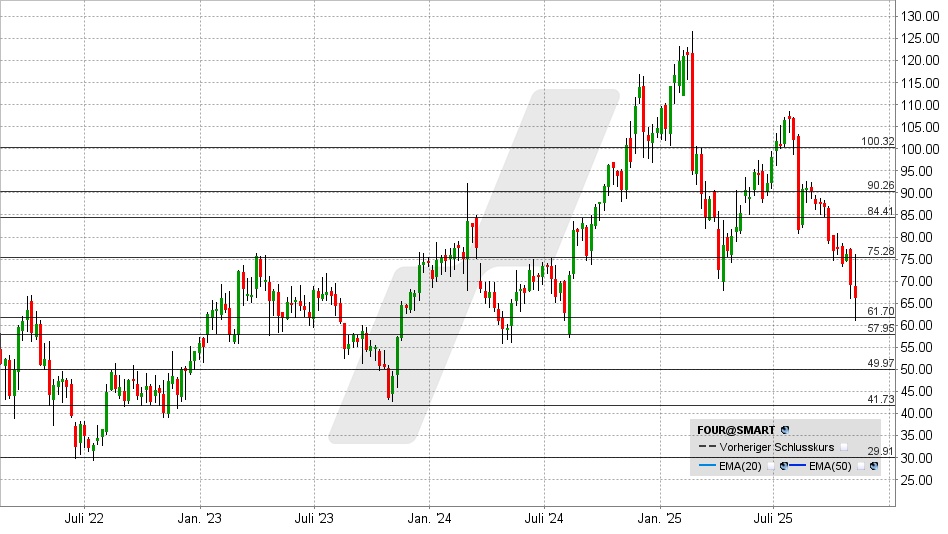
Shift4 Payments share: Chart from 10.11.2025, price: USD 66.15 - symbol: FOUR | Source: TWS
From the bulls' perspective, the share price should not fall below USD 58. If it does, however, the correction is likely to extend towards USD 50.
If, on the other hand, it manages to return above USD 67, the situation will ease and a recovery to USD 70 or 75 will be possible. The chart picture brightens sustainably above this level