Continuous AI recovery is the only way to consistently restore a company to its fullest potential.
Hello, everyone,
On days when investors are punishing companies with double-digit declines in earnings due to falling and negative free cash flow, I spent the weekend looking for a company where we see exactly the opposite. This company was already introduced here a few months ago by our dear @Multibagger .
This company is the market leader in data backup and recovery. Its software is considered one of the best backup and recovery solutions in the industry. Last quarter, the company surpassed the 8,000-customer mark.
What I like is that Commvault has successfully transitioned to a subscription-based model. This leads to more predictable revenue (ARR).
Key growth drivers include the expanding market for cyber resilience, the breadth of the partner ecosystem, and ongoing innovations in AI.
Commvault Systems, Inc.. is a provider of cyber resilience and data protection solutions. The company helps businesses protect, secure, and recover their data, applications, and identity systems from cyber threats and attacks. It delivers its solutions via the Commvault Cloud, a cloud-native platform that combines data security, cyber recovery, and identity resilience across on-premises, hybrid, multi-cloud, and Software-as-a-Service (SaaS) environments. The company offers a range of features designed to help customers prepare for, weather, and recover from cyber incidents such as ransomware, data corruption, infrastructure failures, and cyberattacks. Commvault Cloud offerings are divided into three packages: Operational Recovery, Autonomous Recovery, and Cyber Recovery. Operational Recovery provides core backup and recovery capabilities for hybrid enterprise workloads. The offerings include Commvault Cleanroom Recovery, Commvault HyperScale Grid, and others.
Number of employees: 3,300
8a85effd-e160-46f0-957b-a034fdc99598
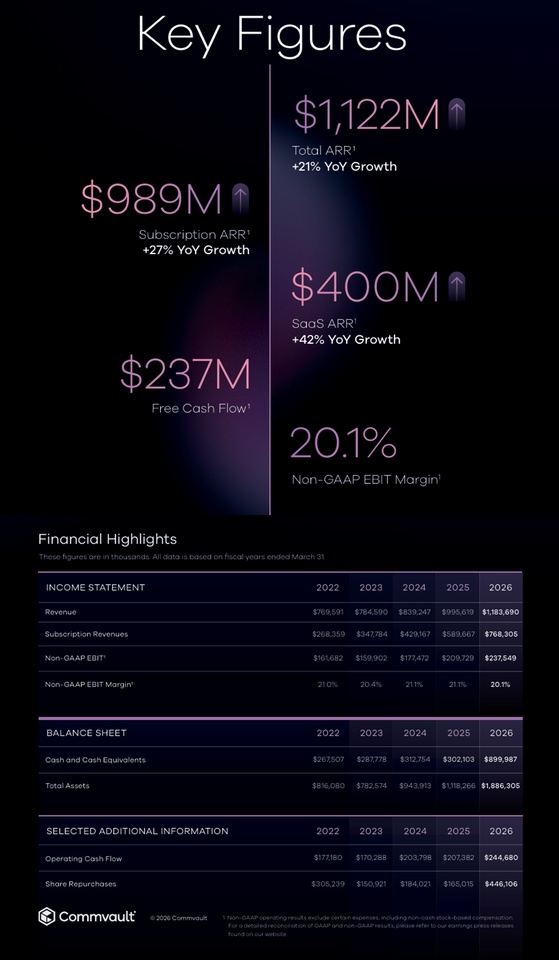
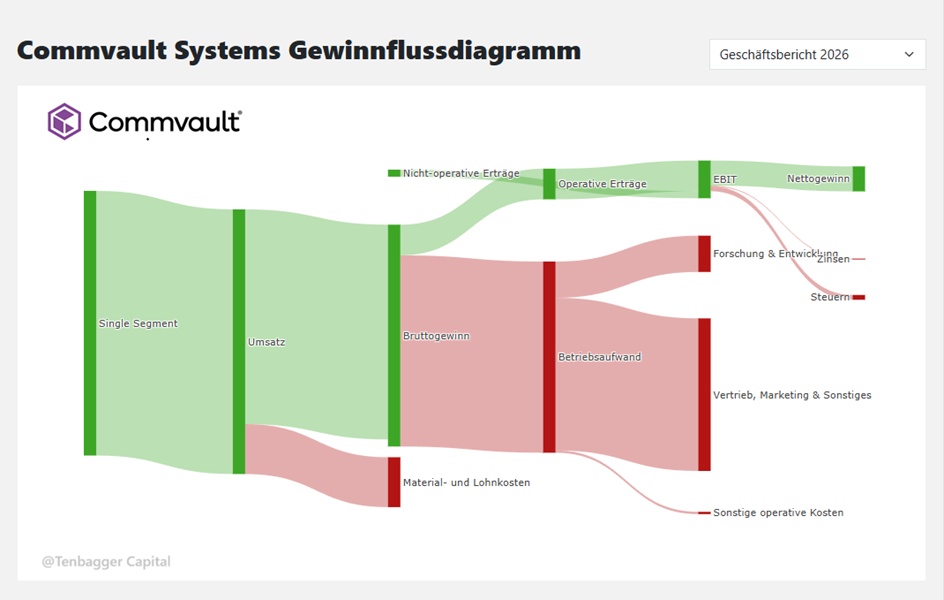
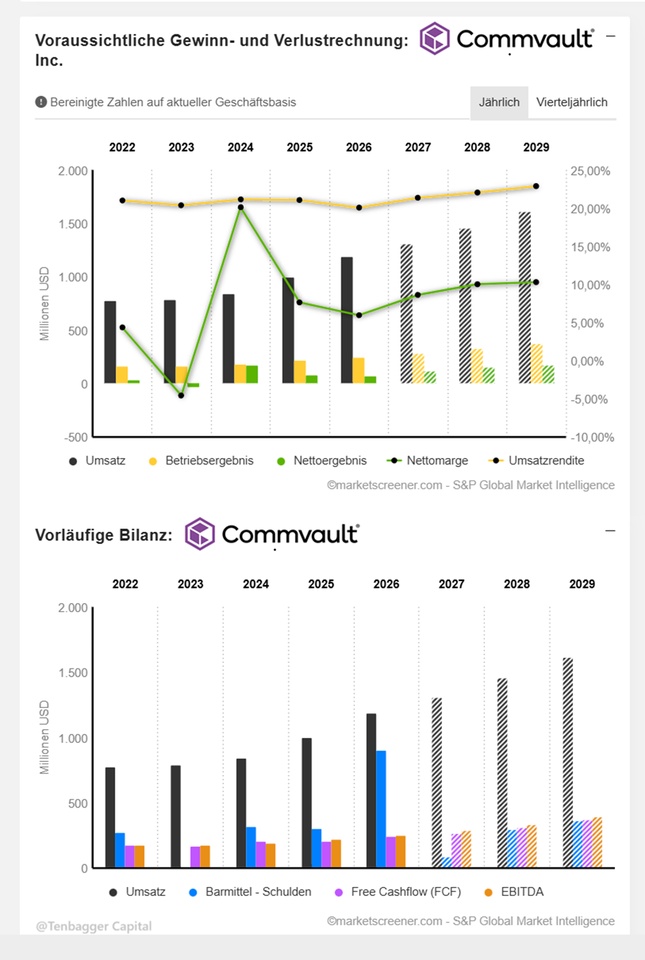
In the last fiscal year, Commvault Systems Inc.’s revenue rose by 18.9%, from $995.6 million to $1.2 billion. Meanwhile, net income fell by 7.2%, from $76.1 million to $70.7 million. The net profit margin was thus 6.0%, compared to 7.6% in the previous year. On October 28, 2026, Commvault Systems Inc. reported its Q3 results for the quarter ending September 30, 2026. Revenue for the reporting period was $312.4 million (+13.1% compared to the same quarter last year), and net income was $29.1 million (+97.6% compared to the same quarter last year).
DA Davidson Raises Commvault’s Price Target Due to Strong Subscription Growth
Published on October 28, 2026
Summary of the report on Commvault Systems (CVLT):
Key Points
- DA Davidson has raised the raised its price target from $185 to $210 and reaffirmed its “Buy” rating. [investing.com]
- This was due to better-than-expected quarterly results. The newly acquired subscription-based annual recurring revenue (Subscription Net New ARR) amounted to $51 million, while analysts had expected only about $43.5 million . [investing.com]
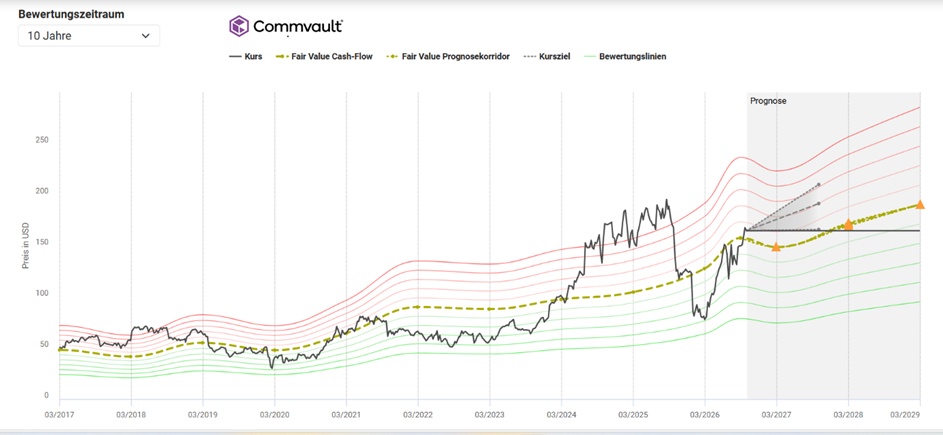
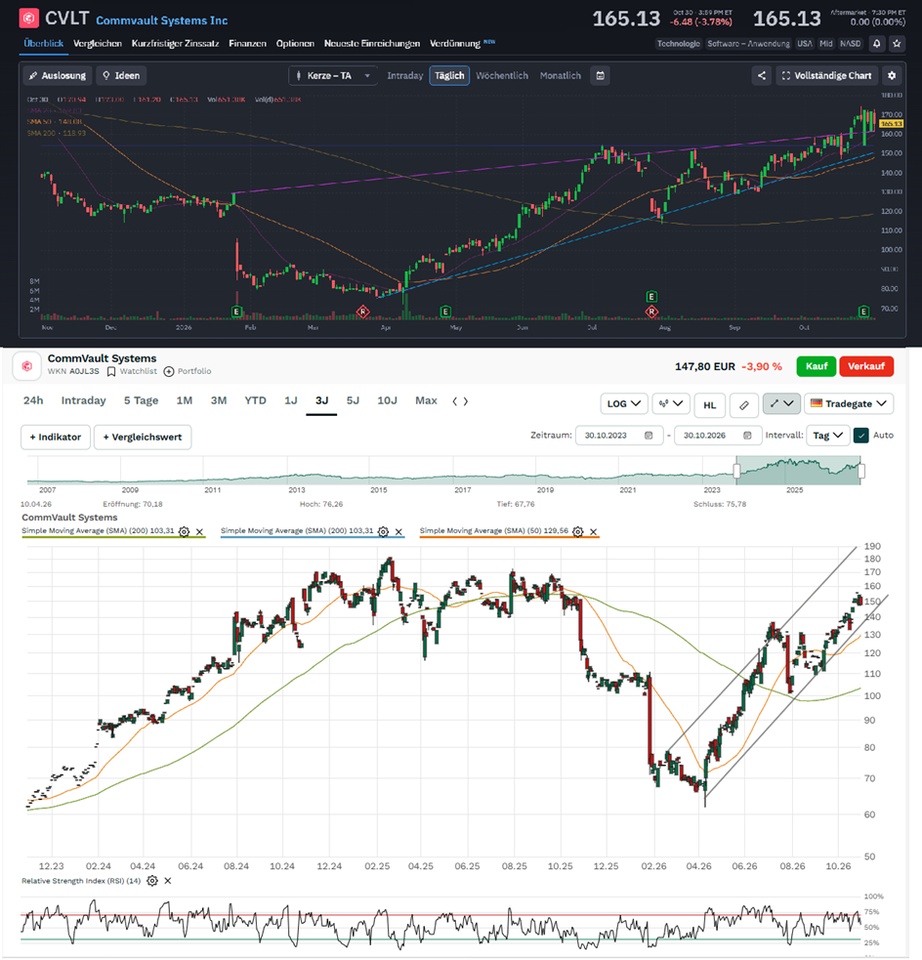
- At the time of this report, the stock was trading at around $169.52 , just slightly below the 52-week high of $174.25. Over the previous six months, it had gained approximately 76% gain . [investing.com]
Why Analysts Are Becoming More Optimistic
- Some investors were concerned that SaaS growth was slowing.
- DA Davidson considers these concerns to be exaggerated following the quarterly results.
- From the analysts’ perspective, the outlook for the second half of the year now even appears conservative—that is, set on the cautious side. [investing.com]
- Sustainable growth in subscription revenue is still expected in the range of the high teens to about 20% per year. [investing.com]
More positive news
- Also, Guggenheim raised its price target following the earnings report, from $175 to $200, while maintaining its positive rating. [investing.com]
- Commvault reported the following for the quarter:
- Earnings per share: $1.38 (Estimate: $1.24)
- Revenue: $312.39 million (expectation: $310.24 million) [investing.com]
Conclusion for Investors
The report is clearly bullish. Several analysts view Commvault’s operational performance as stronger than expected. Recurring cloud and subscription revenue, in particular, is performing very well. The only downside: According to the InvestingPro rating mentioned in the article, the stock may already be overvalued . [investing.com]
Juan’s verdict: 🟢 A quality stock with strong momentum, rising estimates, and robust ARR growth. Fundamentally, it is currently one of the stronger software stocks in the cybersecurity/data protection sector. [investing.com]
Geographic Revenue Breakdown:
2026 (USD)
United States 631 million
Other 553 million
Company: Commvault Systems
WKN: A0JL3S
ISIN: US2041661024
Source: Exclusively MarketScreener – Finanzdaten Commvault Systems
The fiscal year ends in March. All financial figures are in millions of USD, as MarketScreener reports the data in USD.
Date of publication: April 28, 2026
5. My Assessment of the 2036 Portfolio
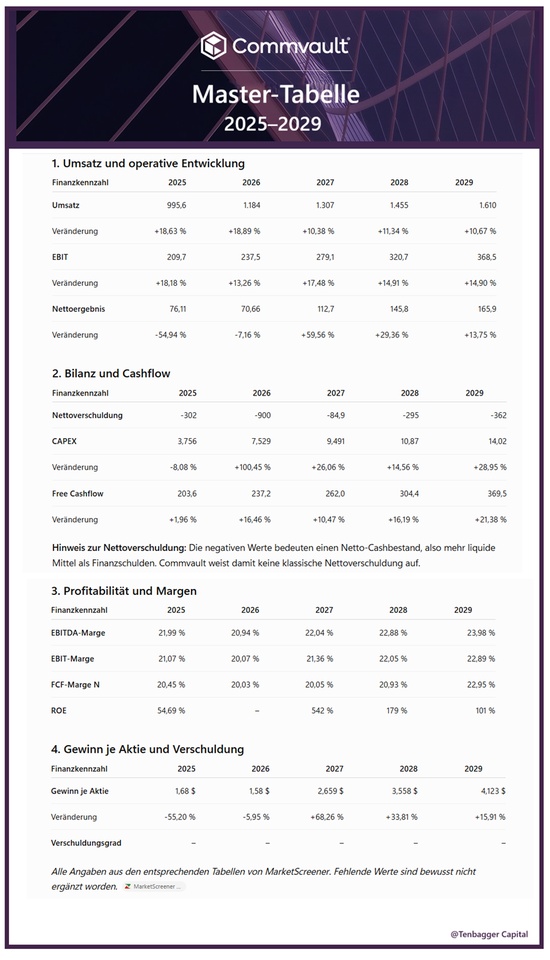
Commvault shows an interesting growth profile. Three points in particular stand out:
1. Revenue growth
- 2025: $995.6 million
- 2029: $1,610 million
- Growth over four years: approximately 62%.
2. Operating Performance
EBIT grows from 209.7 to 368.5 million USD. Particularly positive: EBIT is growing faster than revenue.
The EBIT margin rises from 21.07% to 22.89%.
3. Free Cash Flow
Free cash flow increases from 203.6 to 369.5 million USD.
This corresponds to growth of approximately 81.5%.
This is a strong sign for a software company.
My Conclusion
Criterion
Assessment
Revenue Growth
🟢 Good
EBIT growth
🟢 Very good
Margin Performance
🟢 Positive
Free cash flow
🟢 Very strong
Balance Sheet
🟢 Net Cash
Earnings Growth
🟢 Strong starting in 2027
ROE
🟡 Remarkably high
My verdict: From a fundamental perspective, Commvault is an interesting candidate for the second wave of AI.
I find the combination of data security, backup, cyber resilience, and the growing importance of AI-generated data particularly exciting.
However: Earnings growth in 2025/2026 is weaker than operational performance. This should be taken into account in the valuation.
For the 2036 portfolio, Commvault would be an interesting candidate for me in the AI data security and cybersecurity sector.
An important caveat: These figures are company forecasts from MarketScreener, not guaranteed results.
What I particularly like:
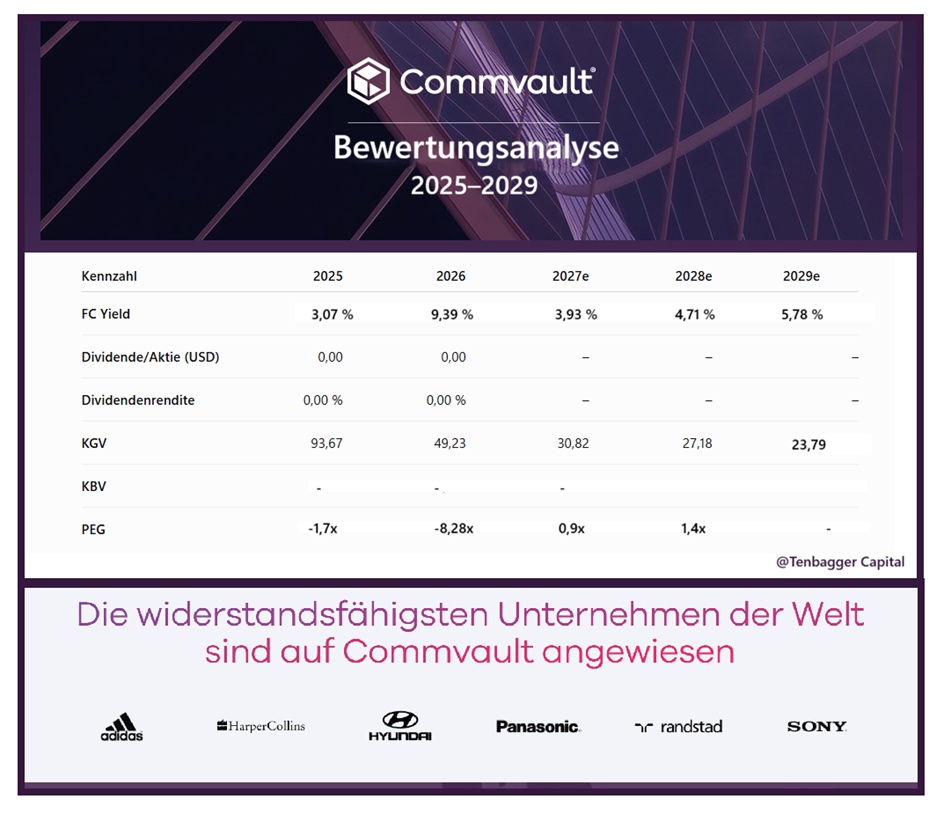
1. Free cash flow yield
From 3.07% (2025) to 5.78% (2029).
This is a positive trend. Commvault is becoming increasingly attractively valued relative to its expected free cash flow.
What stands out, however, is the jump to 9.39% in 2026 and the subsequent decline. Here, I would keep an eye on the underlying cash flow estimates.
2. P/E Ratio – Significant Improvement
- 2025: 93.67
- 2026: 49.23
- 2027: 30.82
- 2028: 27.18
- 2029: 23.79
That represents a significant easing of the valuation.
If Commvault meets its earnings forecasts, the stock could reach a much more reasonable valuation level by 2029.
3. PEG – particularly attractive right now
2027: 0.9x
2028: 1.4x
A PEG below 1 is often considered attractive, provided that the expected earnings growth is sustainable.
The negative values for 2025 and 2026, however, should not be interpreted as a favorable valuation. They result from negative earnings growth rates and are difficult to interpret meaningfully.
Particularly exciting: Commvault has confirmed and updated its annual forecast for fiscal year 2027:
- Subscription revenue: $1,127–1,133 million
- Subscription ARR: $1,205–1,215 million
- Free cash flow: $255–265 million
- Non-GAAP EBIT margin: 21–21.5%
I like that. The company isn’t just growing—it’s also generating solid cash flow.
3. My Assessment for Portfolio 2036
Criterion
Rating
Revenue Growth
🟢 Very interesting
SaaS growth
🟢 Very strong
Free Cash Flow
🟢 Very good
FC Yield
🟢 Improvement
P/E Ratio
🟢 Significant decline
PEG 2027
🟢 Attractive
Balance Sheet / Liquidity
🟢 Strong
Dividend
⚪ None
Valuation Risk
🟡 Still present
4. My Conclusion: Buy or Watch?
I now see Commvault as an interesting candidate for the second wave of AI.
Why?
AI is generating more and more data. Companies need to be able to protect, back up, manage, and—in an emergency—restore this data.
This is precisely where Commvault’s business model comes in.
I find three areas particularly exciting:
AI data security: Protection of increasingly complex corporate data.
Cyber resilience: Recovery from cyberattacks and ransomware.
Cloud and SaaS: Recurring revenue and increasing customer loyalty.
My biggest selling point is the combination of 33% SaaS growth and rising free cash flow.
My decision for the 2036 portfolio:
I’m going to add Commvault to my shortlist of stocks to buy. The P/E ratio of 23.79 for 2029 and the PEG ratio of 0.9 for 2027 look interesting.
However, I won’t buy blindly based on future metrics. The forecasts still need to be earned.
My verdict: Fundamental growth is solid, and the valuation is becoming more attractive—Commvault deserves a spot on the watch list.
The key question now is whether the market will once again assign the company a higher valuation as soon as the projected earnings growth is reflected in the actual quarterly results.
Dear readers,
I look forward to hearing your thoughts in the comments.