✅ Earnings Exceeded Expectations
- Non-GAAP EPS (earnings per ADS) was $0.37 , exceeding analysts’ estimates by $0.01. [three.ws], [alphathinker.app]
✅ Very strong revenue growth
- Revenue reached NT$244.16 billion. [three.ws], [alphathinker.app]
- Compared to the previous year, this represents growth of 44.8%. [coinunited.io]
- Compared to the previous quarter, revenue rose by 27.8%. [coinunited.io]
✅ AI boom as a growth driver
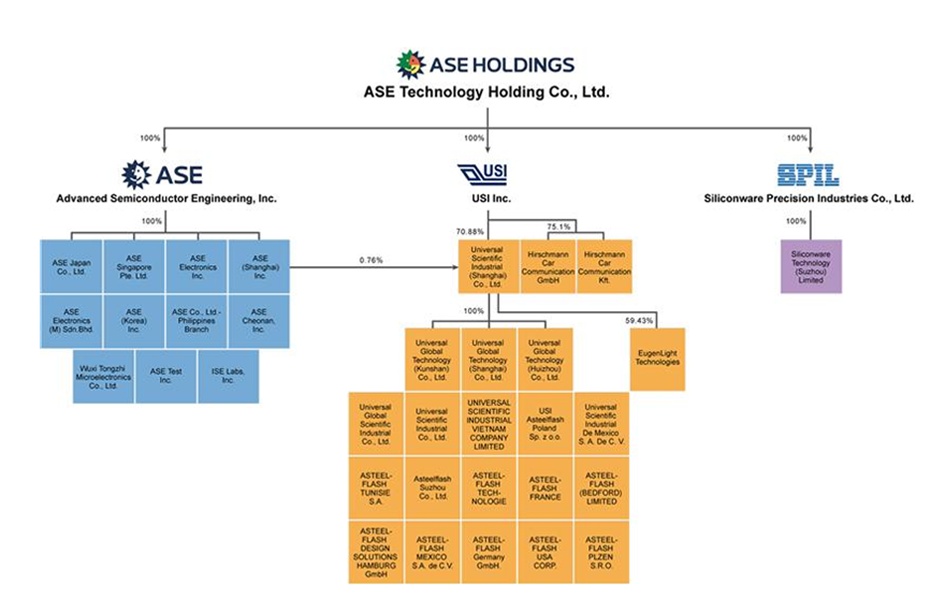
- This growth is driven in particular by the high demand for advanced packaging and AI infrastructure. As the world’s leading provider of Outsourced Semiconductor Assembly & Testing (OSAT), ASE benefits directly from the expansion of AI. [coinunited.io]
✅ Business Mix
- Packaging: approx. 50% of revenue
- EMS: approx. 38%
- Testing: approx. 11%
[coinunited.io]
Particularly important for investors
Positive
- Revenue is growing significantly faster than that of many other semiconductor companies.
- Earnings are above expectations.
- AI packaging remains a structural growth driver.
- Confirms ASE’s strong position in the supply chain for NVIDIA, TSMC, and AI data center projects. [coinunited.io]
What the market is focusing on now
- Outlook for Q4 and 2027.
- Margin performance despite high capital expenditures.
- Capacity expansion in the advanced packaging business.
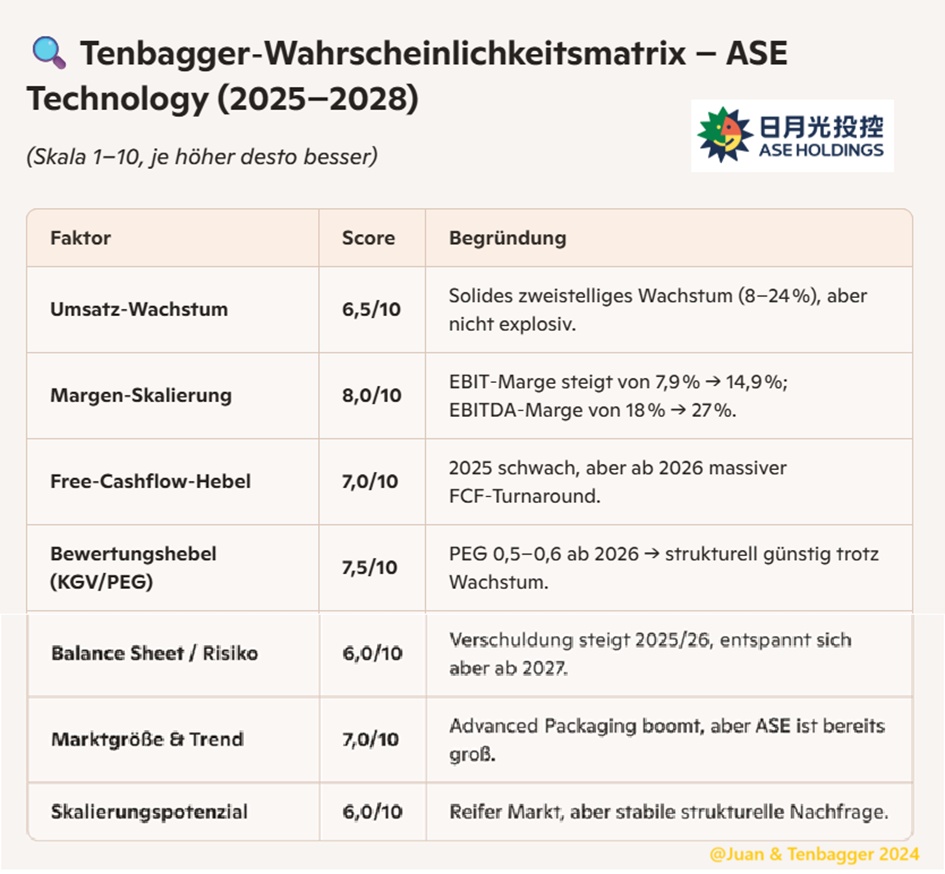
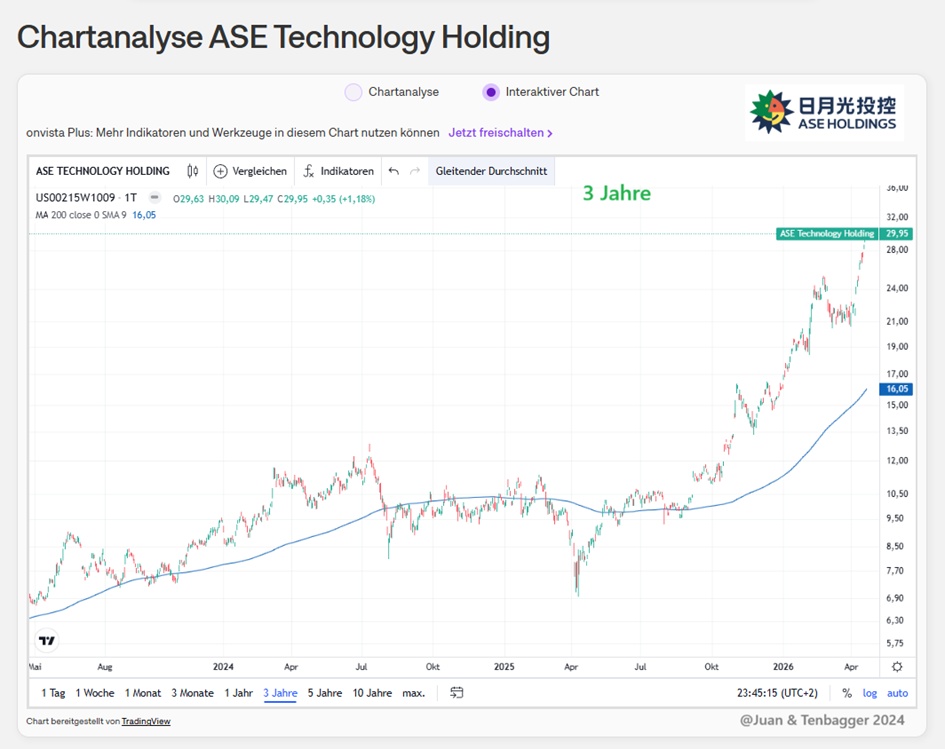
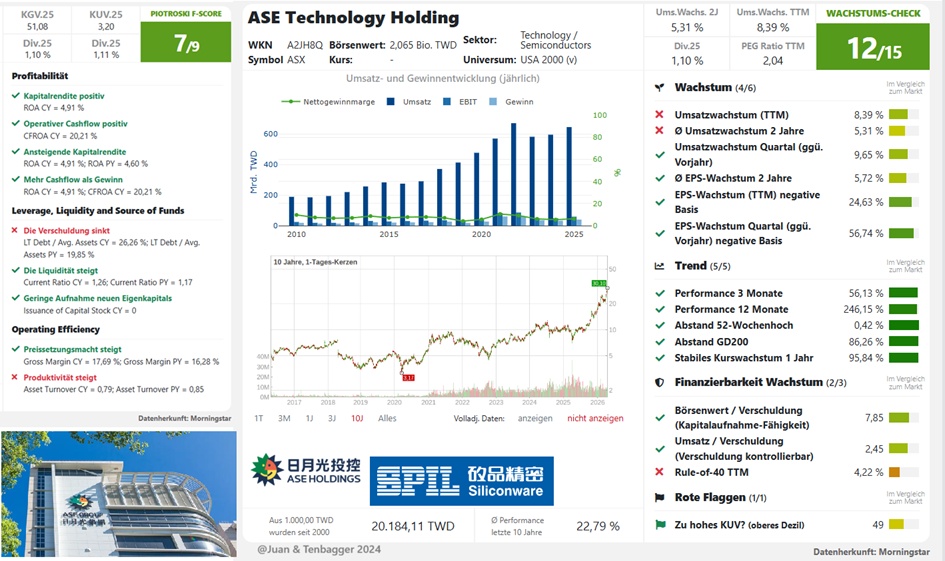
The quarter was clearly positive. Revenue growth of just under 45% coupled with a profit beat shows that ASE is currently one of the biggest beneficiaries of the AI packaging boom. For my tenbagger logic, the most important question remains whether ASE can monetize this growth in the coming years through higher margins and market share gains. Currently, the figures appear to be a confirmation of the ongoing upward trend, not a one-time outlier