Here's the hot stuff from Tristel $TSTL (+0%) (AIM: TSTL) FY 2026 Earnings Release, hot off the press:
🚀 Topline consistently delivers
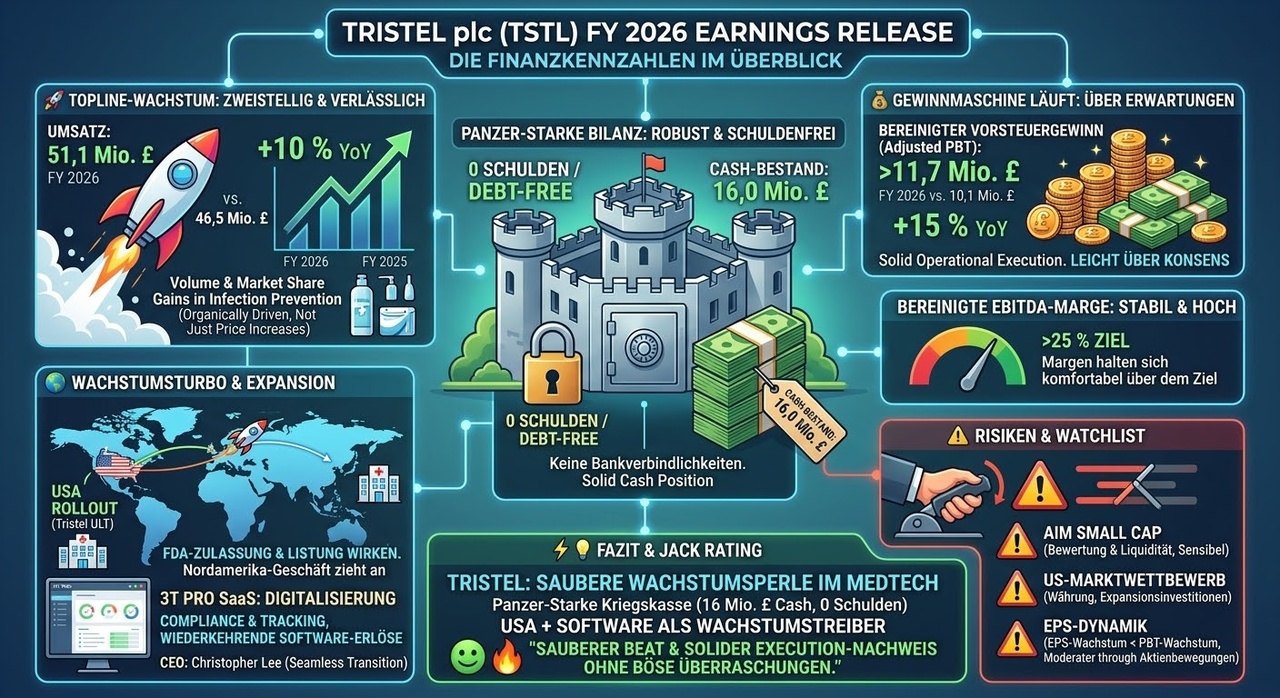
Tristel posted solid, double-digit revenue growth in fiscal year 2026 (ending June 30, 2026):
Revenue: £51.1 million → +10% YoY (compared to £46.5 million the previous year).
This growth is organically driven—by genuine volume and market share gains in the infection prevention segment, not by mere price hikes.
💰 Profit engine running smoothly and on target
The bottom line also shows encouraging figures, which were slightly above the original consensus expectations:
Adjusted pre-tax profit (Adjusted PBT): Over £11.7 million (or >£11.5 million) → approx. +14% to +15% YoY (previous year: £10.1 million).
Cash & Balance Sheet: Extremely solid position with cash reserves of £16.0 million—and still completely debt-free.
Gross / EBITDA Margin: The adjusted EBITDA margin remains stable and comfortably above the 25% target.
🌍 U.S. Expansion & Digitalization as the Next Growth Driver
The most important point beyond the raw numbers:
U.S. Rollout (Tristel ULT): FDA approval and the official inclusion of chlorine dioxide in U.S. hospital guidelines for ultrasound probes are having an impact. The North American business is picking up noticeably and offers significant growth potential for the coming years.
SaaS & Software (3T Pro): With the commercial rollout of 3T Pro, Tristel is strategically building recurring software revenue (compliance & tracking) to bind customers even more closely to the product ecosystem.
Leadership Change: CEO Christopher Lee (in office since August 2026) is seamlessly continuing the strategy and keeping the ship on course.
⚠️ But Jack is also applying the brakes
The report is fundamentally sound from an operational standpoint and is encouraging, but a few points remain on the watchlist:
Valuation & Liquidity: As an AIM-listed small-cap stock (compared to U.S. tech giants), the stock is not a sure thing and is sensitive to valuation premiums.
Currency and Expansion Risks: The U.S. market is highly competitive; marketing and sales investments eat into some of the operating leverage in the short term.
EPS momentum: While operating profit (Adjusted PBT) rose by 15%, growth in adjusted earnings per share (EPS) was somewhat more moderate due to share-based adjustments.
⚡💡 Jack’s Conclusion
Tristel delivers exactly what you’d expect from a solid growth gem in the medtech sector: double-digit revenue growth, rising margins, a full war chest, and zero debt. On top of that, the U.S. wild card is slowly but surely paying off.
Not a hype monster like Nvidia, but a top-notch quality stock for your portfolio.
Fundamentals: Very solid.
Balance Sheet: Rock-solid war chest (£16 million in cash, 0 debt).
Growth drivers: U.S. + 3T Pro software.
Valuation: Appropriate for its market position.
Jack’s rating for the earnings report: 🟢🔥 “A clean beat and solid proof of execution with no nasty surprises.”