The dilution has been completed, and I’ve decided to gradually increase my position even further…
A brief overview of the situation:
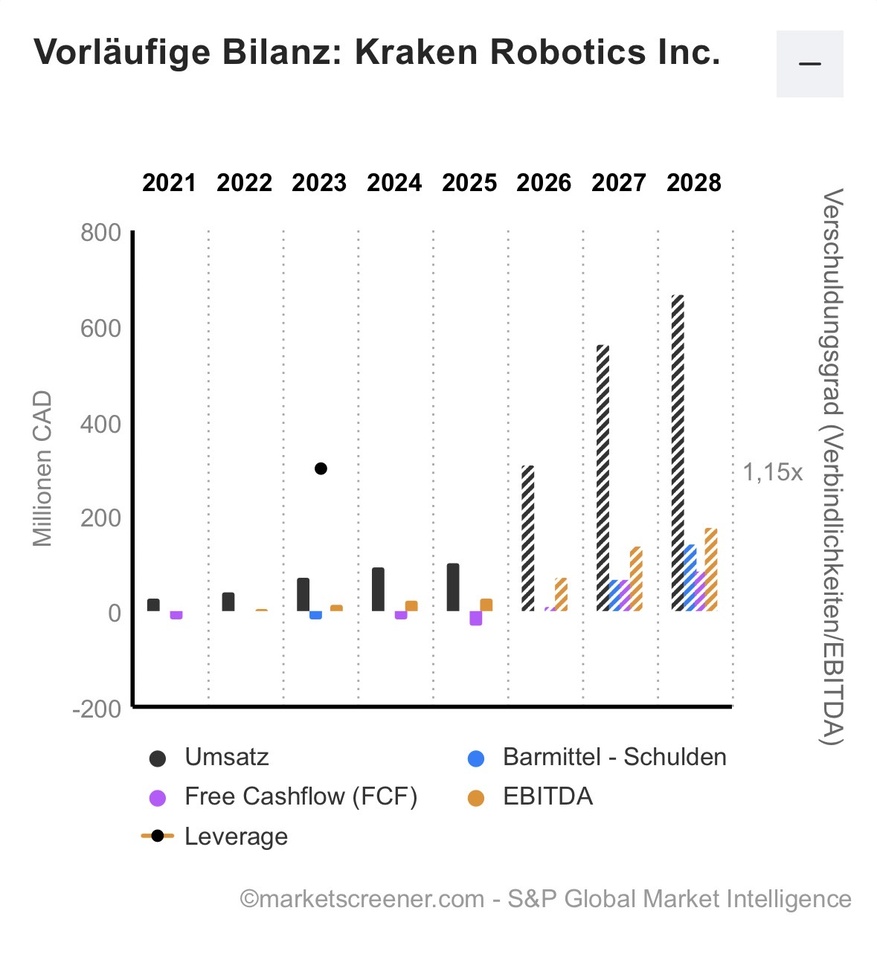
- “Revenue growth: Consensus estimates and company forecasts project a year-over-year annual revenue growth rate (CAGR) of over 50% to nearly 60%. While Kraken was heading toward annual revenue in the range of 100 to 130 million CAD prior to the merger, the adjusted guidance for the full year 2026 (including the second half of the year with Covelya) is already at CAD 290 to 320 million.
For the following year, analysts are targeting further growth from this expanded level, both organically and through cross-selling.
- Revenue and Margin Surge: Since Covelya’s units (such as Sonardyne and Voyis) are operating profitably, analysts estimate that Kraken is now entering a phase of sharply rising
- earnings per share (EPS) and robust adjusted EBITDA margins (around 22–24%). Forecasts project earnings and margin growth of in some cases over 90% per year, as the company realizes economies of scale and fixed costs decline as a percentage of the growing order backlog.”
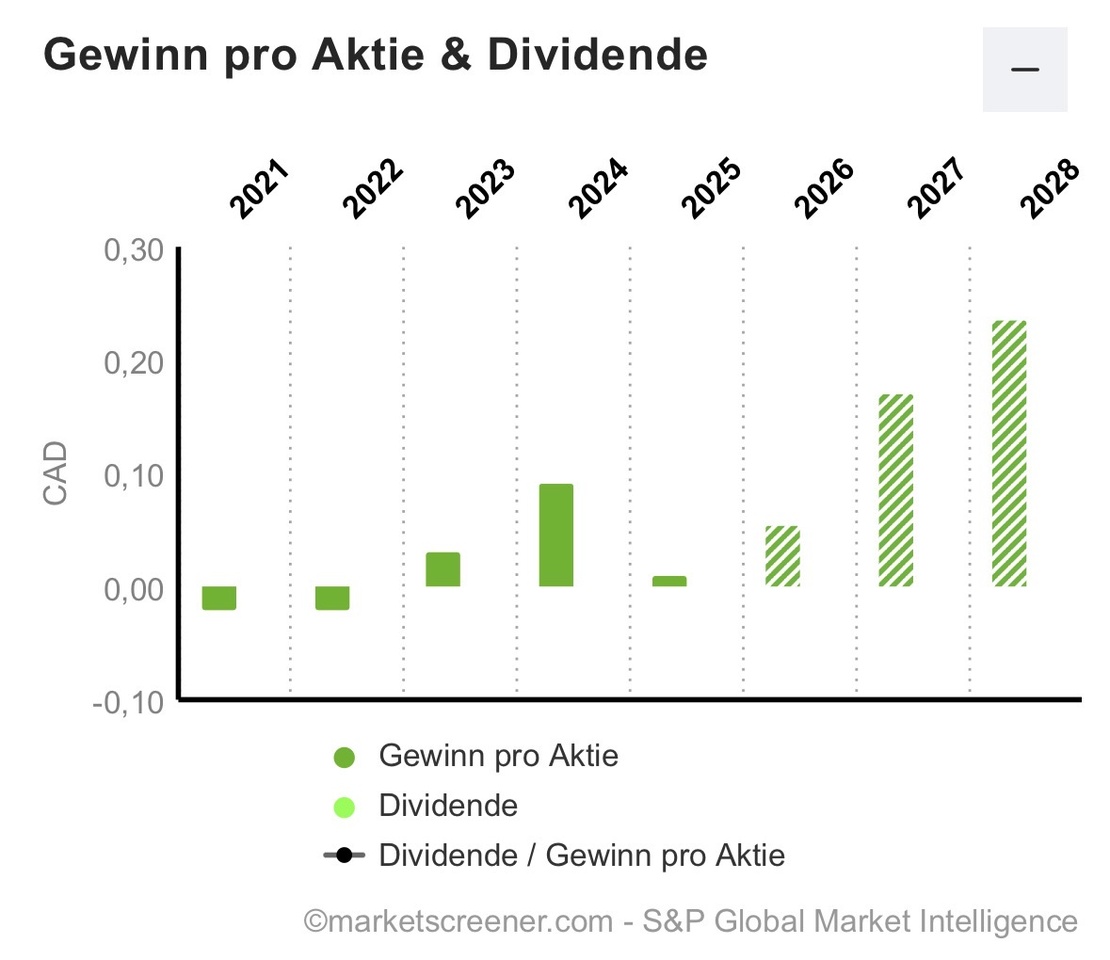
Here’s the earnings per share (important because it already factors in dilution…)
Best regards, Small Investor 😁